


Did Dry Eye Drop Launch Just Shift Alcon's (SWX:ALC) Investment Narrative?
- Alcon has launched Systane PRO Preservative-Free in Canada, a triple action artificial tear formulated with HP-guar, hyaluronic acid, nano-sized lipids, and propylene glycol to provide up to 12 hours of dry eye symptom relief for a broad range of patients.
- This preservative-free product targets an estimated 6 million people with dry eye disease in Canada, reinforcing Alcon's focus on higher value, clinically differentiated eye drop formulations within its Systane franchise.
- We will now assess how Alcon's preservative-free Systane PRO PF launch could influence the broader investment narrative around its eye care portfolio.
Scan for other eye care and health-focused businesses that could be building similar momentum off product launches like Alcon's Systane PRO PF by reviewing our handpicked list of solid balance sheet and fundamentals (204 results).
Alcon Investment Narrative Recap
To own Alcon, you need to believe its mix of surgical equipment and higher value eye drops can keep gaining share despite slower cataract procedure growth and recent margin pressure. The Systane PRO PF launch fits that story but, on its own, looks incremental rather than a swing factor for near term results. The more immediate swing issues remain tariffs, cost discipline, and how fast new products ramp into meaningful volumes.
The biggest risk still sits in competitive pressure in intraocular lenses, integration of recent deals like STAAR and LumiThera, and the drag from lower net profit margins versus last year. Systane PRO PF does support the case that Alcon can refresh its portfolio, yet it does not change the need for cleaner earnings quality after large one off items and for execution on integration and regulatory timelines.
The Systane PRO PF launch lines up with the broader catalyst many investors are watching: a steady drumbeat of new products across platforms such as Unity VCS, PanOptix Pro, Tryptyr and Precision7. Together, these launches could shape how convincingly Alcon turns its research spend and acquisitions into higher margin sales and better mix across Surgical and Vision Care.
This new preservative free tear also speaks directly to the dry eye theme that underpins interest in future therapies like Tryptyr. If Alcon can scale both over the next few years, the dry eye category could become a more central contributor to revenue and earnings than it is today. The flip side is execution risk; any delays in adoption, reimbursement or competitive response would matter for how quickly those expected earnings growth rates materialise.
Alcon's narrative projects $12.9b revenue and $1.7b earnings by 2029. This assumes 5.9% yearly revenue growth and an earnings increase of about $1.1b from $643.0m today.
Uncover how Alcon's fair value indicates a 36% potential upside to its current price that may not last much longer.
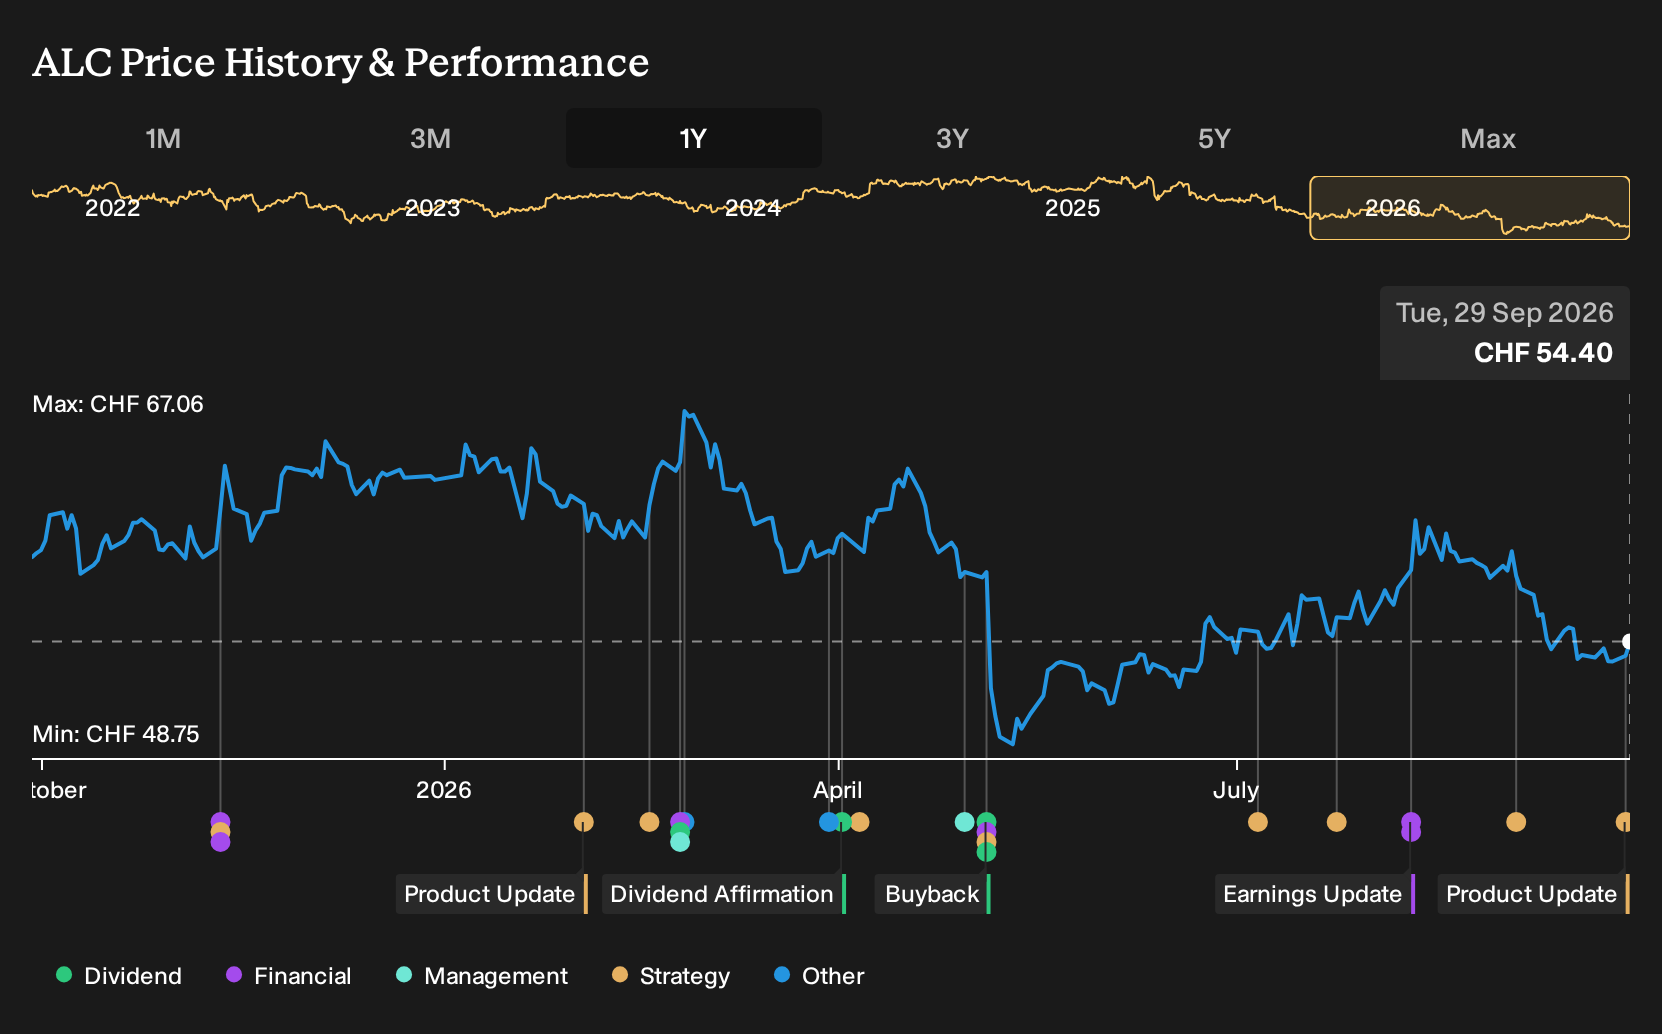
Exploring Other Perspectives
One alternate view puts pricing pressure at the center of the Alcon story. The most cautious analysts were only pencilling in revenue of about $12.5b and earnings of roughly $1.3b by 2029, well below the top-end $2.2b earnings case. That gap shows how widely opinions can differ. You can now ask whether a preservative free Systane PRO launch in Canada might push some of those expectations higher or reinforce concerns as forecasts get refreshed.
Explore 4 other Alcon fair value estimates, including one that suggests it could be worth just CHF55.04.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Alcon research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Alcon. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alcon's overall financial health at a glance.
Looking For More Alcon-Like Investment Ideas?
If the Alcon story has sharpened your appetite for quality businesses, it can help to widen the lens and scan other stocks with resilient balance sheets, cash flow support, or income potential using the Simply Wall St Screener.
- For investors who want financially robust companies at the top of their watchlist, start with a curated list of solid balance sheet and fundamentals (204 results).
- If upside potential is the priority, focus on businesses that screen well on both quality and value using the 197 high quality undervalued stocks.
- For those building a portfolio around income, zero in on companies with higher yields and resilient payout profiles through the 163 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com