


Schneider Electric (ENXTPA:SU) Unveils Software Defined Switchgear, Is It Still 9% Undervalued?
Schneider Electric (ENXTPA:SU) has put its software defined medium voltage switchgear at center stage, tying the launch directly to rising power needs from AI data centers and more software driven energy infrastructure.
Recent product launches aimed at AI data centers and critical infrastructure have arrived alongside firm share price momentum. At a latest share price of €296.35, Schneider Electric has logged a 90 day share price return of 7.12% and a year to date share price return of 25.02%. The 5 year total shareholder return of 126.80% points to strong longer term compounding, even as the 30 day share price return of 1.79% describes a brief pause rather than a clear reversal.
Scan for other electrification and AI infrastructure plays moving on similar themes by checking the curated 39 power grid technology and infrastructure stocks.
Bulls point to Schneider Electric’s software defined push and strong recent returns. Bears argue the valuation already bakes that in. The next step is to test which side current pricing supports.
Most Popular Narrative: 9% Undervalued
Against the latest close of €296.35, the most followed narrative pegs Schneider Electric’s fair value at €325.04, leaving a modest valuation gap that investors are now weighing against AI and electrification expectations.
The accelerating global shift towards electrification, renewable energy, and energy efficiency, supported by both corporate and government sustainability initiatives, continues to expand Schneider's addressable market and supports steady long-term revenue growth, particularly in energy management and grid modernization.
The company's transition toward software and recurring digital services (notably EcoStruxure, AVEVA SaaS, and EcoCare), now representing 60% of revenues and growing at double-digit rates, should drive higher margins and recurring earnings, with further upside potential as AVEVA's SaaS conversion completes by 2027.
See why 115 investors see Schneider Electric as 9% undervalued.
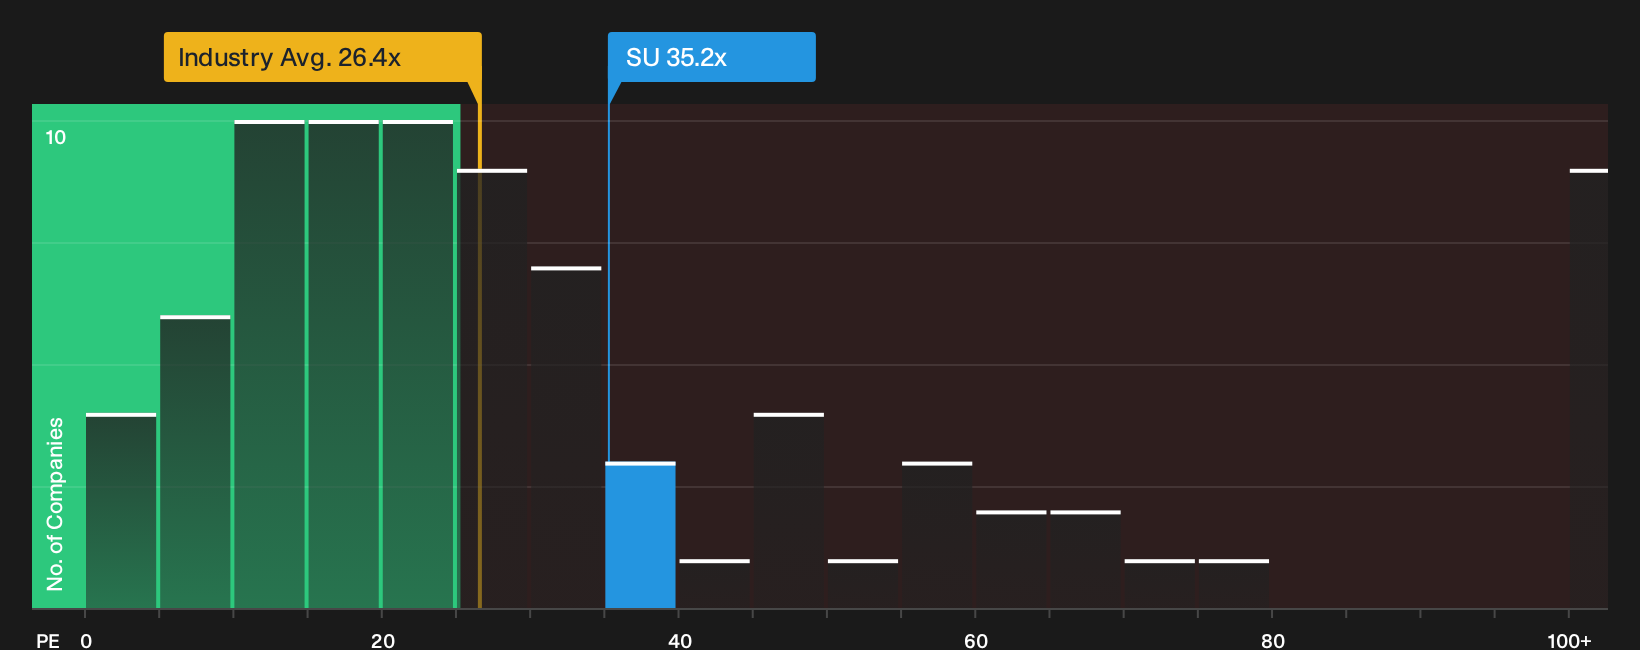
That story is underpinned by a discount rate of 9.35% and analyst assumptions for revenue growth of around 10.3% a year, with profit margins modeled to move from 11.3% to 14.7%. Those inputs help explain why this narrative still points to upside even though the current P/E of 35.2x is described as expensive versus both peers and Simply Wall St’s fair P/E estimate of 34.5x.
At the same time, the narrative highlights clear pressure points. Forecast earnings growth of roughly 16% a year sits above the French market but remains below the 20% threshold used here for very rapid expansion, and Industrial Automation is described as structurally softer, with AVEVA’s SaaS shift and regional weakness adding volatility. High debt levels and reliance on higher risk funding sources also mean the equity story leans heavily on continued execution in AI data centers, grid upgrades and software conversion.
Put together, Schneider Electric is framed as a business with high quality earnings, an experienced board and forecast return on equity of 24.3% in three years, yet carrying valuation expectations that leave little room for prolonged setbacks in margins or cash generation. The narrative fair value of €325.04, around 9% above the current share price, effectively asks investors to judge whether the AI and electrification runway, plus the software mix shift, are enough to compensate for balance sheet leverage and execution risk around those targets.
Result: Fair Value of €325.04 (UNDERVALUED)
Still, the story can crack if Industrial Automation stays weak for longer, or if heavy R&D and acquisition spending continues to squeeze free cash flow.
Find out about the key risks to this Schneider Electric narrative.
Another View: Schneider Electric On Earnings Multiples
There is a different message when you look at Schneider Electric through a simple earnings multiple. The stock trades on a P/E of 35.2x, compared with 30x for peers and 26.4x for the wider European electrical group, and above a fair ratio of 34.5x that the market could move towards.
That premium suggests investors are already paying more for execution on AI data centers, electrification and software growth. The gap over peers, and even over the fair ratio, raises a basic question for you to answer: Is the extra price worth the execution risk on margins, cash flow and leverage?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this Schneider Electric story feels finely balanced between optimism and caution, move fast to stress test the numbers yourself and form your own view. Start with the 2 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Schneider Electric?
If Schneider Electric has sharpened your focus on quality, do not stop here. Broaden your watchlist with ideas filtered for risk, value and resilience.
- Target potential mispricings by scanning a focused set of companies screened as 197 high quality undervalued stocks that might warrant a closer look on your radar.
- Prioritize resilience by reviewing a 227 resilient stocks with low risk scores that filters for businesses aiming to keep downside risk in check.
- Hunt for future leaders early by checking a 619 high quality undiscovered gems that highlight quality fundamentals before they attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com