


What Adobe Stock's AI Partnerships Mean For Shareholders
- Adobe announced multi-year AI partnerships with the NHL and Jet2, supplying CX Enterprise, GenStudio, Firefly and Express to personalize fan and traveler experiences across channels.
- The NHL deal gives Adobe access to a global base of more than 200 million hockey fans, providing a large real-world testbed for its AI marketing and content tools.
- We will now look at how Adobe's expanded AI partnerships with the NHL could influence the existing investment narrative around the business.
Adobe Investment Narrative Recap
To own Adobe, you need to believe its AI driven content and customer experience platforms can stay central to how brands create, personalize and measure digital engagement. The NHL deal speaks directly to that thesis. It reinforces the idea that large enterprises still want Adobe as a core CX partner, even as competition in AI marketing tools intensifies.
The near term swing factor remains execution on cross cloud, AI infused offerings like GenStudio and Firefly without letting complexity drag on margins. The NHL and Jet2 partnerships look additive but not transformative by themselves. Competitive pressure, rising AI investment needs and any slowdown in digital transformation budgets still sit as the key operational risks.
The Jet2 agreement is the most useful companion announcement to the NHL news. It shows Adobe pushing the same CX Enterprise and agentic AI toolkit into a very different vertical, travel, where personalization, timing and content velocity also matter. That reinforces the core catalyst for the story, which is broad adoption of its AI powered experience stack across sectors.
For you as an investor, both the NHL and Jet2 deals point to the same operational question. Can Adobe convert these flagship partnerships into scalable, high retention, cross cloud deployments without eroding profitability or losing share to faster moving rivals? Execution on that rollout will likely matter more to the outlook than any single contract headline.
Adobe's narrative projects US$32.8b revenue and US$9.6b earnings by 2029. This assumes 9.2% yearly revenue growth and an earnings increase of about US$2.4b from US$7.2b today.
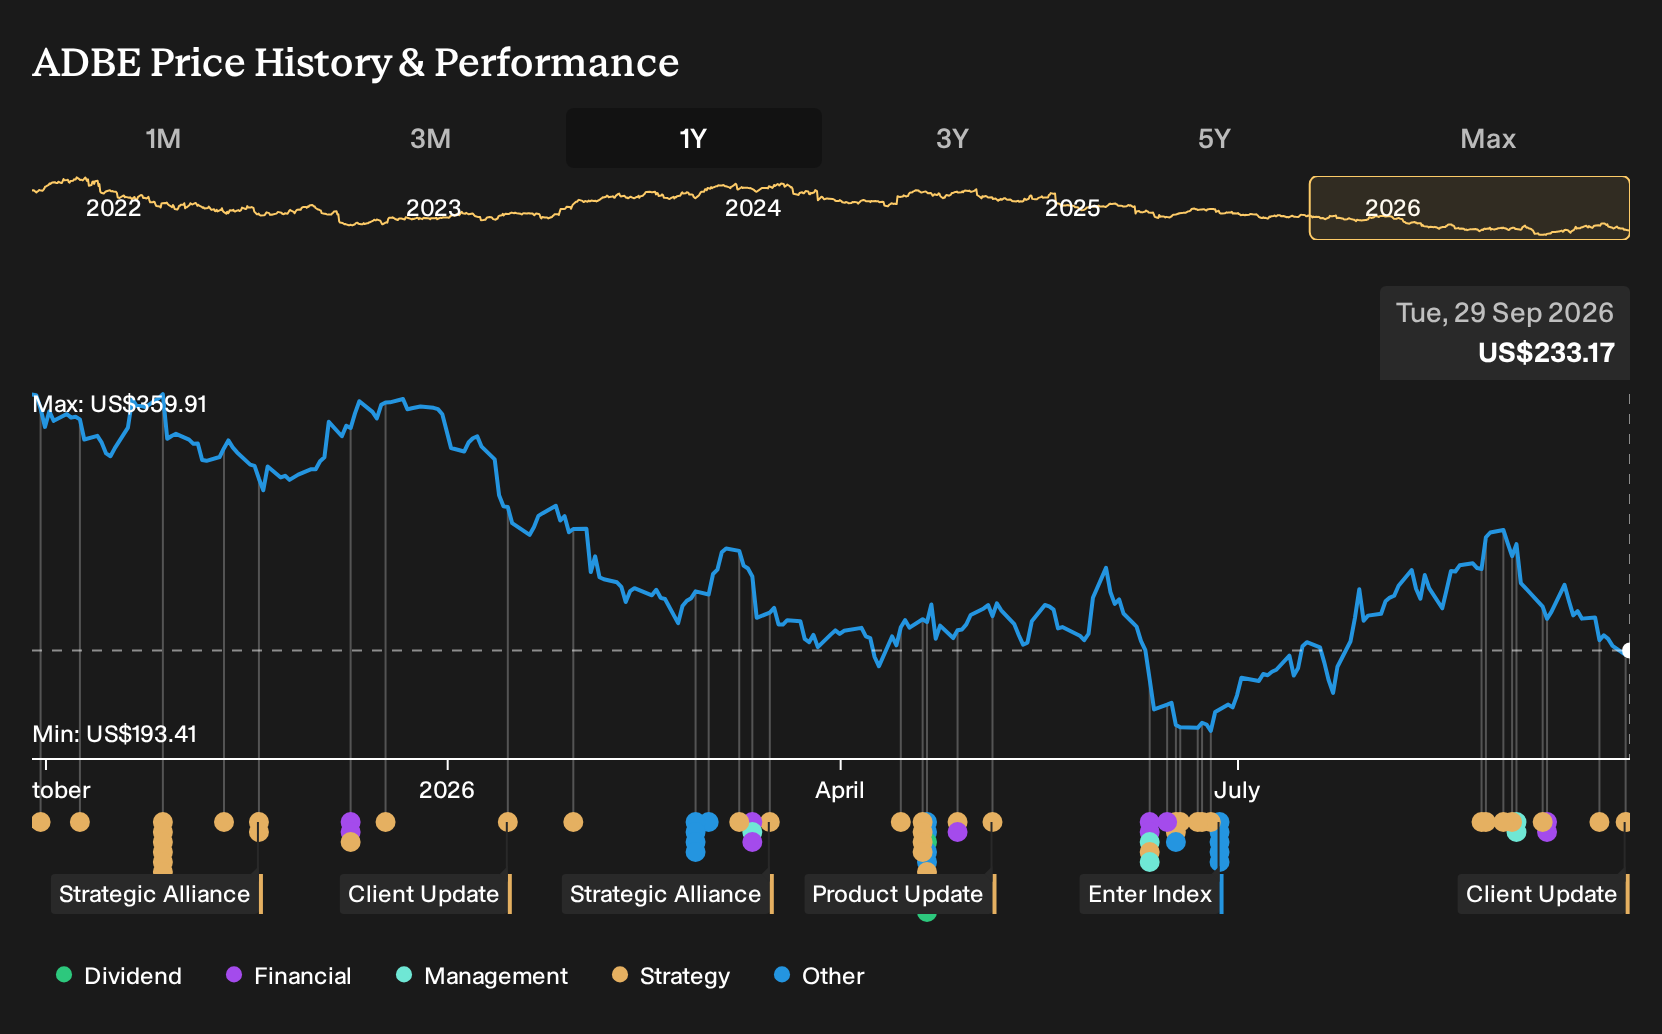
Uncover why Adobe's fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view says the real catalyst is Adobe’s AI book of business rather than any single league deal. The most optimistic analysts were already penciling in revenue of about US$34.9b and earnings near US$10.5b by 2029. Those forecasts came before the NHL news, so opinions may change as this partnership develops.
Explore 48 other Adobe fair value estimates, including one that suggests potential upside of as much as 163% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Adobe research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Adobe. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Adobe's overall financial health at a glance.
Looking For More Investment Ideas Beyond Adobe?
If the Adobe story has sharpened your thinking about AI, customer experience and long term compounding, it can be useful to widen the lens and compare it with other opportunities that share some of the same financial qualities. The Simply Wall St Screener can help you build that wider watchlist in a structured way instead of just chasing headlines.
- If you prefer to focus on stability first and potential upside second, especially in choppier markets, then filter for 32 resilient stocks with low risk scores that might better fit a capital preservation mindset.
- If balance sheet strength is your starting point and you want businesses with room to invest without stretching finances, build a shortlist from our list of solid balance sheet and fundamentals (25 results) to compare against Adobe on resilience.
- For readers hunting for underfollowed opportunities with robust fundamentals, use the 17 high quality undiscovered gems to surface candidates that could deserve a spot beside Adobe on your research list.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com