


Explore These 3 Undiscovered Gems In Asia For Potential Growth
Amidst the backdrop of fluctuating global markets, Asian equities have been capturing attention due to their potential for growth, particularly in the small-cap sector. As investors navigate these dynamic conditions, identifying promising stocks with strong fundamentals and innovative business models can be crucial for capitalizing on emerging opportunities.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Management SolutionsLtd | 7.61% | 23.78% | 29.72% | ★★★★★★ |
| Taiyo KagakuLtd | 0.68% | 6.49% | 11.88% | ★★★★★★ |
| Xinxiang Chemical Fiber | 69.88% | -0.33% | -29.16% | ★★★★★☆ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
Underneath we present a selection of stocks filtered out by our screen.
Hallenstein Glasson Holdings (NZSE:HLG)
Simply Wall St Value Rating: ★★★★★★
Overview: Hallenstein Glasson Holdings Limited, along with its subsidiaries, operates as a retailer of men's and women's clothing in New Zealand and Australia, with a market cap of NZ$835.09 million.
Operations: Hallenstein Glasson Holdings generates revenue primarily through its retail operations in New Zealand and Australia. The company's financial performance is influenced by its ability to manage costs and optimize profit margins.
Hallenstein Glasson Holdings, a nimble player in the retail sector, reported impressive earnings growth of 49.9% over the past year, significantly outpacing the Specialty Retail industry's 1.3%. With sales reaching NZ$563 million for the year ending August 2026, up from NZ$470.74 million previously, and net income rising to NZ$59.16 million from NZ$39.46 million, this company shows strong financial health without any debt on its books for five years. Trading at 73.5% below its estimated fair value and boasting high-quality earnings, it seems well-positioned with forecasted earnings growth of 7.23% annually.
- Dive into the specifics of Hallenstein Glasson Holdings here with our thorough health report.
Understand Hallenstein Glasson Holdings' track record by examining our Past report.

Plover Bay Technologies (SEHK:1523)
Simply Wall St Value Rating: ★★★★★☆
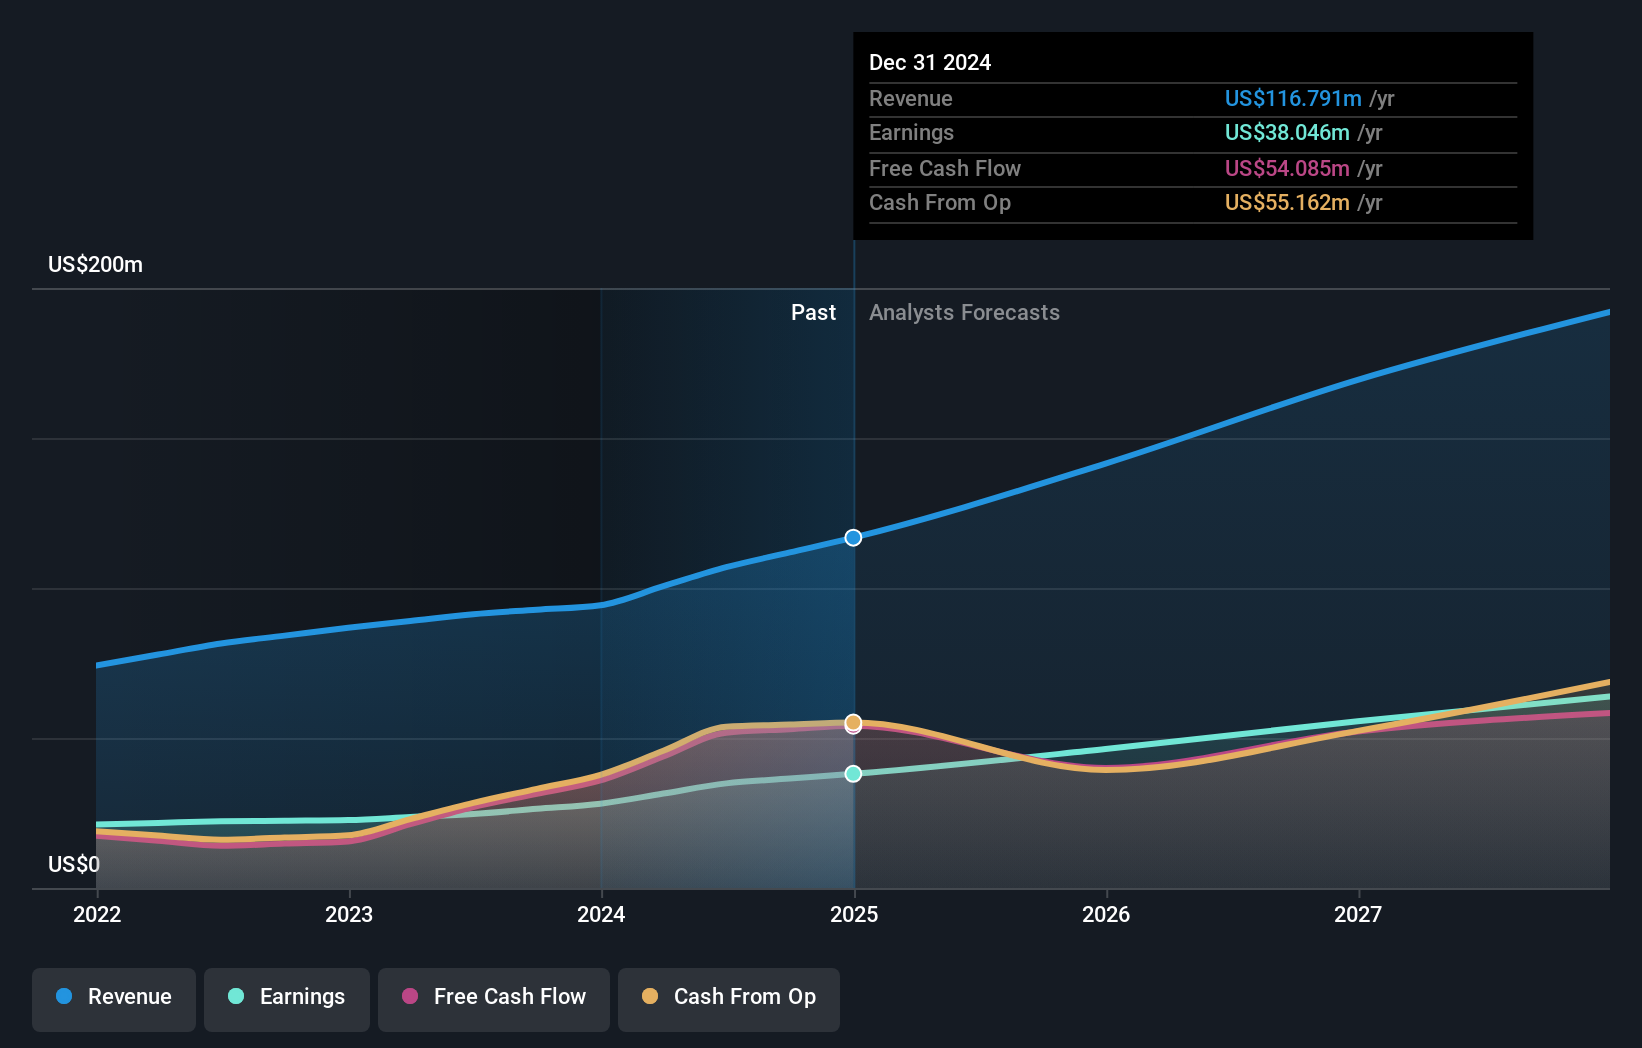
Overview: Plover Bay Technologies Limited is an investment holding company that designs, develops, and markets software-defined wide area network routers and related products, with a market capitalization of HK$8.15 billion.
Operations: The company generates revenue primarily from the sale of SD-WAN routers, with Mobile First Connectivity contributing $76.53 million and Fixed First Connectivity adding $21.10 million. Additionally, software licenses and warranty and support services account for $44.17 million in revenue.
Plover Bay Technologies, a promising player in the tech sector, has seen its earnings grow 20.7% annually over the past five years, reflecting robust performance. The company reported sales of US$74.6 million for the first half of 2026, up from US$62.94 million last year, with net income climbing to US$27.72 million from US$21.67 million a year prior. Basic earnings per share increased to US$0.0251 compared to US$0.0196 previously, indicating solid profitability despite not outpacing industry growth rates recently at 26.9%. Trading at 20% below estimated fair value suggests potential undervaluation in this small-cap gem's stock price.
- Navigate through the intricacies of Plover Bay Technologies with our comprehensive health report here.
Evaluate Plover Bay Technologies' historical performance by accessing our past performance report.
F&MLtd (TSE:4771)
Simply Wall St Value Rating: ★★★★★★
Overview: F&M Co., Ltd. offers management support and accounting services tailored for medium and small businesses, as well as individual business owners, with a market capitalization of ¥40.41 billion.
Operations: F&M's primary revenue streams are from its Consulting Business, generating ¥8.73 billion, and the Business Solution Business, contributing ¥6.97 billion. The System Development and Accounting Services businesses also add significant revenue at ¥5.08 billion and ¥5.60 billion respectively.
F&M Ltd. stands out with its impressive financial health and growth metrics. Over the past year, earnings surged by 66%, far outpacing the Commercial Services industry's 10%. The company is debt-free, a significant improvement from five years ago when it had a debt to equity ratio of 0.2%. Trading at about 21% below estimated fair value, F&M appears undervalued compared to peers. With high-quality earnings and positive free cash flow, the company's robust financial position suggests potential for continued growth. Recent dividends further bolster investor confidence in its stable prospects within the industry context.
- Get an in-depth perspective on F&MLtd's performance by reading our health report here.
Gain insights into F&MLtd's historical performance by reviewing our past performance report.

Seize The Opportunity
- Click through to start exploring the rest of the 118 Asian Undiscovered Gems With Strong Fundamentals now.
- Already own these companies? Link your portfolio to Simply Wall St and get alerts on any new warning signs to your stocks.
- Unlock the power of informed investing with Simply Wall St, your free guide to navigating stock markets worldwide.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com