


Contract Wins Could Shape The Next Chapter For Perenti Shares
- Perenti recently secured more than $200 million in drilling and underground mining contracts across Australia, the US, Canada, and Senegal, with about $185 million expected to be recognised in the 2027 financial year from drilling services alone.
- The fresh contract book highlights how Perenti’s diversified drilling businesses and AUMS underground arm are being used by miners to outsource complex work across several continents.
- We now examine how Perenti's investment narrative is influenced by these large multi region contract wins and the additional revenue visibility they provide.
Scan how miners outsourcing complex drilling work compare to peers by reviewing our curated list of list of solid balance sheet and fundamentals (11 results).
Perenti Investment Narrative Recap
To own Perenti, you need to believe outsourced mining services will stay integral to how resource companies run complex projects and that this contractor can convert its pipeline into durable earnings without letting margins slide. The fresh A$200 million plus in contracts supports near term workload, although it does not change the underlying exposure to client pricing pressure and utilisation swings.
Right now, the key near term swing factor is whether Perenti can lift margins from a base where net profit sits at A$81.9 million on A$3.34b of revenue while managing one off items and cost inflation. The biggest risk remains operational and political concentration in a handful of regions, especially Africa and Australia, if project conditions tighten or contracts roll off unfavourably.
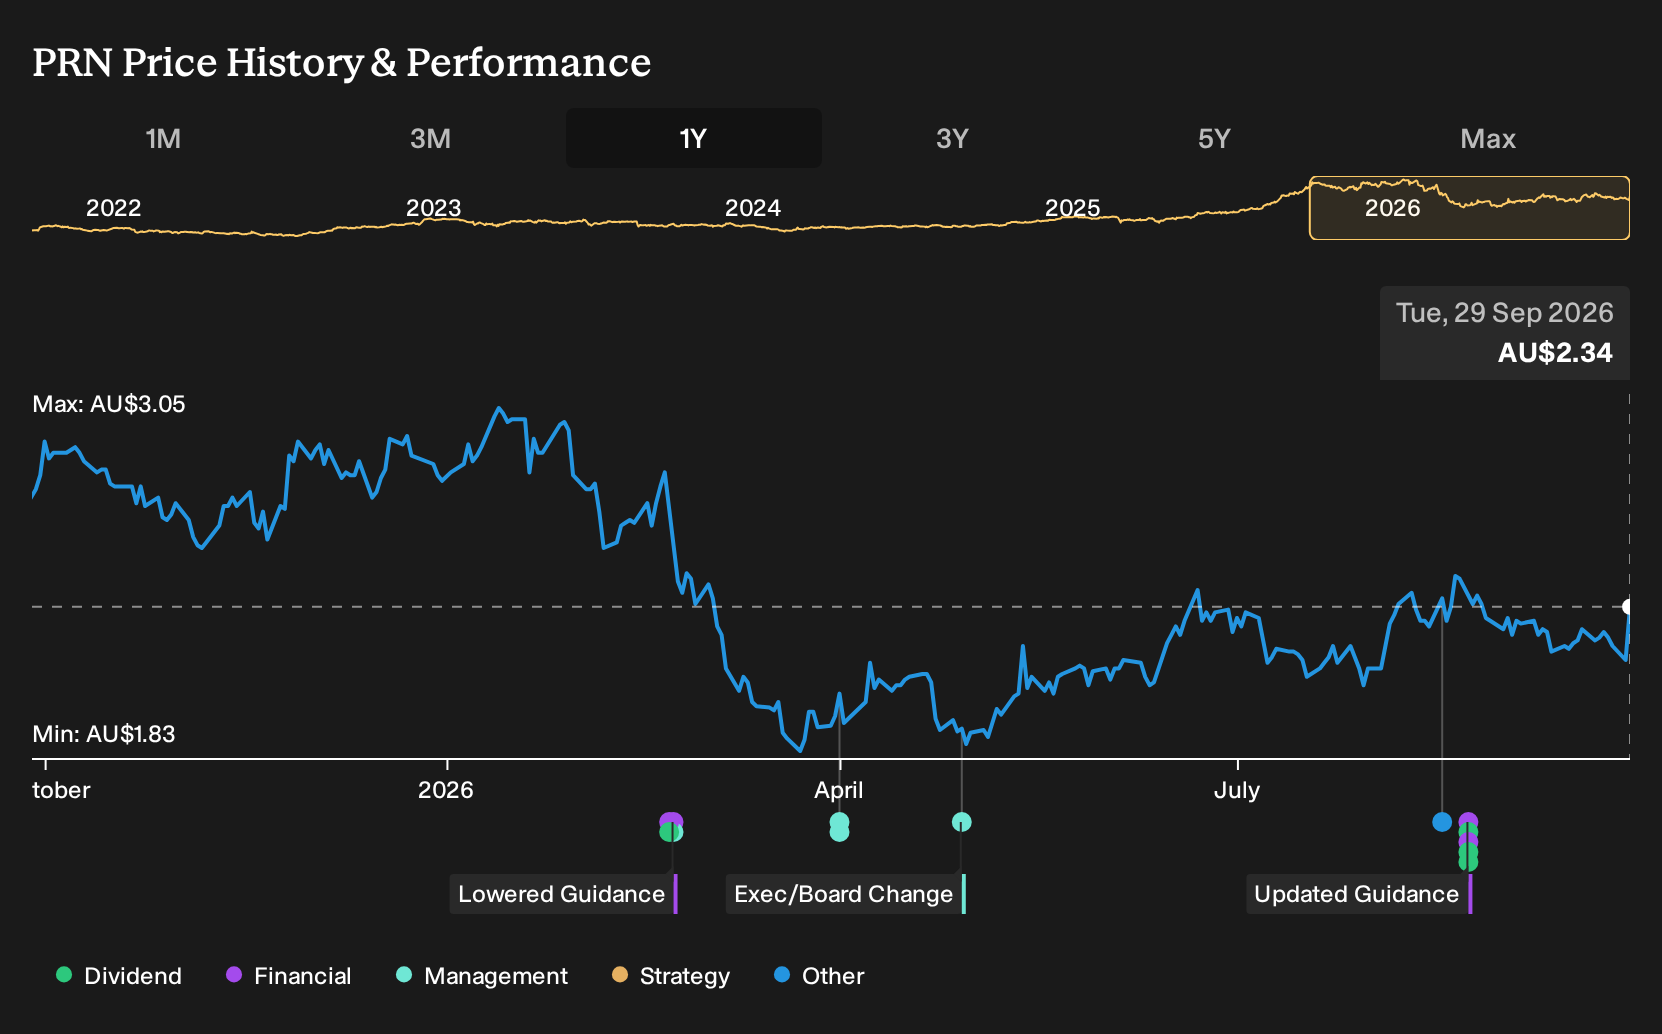
The recent cluster of drilling and underground awards is the clearest current proof point for one of the main catalysts flagged by analysts, which is growth in outsourced work as miners seek specialist contractors across multiple continents. Around A$185 million of that book is expected to be recognised in the 2027 financial year, which adds timing clarity around a slice of future activity.
That said, no accompanying announcement points to a structural change in Perenti’s economics yet. Execution quality on these jobs, utilisation of the drilling fleet, and delivery in higher risk jurisdictions like parts of Africa still sit front and centre for the story. If margins remain under pressure or further large one off losses appear, contract wins alone may not offset the concerns many investors have around pricing power and return on equity.
Perenti's current analyst narrative points to A$3.9b of revenue and A$233.9 million of earnings by 2029, built on 4.0% yearly revenue growth and an earnings increase of about A$111 million from A$122.7 million today.
Uncover why Perenti's fair value indicates a 15% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame Perenti’s contract pipeline itself as the key upside. Before this news, the bullish group already projected revenue reaching about A$4.0b and earnings of roughly A$273.2 million by 2029. You can now weigh these higher expectations against the fresh contract awards and decide whether that story still fits.
Explore 3 other Perenti fair value estimates, including one that suggests up to 15% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Perenti research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Perenti. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Perenti's overall financial health at a glance.
Looking For More Ideas Beyond Perenti?
If Perenti has sharpened your thinking about contractors and risk, use that momentum to scan for other stocks that match the kind of balance sheets, income streams, or resilience you want in your portfolio. The Simply Wall St Screener can help you filter for very different styles of opportunities without losing sight of fundamentals.
- If you want value with quality in mind, start by reviewing a focused group of 5 high quality undervalued stocks that combine solid fundamentals with room for the market to reassess their pricing.
- If consistency and financial resilience appeal more than excitement, narrow in on a 7 resilient stocks with low risk scores that aims to limit unpleasant surprises when conditions get tougher.
- If you are hunting for under-the-radar ideas, scan through a curated pool of 15 high quality undiscovered gems where strong financial profiles have not yet drawn widespread attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com