


L'Oréal (ENXTPA:OR) Could Be 9% Below Fair Value As Armani Stake Sale Draws Focus
Armani’s reported plan to sell a 15% stake at a €10b valuation has pulled L'Oréal (ENXTPA:OR) into the spotlight as investors weigh what deeper ties to the Italian group could mean.
Recent price action has been muted, with the share price down over the past week and month. However, the year to date share price return of 4.4% and 1 year total shareholder return of 5.35% point to steady but not explosive momentum as investors digest Armani headlines, fresh bond issuance and high profile Paris Fashion Week exposure.
Scan how investors are pricing beauty leaders like L'Oréal against peers and spot potential breakouts in our curated list of 202 high quality undervalued stocks.
L'Oréal now trades around €380.75 while analyst targets and intrinsic value estimates cluster higher, leaving a clear gap. Does the recent pullback narrow fair value, or has the valuation case simply become more interesting?
Most Popular Narrative: 9% Undervalued
L'Oréal’s most followed narrative places fair value at €417.08, above the recent €380.75 close, which frames the current pullback as a valuation gap that still ties back to fundamentals and cash flows rather than sentiment alone.
Acceleration of double-digit sales and volume growth in emerging markets, such as Mexico, Brazil, India, and Thailand, is expanding L'Oréal's addressable market and directly supporting long-term sustainable revenue and earnings growth. Ongoing rapid shift to online channels (e-commerce accounted for nearly 29% of first-half sales and is growing at double the pace of the market) enhances direct-to-consumer margins and customer acquisition efficiency, bolstering both profitability and top-line expansion.
See why 85 investors see L'Oréal as 9% undervalued.
The narrative applies a 6.71% discount rate and arrives at a fair value about 9% above the current share price, while also assuming revenue growth of roughly 6.3% a year and profit margins above 16%. That combination points to a view that L'Oréal’s current P/E and premium to peers are supported by expected earnings power rather than multiple expansion alone.
Result: Fair Value of €417.08 (UNDERVALUED)
Still, if L'Oréal loses ground to local and digital rivals in China or spends more on marketing than sales can justify, that 9% valuation gap could evaporate.
Find out about the key risks to this L'Oréal narrative.
Another View On L'Oréal’s Valuation
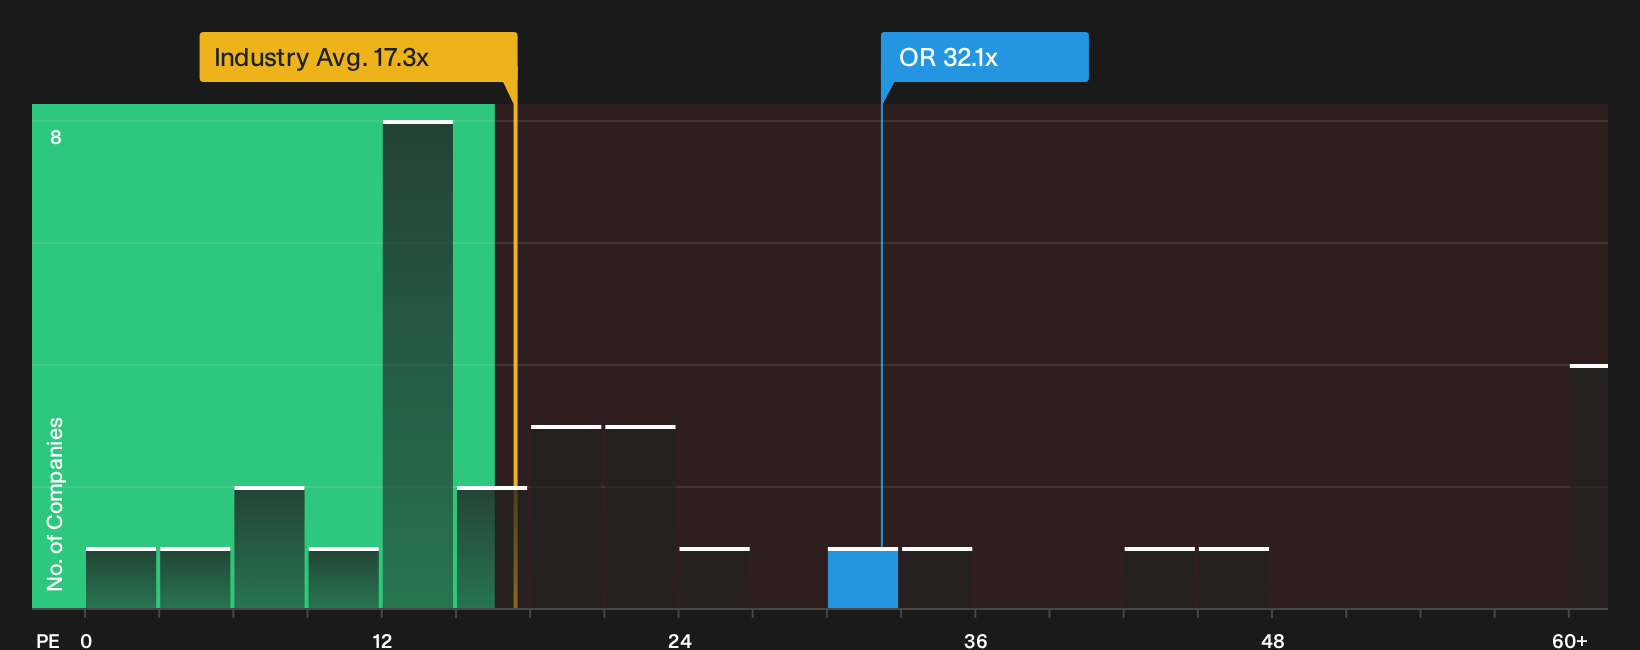
The earlier narrative leans on discounted cash flows and a fair value around €417. Yet on simple earnings multiples, L'Oréal looks expensive. The stock trades on a P/E of 32.1x, compared with 17.3x for the European personal products group and 26.3x for peers.
The fair ratio for L'Oréal is 33.2x, only slightly above the current 32.1x. This suggests limited room if the market drifts toward that level rather than well beyond it. If growth or margins come in softer than expected, how much multiple risk are you really comfortable carrying here?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the cautious optimism around L'Oréal really holds up for you personally? Take a close look at the underlying drivers and weigh them against 3 key rewards.
Looking for more ideas beyond L'Oréal?
If L'Oréal is on your radar, do not stop there. Use the Simply Wall Street Screener to uncover other opportunities that could fit your style and risk comfort.
- Zero in on value opportunities by scanning for 202 high quality undervalued stocks that pair quality fundamentals with potentially appealing entry points.
- Strengthen your income game by reviewing 164 dividend fortresses that focus on higher yields supported by solid underlying businesses.
- Dial back portfolio stress by assessing 225 resilient stocks with low risk scores that show more resilient financial profiles and lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com