


How Investors May Respond To Nektar Therapeutics (NKTR) New Phase 2b Data Presentations
- Nektar Therapeutics recently reported that Phase 2b data for its Treg‑targeting biologic rezpegaldesleukin in atopic dermatitis and alopecia areata were presented across three oral sessions at the 2026 EADV Congress in Vienna. These presentations included 6‑month off‑treatment durability findings in severe alopecia areata.
- The focus on long term response durability, multi omic biomarker work from Mount Sinai, and flexible dosing regimens highlights how central rezpegaldesleukin has become to Nektar Therapeutics' clinical and operational priorities.
- We will now look at how these new rezpegaldesleukin durability and biomarker data could influence Nektar Therapeutics' broader investment narrative.
Nektar Therapeutics Investment Narrative Recap
To own Nektar Therapeutics, you have to believe rezpegaldesleukin can convert deep Phase 2b data into a focused late stage plan in atopic dermatitis and alopecia areata before the balance sheet tightens. The short term story still revolves around clarity on trial design, timing to Phase 3, and whether a partner or new funding supports that step.
The main risk has not changed. Nektar remains pre commercial, loss making, and heavily concentrated in a single asset, with past shareholder dilution and ongoing R&D spend pressuring future ownership. The new EADV data look directionally helpful for the rezpegaldesleukin case, but do not remove financing or execution risk.
The most relevant element here is the prior FDA Fast Track designations for rezpegaldesleukin in atopic dermatitis and severe alopecia areata. Those designations already set the stage for a potentially more efficient regulatory path. The new EADV readouts now sit on top of that framework and give investors more detail on durability and dose flexibility.
In practical terms, the combination of Fast Track status and extended Phase 2b data makes the next set of decisions more operational than theoretical. Investors are watching for how Nektar structures Phase 3, whether it can secure a partner to share costs, and how quickly the firm moves without over stretching a business that is still unprofitable.
Nektar Therapeutics' current analyst narrative points to forecast 2029 revenue of $40.0 million and earnings of $8.8 million, based on a view that top line performance will decline 9.9% each year for the next 3 years. Earnings are expected to move from a loss of $157.1 million today to a profit of $8.8 million, a swing of about $166 million over that period.
Uncover how Nektar Therapeutics' fair value indicates a 139% potential upside to its current price before the market closes that gap.
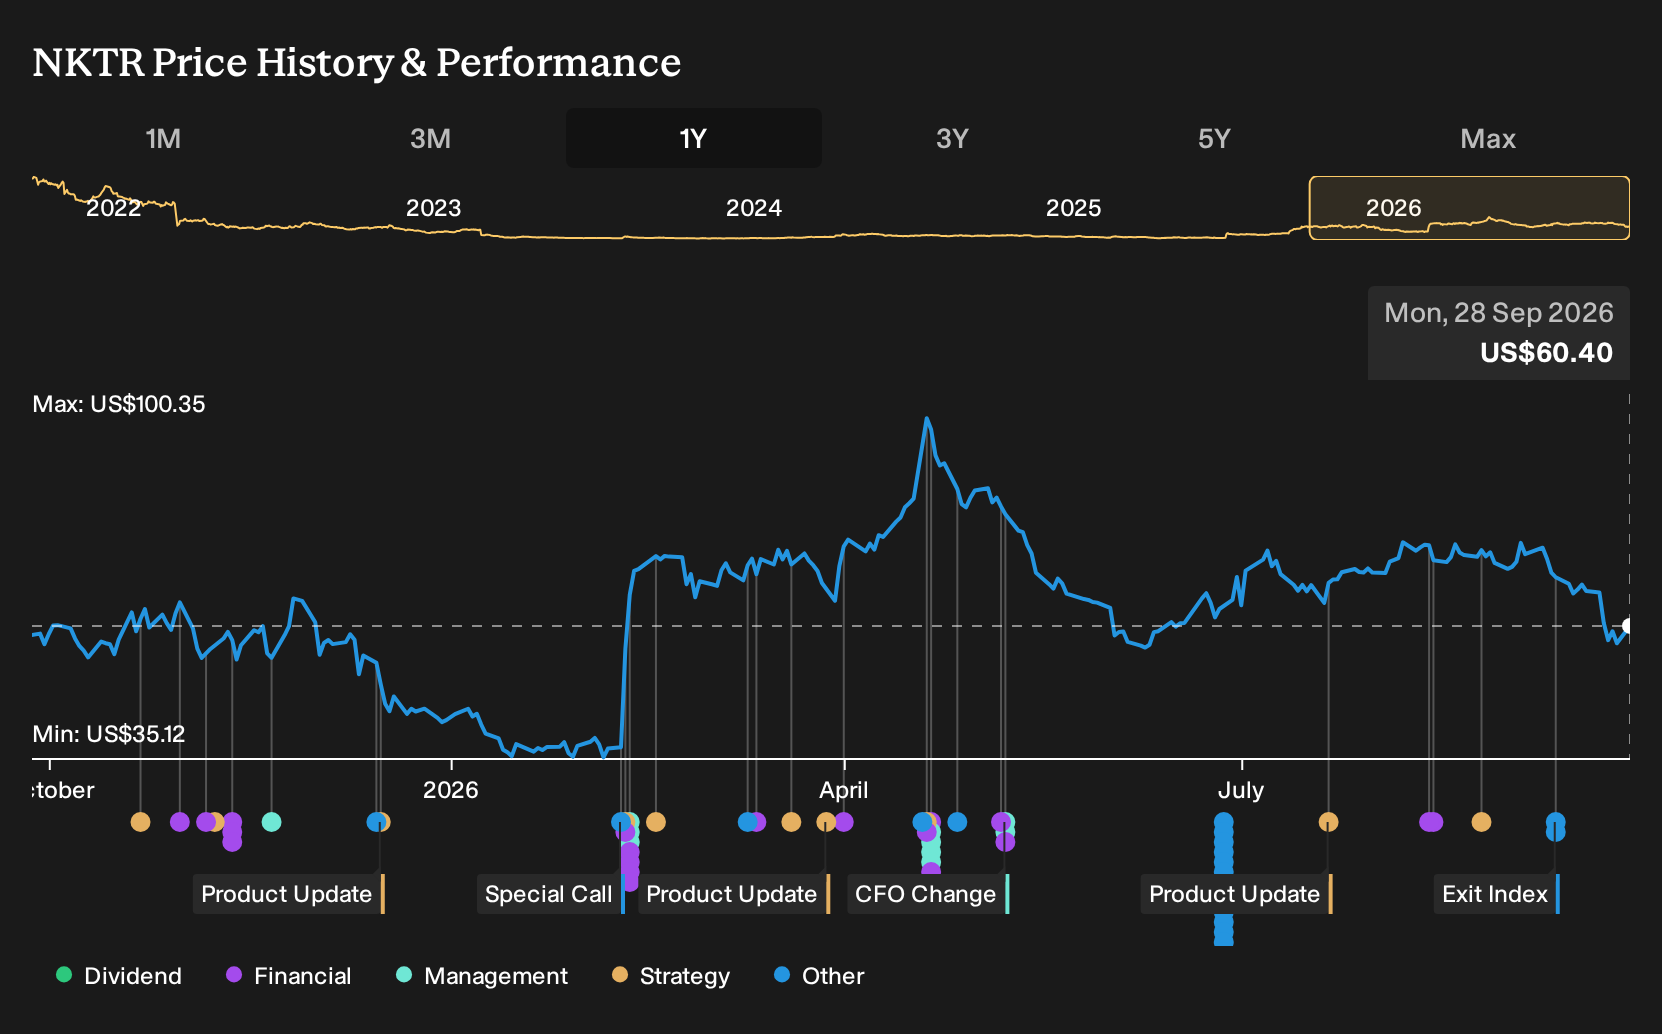
Exploring Other Perspectives
One alternate view leans hard into the catalyst of rezpegaldesleukin potential. The most optimistic analysts were already assuming revenue could reach about $136.0 million and earnings about $26.8 million by 2029, before this EADV data. You should expect those more upbeat narratives to evolve as you weigh your own view on Nektar Therapeutics.
Explore 2 other Nektar Therapeutics fair value estimates, including one that suggests as much as 218% potential increase from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Nektar Therapeutics research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Nektar Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nektar Therapeutics' overall financial health at a glance.
Looking for more investment ideas beyond Nektar Therapeutics?
If the rezpegaldesleukin story has sharpened your interest in where capital could work hardest next, it can help to compare Nektar Therapeutics with a wider set of opportunities that fit different risk and quality profiles.
- For investors who want potential upside without ignoring balance sheet strength, start with a curated list of solid balance sheet and fundamentals (25 results) that can handle pressure when conditions get tougher.
- If capital preservation comes first and you prefer steadier profiles, focus on a group of 30 resilient stocks with low risk scores that screen well on resilience and financial sturdiness.
- When you are hunting for underfollowed opportunities with room for the story to develop, consider a hand picked pool of 16 high quality undiscovered gems that pair quality fundamentals with less crowded ownership.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com