


InnoCare Pharma (SEHK:9969) Recasts Its Valuation Story After Eli Lilly Deal
New Lilly alliance resets the conversation around InnoCare Pharma
InnoCare Pharma (SEHK:9969) has signed a research collaboration and license deal with Eli Lilly that links its drug discovery platform to up to five targets and includes sizable potential milestone payments.
Investors have already reacted to the Lilly tie-up, with InnoCare Pharma’s share price up 2.62% over the last day and showing a 22.01% 90-day share price return. The 1-year total shareholder return is down 22.70% after a strong 3-year total shareholder return of 161.66%.
Scan beyond InnoCare Pharma and see how other biopharma players with meaningful pipelines and partnerships line up in our curated list of 618 high quality undiscovered gems.
The Lilly agreement has pulled InnoCare Pharma back into focus after a tough 1-year stretch. The real debate now is whether most of the upside is already in the price or still ahead.
Most Popular Narrative: 26% Undervalued
InnoCare Pharma’s most followed valuation story points to a fair value of HK$19.62, compared with the last close at HK$14.47, which puts the Lilly collaboration into a much bigger earnings and pipeline context.
The company has a strong pipeline with numerous drugs in late-stage development, including tafasitamab, zurletrectinib, and others, expecting approvals and launches in the next few years, which could significantly bolster future revenues.
The introduction of InnoCare's ADC platform aims to tap into new therapeutic areas with highly differentiated products, potentially opening new revenue streams and improving net margins through therapies with a better safety profile.
See why 1 investors see InnoCare Pharma as 26% undervalued.
Result: Fair Value of HK$19.62 (UNDERVALUED)
Still, the InnoCare Pharma story depends heavily on a few key drugs, and rising R&D spending could pressure profitability if new launches disappoint.
Find out about the key risks to this InnoCare Pharma narrative.
Another View: What The P/E Ratio Says About InnoCare Pharma
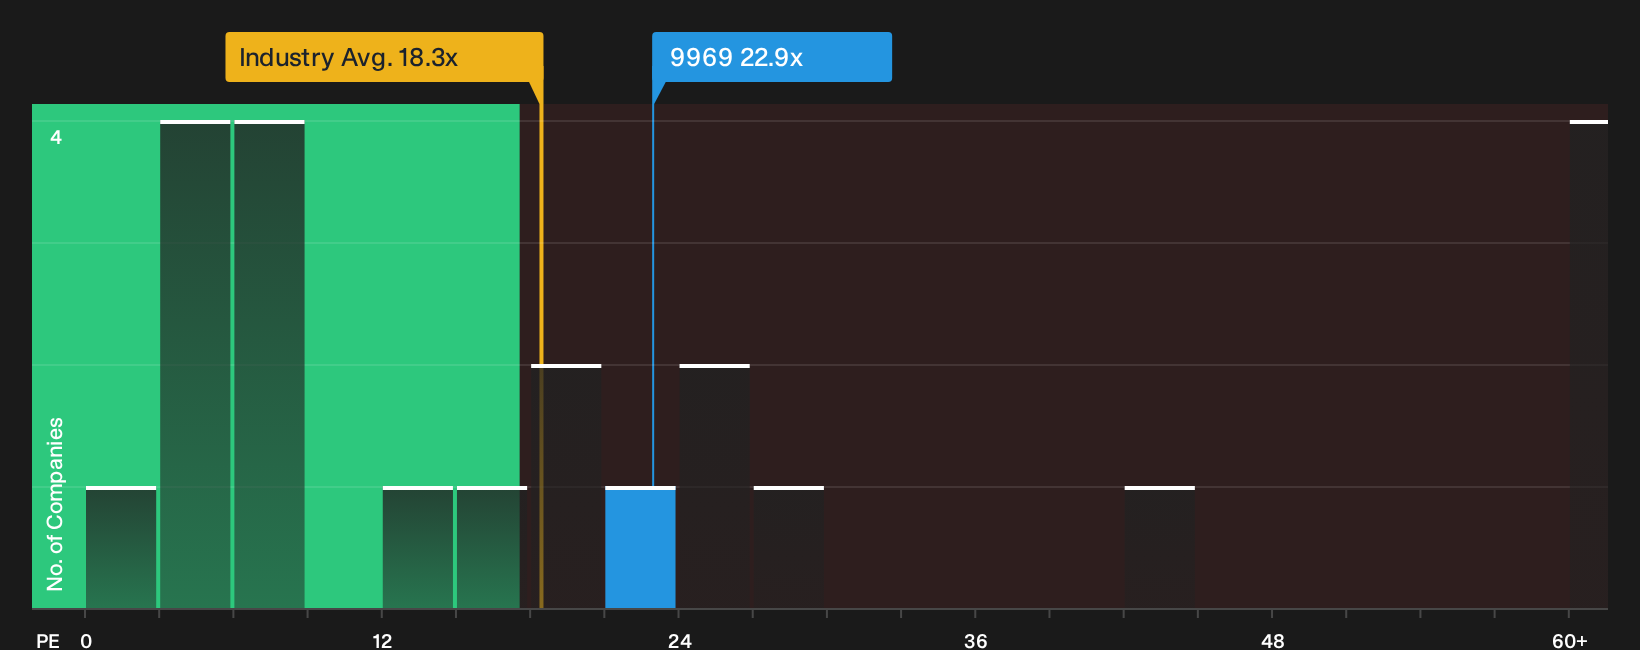
Analysts see upside to HK$19.62, yet InnoCare Pharma trades on a P/E of 22.9x while its own fair ratio is 10x, the Hong Kong Biotechs industry sits at 18.3x, and peers average 55.4x. That mix of expensive versus fair ratio, but cheaper than peers, raises a simple question: How much valuation risk are you really taking on at HK$14.47?
To see how that gap between current P/E, fair ratio and sector levels might close over time, and what the numbers imply for upside or downside, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the mixed sentiment around InnoCare Pharma leaves you undecided, consider reviewing the numbers for yourself and weighing both sides. To see the core issues and potential upsides in one place, start with 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond InnoCare Pharma?
Do not stop with InnoCare Pharma. Put fresh ideas on your radar using focused screeners that surface opportunities you might otherwise overlook.
- Target dependable income by scanning for companies that resemble defensive income plays with 164 dividend fortresses.
- Prioritize resilience by reviewing a list of solid balance sheet and fundamentals (204 results) that can help you sidestep weaker balance sheets.
- Pursue mispriced potential by checking a 202 high quality undervalued stocks that match your risk and return preferences.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com