


How International Pump Launch Has Changed Its Investment Story At Tandem Diabetes Care (TNDM)
- Tandem Diabetes Care has rolled out its Tandem Mobi automated insulin delivery system to 12 countries across Europe and Israel, offering Control-IQ+ algorithm support, Dexcom G7 integration, flexible wear options, and a 200 unit cartridge.
- This wider Tandem Mobi availability gives Tandem Diabetes Care more exposure to high recurring hardware and supplies revenue outside the US, while testing demand for app controlled, small form factor pumps in multiple reimbursement systems.
- We will examine how Tandem Diabetes Care's investment narrative may be influenced by Tandem Mobi's international rollout and the expanded reach of its automated insulin delivery offering.
Tandem Diabetes Care Investment Narrative Recap
To own Tandem Diabetes Care, you need to believe that its pump ecosystem can grow into a larger installed base and higher recurring supply revenue despite rising competition and current losses. The international rollout of Tandem Mobi supports that thesis by widening the funnel for new users, although the immediate financial impact is uncertain and may not change the near term picture on its own.
Right now the key near term catalyst is execution on international and pharmacy channel expansion while working toward profitability from a reported loss of US$63.3 million on US$1.04b of revenue. The biggest risk is that competitive pressure and flat 2026 renewals could limit new pump starts, which in turn could leave revenue growth and margin improvement below expectations.
The Tandem Mobi launch into 12 additional countries directly connects with the earlier catalyst of international expansion and direct sales rollouts. More geographies using Tandem Mobi and Dexcom G7 integration can support higher margin recurring supplies over time, with international revenue already at US$315.2 million versus US$726.2 million in the US.
This same move also highlights the operational risks described in the earlier narrative. Adding app controlled pumps across multiple reimbursement systems raises complexity, from inventory timing to pricing and support. For shareholders, the focus is on how well Tandem Diabetes Care manages that execution load while still working toward the forecast shift from losses to profitability.
Tandem Diabetes Care's current analyst narrative points to revenues of US$1.4b and earnings of US$63.4 million by 2029, based on a 10.3% yearly revenue growth assumption and an earnings change of about US$158 million, from a reported loss of US$94.5 million today to the forecast profit level.
Uncover why Tandem Diabetes Care's fair value indicates a 78% potential upside to its current price, which could narrow quickly.
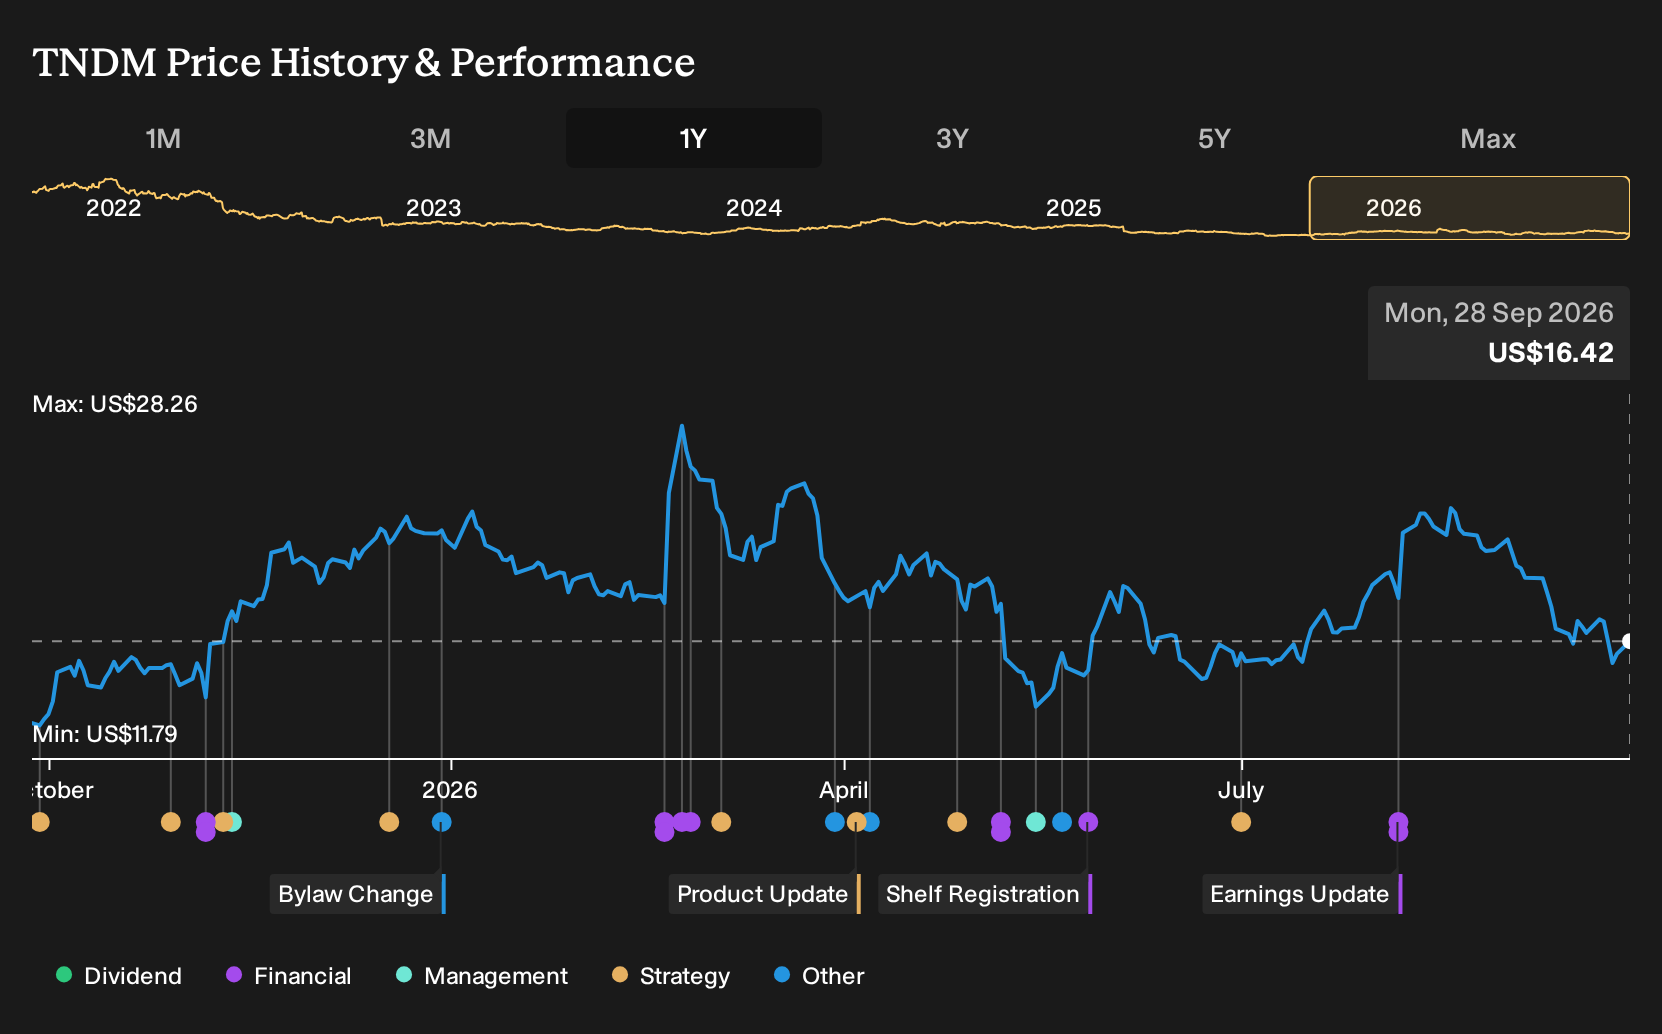
Exploring Other Perspectives
One alternate view leans hard on pricing pressure as the real swing factor for Tandem Diabetes Care. Some of the lowest analysts were using slightly softer revenue assumptions of about 9.3% a year and penciling in earnings as low as a US$5.3 million loss by 2029. Those estimates all predate this Tandem Mobi rollout, so you can decide whether fresh international traction could shift that story.
Explore 2 other Tandem Diabetes Care fair value estimates, including one that suggests it could be worth just $29.20!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Tandem Diabetes Care research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Tandem Diabetes Care. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tandem Diabetes Care's overall financial health at a glance.
Looking For More Investment Ideas Beyond Tandem Diabetes Care?
If Tandem Diabetes Care has sharpened your thinking on healthcare and recurring revenue models, it can be useful to line it up against other opportunities that share similar quality markers or offer very different risk profiles. The Simply Wall St Screener helps you quickly filter for companies that fit the kind of balance sheet strength, income potential, or upside profile you want in your portfolio.
- For investors who want potential upside with a tight focus on valuations and fundamentals, scan a curated set of 16 high quality undiscovered gems that the wider market may not be paying attention to yet.
- If capital preservation and a smoother ride matter more than headline growth stories, filter for 30 resilient stocks with low risk scores that score well on resilience and risk metrics.
- When you care most about financial strength before anything else, start with a list of solid balance sheet and fundamentals (25 results) to see which businesses pair sturdy finances with underlying fundamental support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com