


How Investors Are Reacting To Group 1 Automotive (GPI) Debt Funded Acquisition
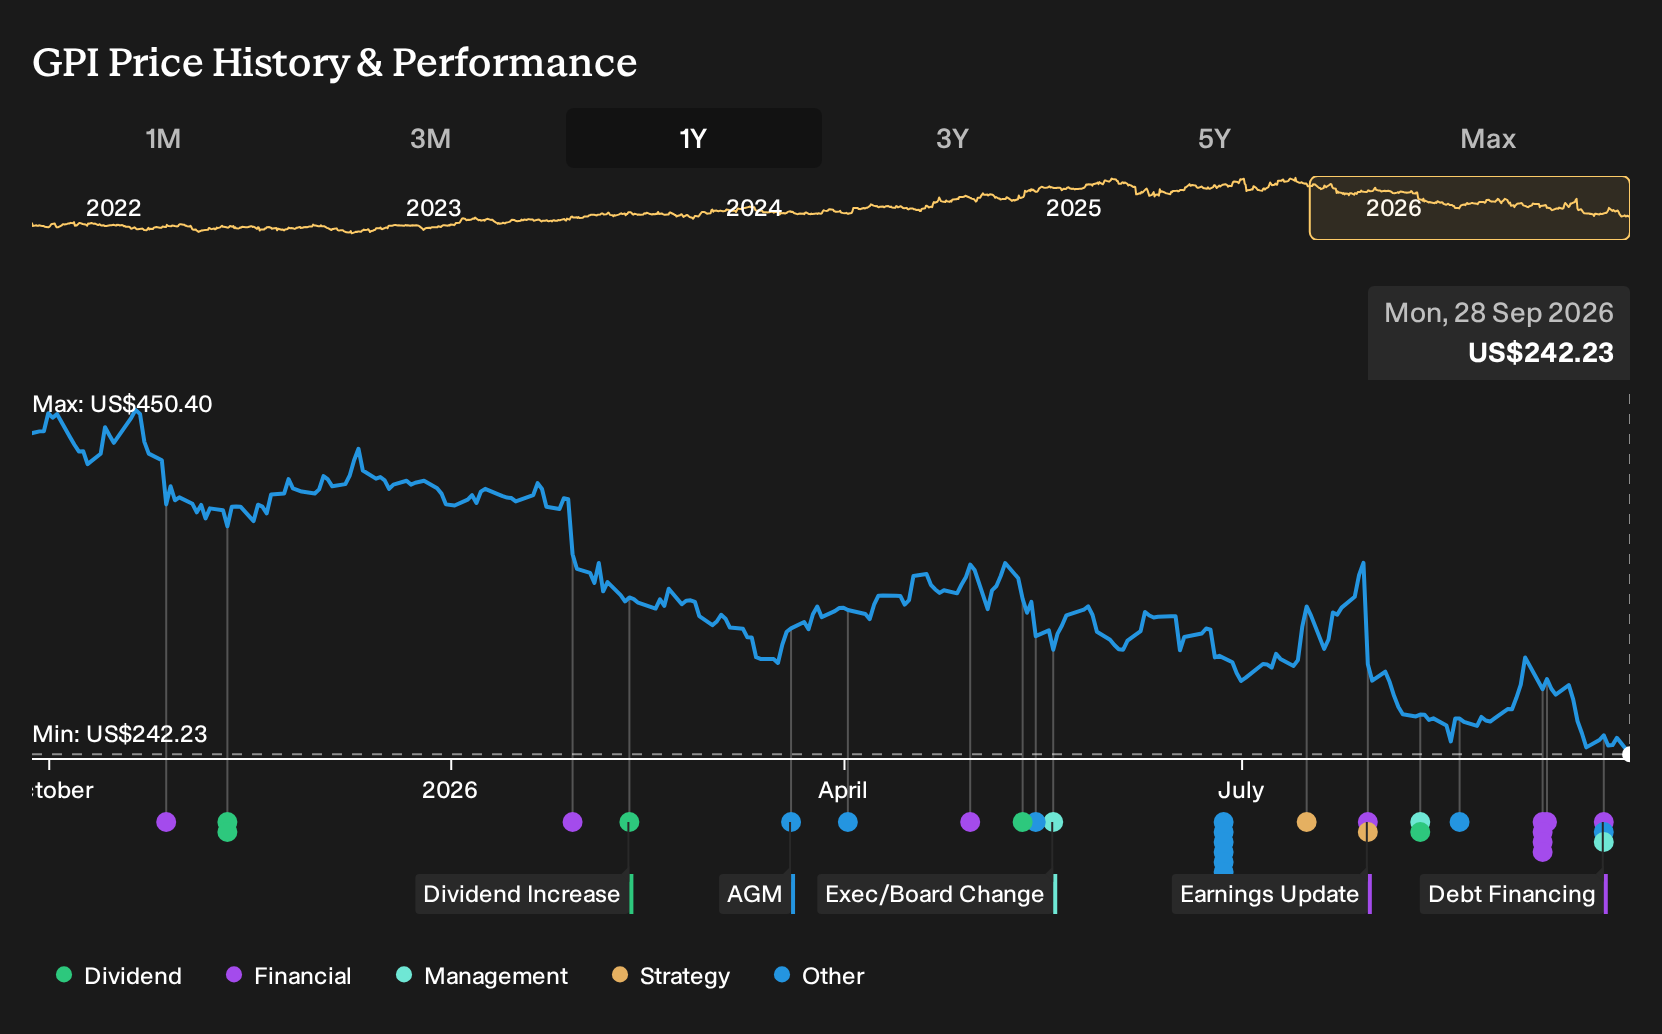
- Group 1 Automotive closed a private placement of $1.25 billion in senior unsecured notes to help fund the Hennessy dealership acquisition and related real estate, with provisions for special mandatory redemption if the deal does not close.
- Conifer Management secured a board seat for investment professional Benjamin Hart through a stockholder agreement, signaling more active shareholder influence over Group 1 Automotive's capital allocation and acquisition approach.
- This article examines how Group 1 Automotive's investment narrative is affected by this large debt issuance to fund the Hennessy acquisition.
Group 1 Automotive Investment Narrative Recap
To own Group 1 Automotive, you need to be comfortable with a dealer group that leans on acquisitions, scale and a growing aftersales engine, while living with thinner recent margins and softer share price performance. The Hennessy deal funded by US$1.25b of new notes keeps that roll up story intact but raises the stakes on balance sheet execution.
In the near term, the main upside swing factor is how effectively Group 1 turns newly acquired rooftops into steady service, parts and used vehicle throughput. The biggest risk is that higher leverage, uneven cash coverage of debt and integration challenges combine with digital competition to keep returns and valuation under pressure.
The most important development tied to that risk and opportunity mix is the new US$1.25b senior unsecured notes package. These 2032 and 2035 notes fund the Hennessy acquisition and temporarily pay down the acquisition line, so your focus has to be on how much incremental cash generation these stores eventually contribute versus the added interest burden.
The special mandatory redemption feature caps one tail risk if Hennessy does not close, since the 2032 notes would return principal at 100% plus accrued interest. Execution risk then shifts back to Group 1 Automotive's existing footprint, where debt coverage, margin pressure and competition from online focused retailers already sit at the front of the catalyst and risk conversation.
What The Hennessy Deal Asks Group 1 To Deliver
Group 1 Automotive's narrative projects US$26.1b revenue and US$657.1m earnings by 2029. That framework assumes 5.6% yearly revenue growth and an earnings increase of about US$372m from US$285.2m today.
Uncover why Group 1 Automotive's fair value indicates a 53% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most pessimistic analysts focus on digital disruption risk for Group 1 Automotive. They assume revenue reaches only US$24.0b by 2029 with 2.7% annual growth and a low 5.5x P/E. Those estimates were set before this Hennessy financing and board change, so opinions may evolve. Explore both narratives.
Explore 2 other Group 1 Automotive fair value estimates, including one that suggests it could be worth just $264.00.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider doing your own independent research.
- A great starting point for your Group 1 Automotive research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Group 1 Automotive. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Group 1 Automotive's overall financial health at a glance.
Looking For More Investment Ideas Beyond Group 1 Automotive?
If this Hennessy financing move has you rethinking how you allocate capital, it can help to line Group 1 Automotive up against other opportunities with different risk and balance sheet profiles using the Simply Wall St Screener.
- Focus on resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (25 results) to compare against Group 1 Automotive's leverage story.
- If capital preservation matters most, filter for companies with lower overall risk profiles by reviewing a targeted set of 30 resilient stocks with low risk scores that may offer a smoother ride through tough periods.
- For investors hunting for mispriced opportunities, check out a focused group of 16 high quality undiscovered gems that pair quieter headlines with fundamental strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com