


Tokio Marine Holdings And 2 Japanese Dividend Stocks To Watch
Australian interest rates are sitting at a 15-year high after the Reserve Bank pushed the cash rate to 4.6%, which keeps cash in the bank attractive and puts more pressure on shares with low or unreliable payouts. Some investors may find high quality Japanese dividend stocks yielding above 3% with solid coverage and stable profiles appealing by comparison. This article highlights three such dividend-focused opportunities from the current screener.
The three stocks in this article are just a starting sample from the Dividend Powerhouses idea. The full screen surfaces 562 more companies with similar yield, coverage and stability profiles that are not covered here. To go deeper, head straight into the Dividend Powerhouses (3%+ Yield) screener to identify, filter and analyze the highest conviction dividend opportunities that fit your own risk and income goals.
Tokio Marine Holdings (TSE:8766)
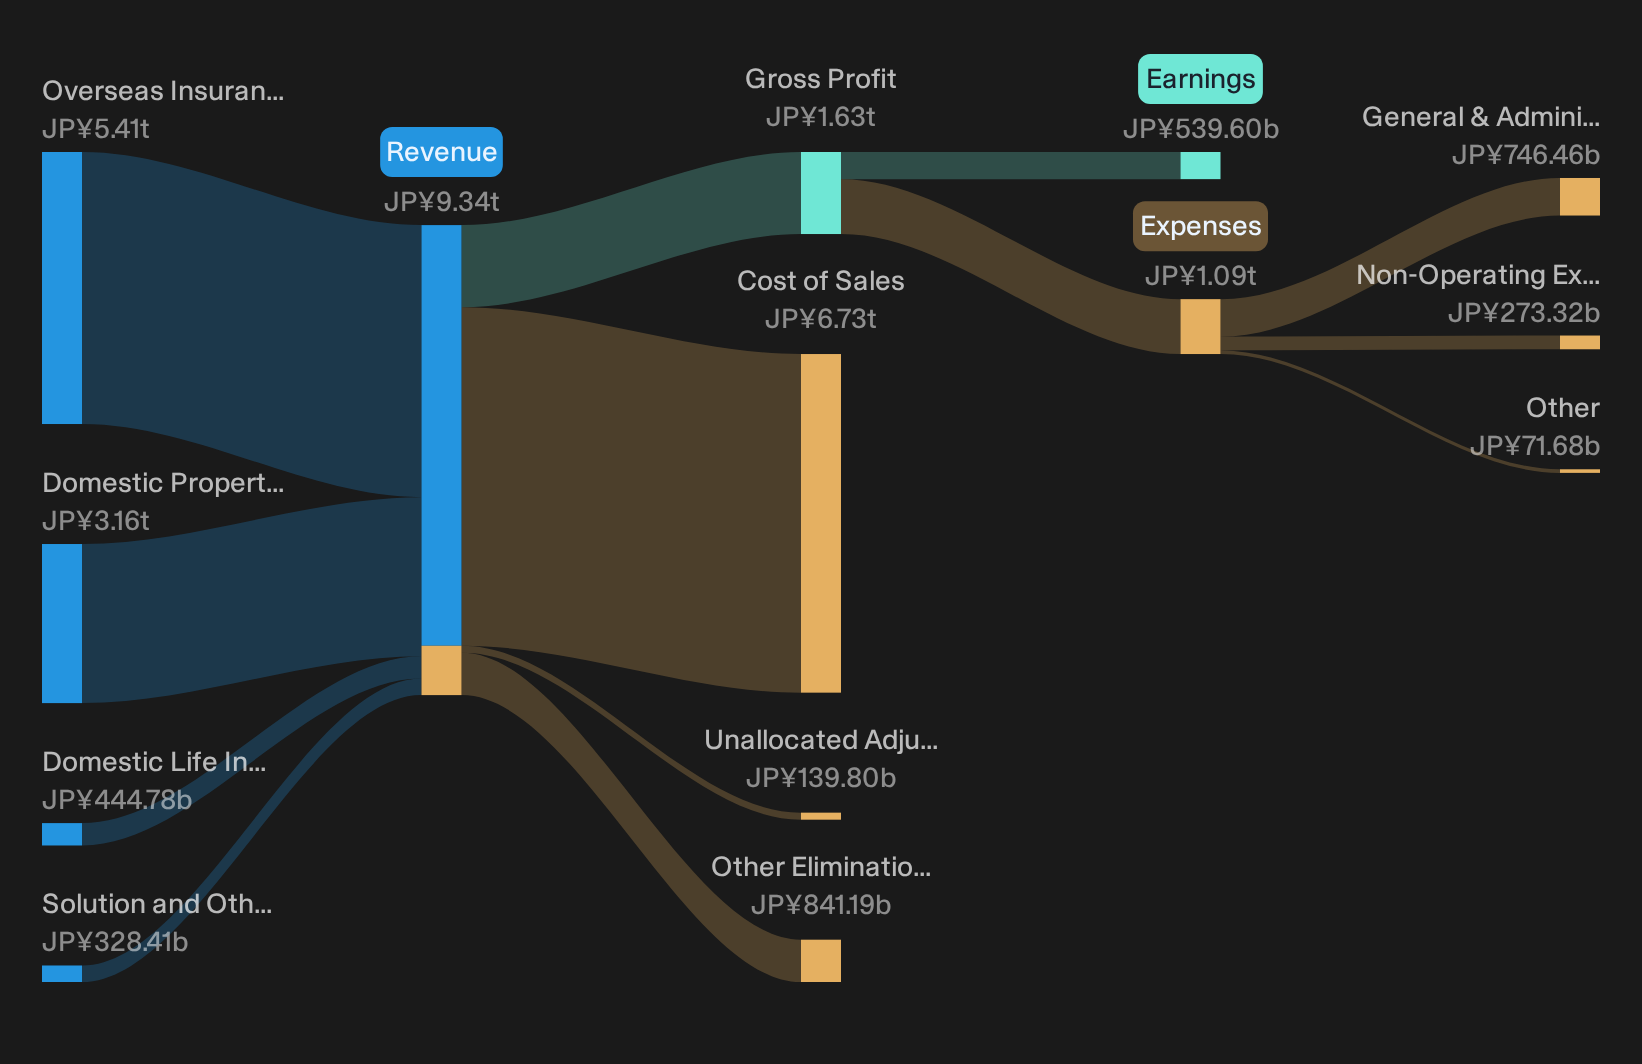
Overview: Tokio Marine Holdings is a global insurance group focused on non-life and life insurance, using recurring premiums to support dividend payouts.
Operations: Tokio Marine generates most revenue from overseas insurance at ¥5,408.0b and domestic property and casualty insurance at ¥3,162.7b, plus smaller life and solution businesses.
Market Cap: ¥14,912.6b
For dividend investors, Tokio Marine Holdings offers a mix of established insurance cash flows and capital returns that fits neatly with the Dividend Powerhouses theme, while still leaving some execution questions on the table.
"Although AI and data usage is being rolled out across Japan P&C, Brazil and North America to improve cost efficiency and underwriting, the scale and complexity of group wide implementation create execution risk. Slower than expected benefits could delay planned reductions in expense ratios and limit EPS growth."
What happens if a single key assumption about how efficiently those insurance earnings are converted into profit margins starts to shift?
If that conversion risk worries you, read the full narrative for Tokio Marine Holdings to see how Tokio Marine Holdings could still accelerate capital returns if execution improves.
Inpex (TSE:1605)
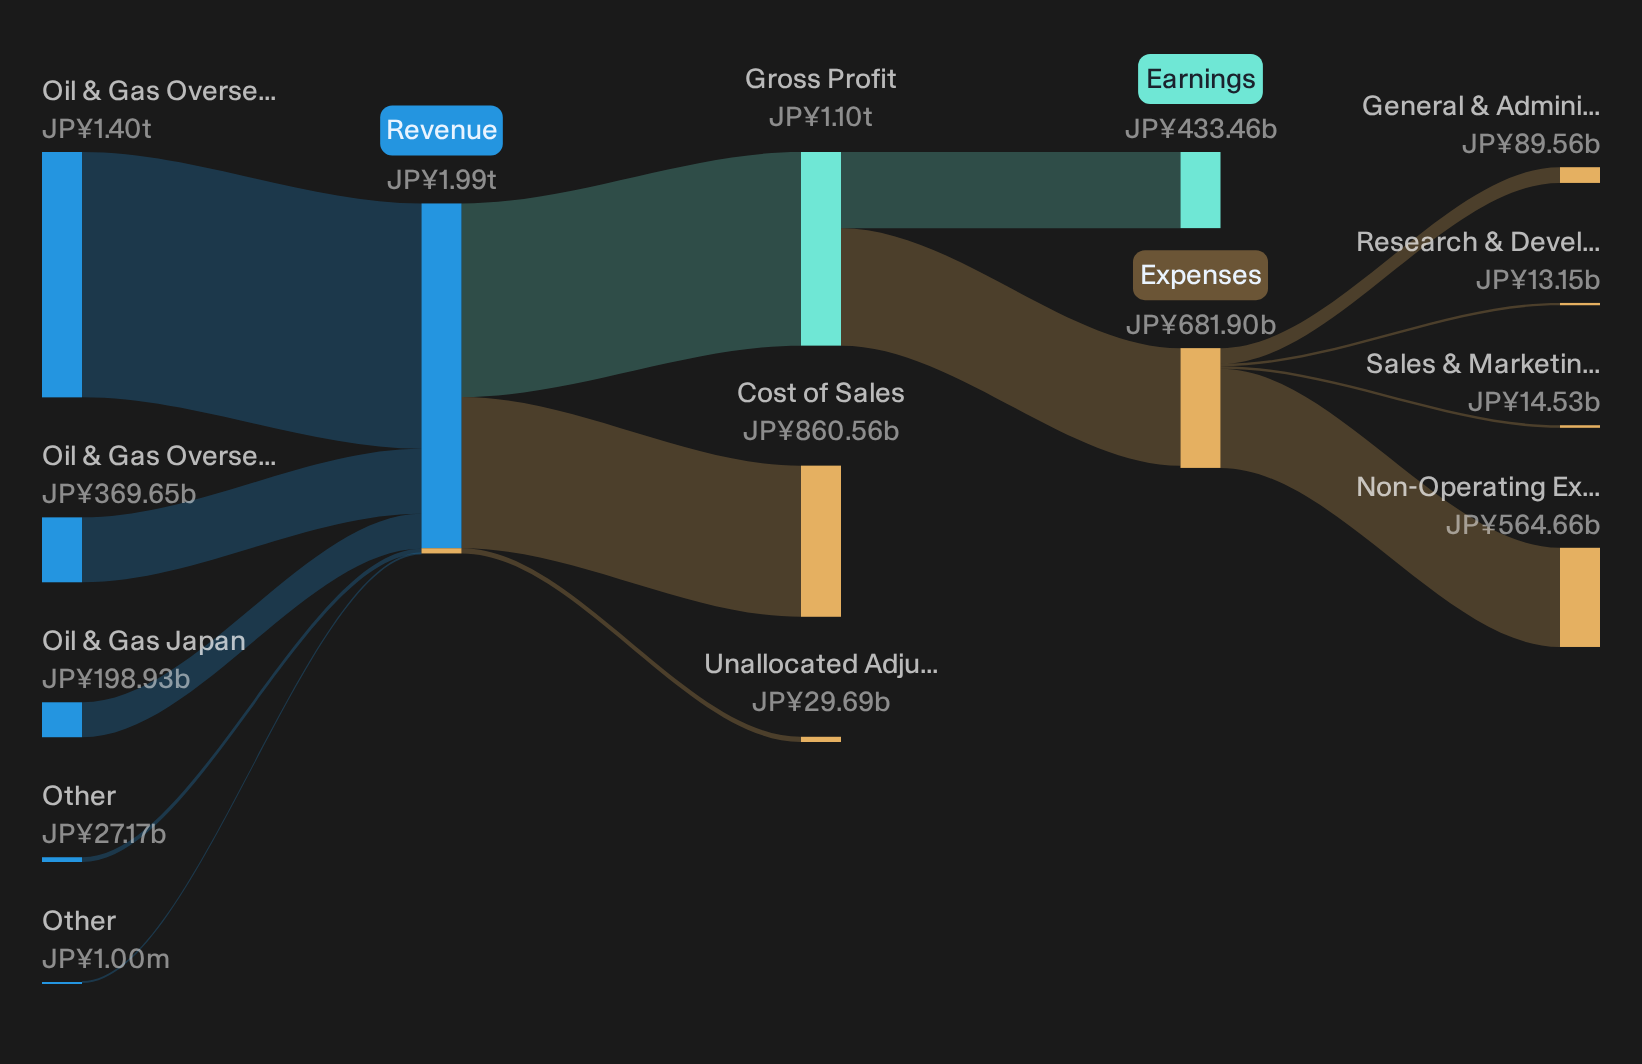
Overview: Inpex is a Japan based oil and gas producer whose upstream LNG and crude projects generate the bulk of cash supporting its dividend profile.
Operations: Inpex earns most revenue from overseas oil and gas projects at about ¥1.40t, plus roughly ¥200b from Japan and Ichthys LNG at about ¥370b.
Market Cap: ¥4.27t
Inpex appeals to dividend focused investors because its large scale LNG and crude portfolio generates recurring cash that underpins a 3%+ yield. Additional capital returns depend on how effectively that production base converts into lasting free cash.
"Organic production growth, expanded assets, and robust Asian energy demand position Inpex for higher revenue and stronger future pricing power."
The real test comes if one unseen pressure on future cash flows and dividend headroom starts to shift at the same time.
If that pressure point is on your mind, read the full narrative for Inpex to see how Inpex’s cash engine could still accelerate or stall from here.
Daiichi Sankyo Company (TSE:4568)
Overview: Daiichi Sankyo Company is a global pharmaceutical group focused on oncology drugs like Enhertu alongside cardiovascular, metabolic, vaccine and specialty treatments.
Operations: Daiichi Sankyo generates about ¥2,223.2b in revenue from its pharmaceutical operation, covering oncology, cardiovascular, metabolic and vaccine products.
Market Cap: ¥5,068.9b
For a dividend screen that cares about coverage and staying power, Daiichi Sankyo Company matters because its oncology franchise, led by Enhertu and Datroway, is the engine expected to keep funding a 3%+ payout even as the wider drug portfolio helps smooth out shocks.
"The company's pipeline productivity, evidenced by multiple late-stage ADC candidates (including HER3-DXd and I-DXd) targeting previously untapped indications and leveraging advanced biomarkers, positions Daiichi Sankyo to capture outsized future revenue as novel therapies address broader populations and high unmet needs."
What happens to that dividend profile if one yet untested assumption about how efficiently those oncology earnings convert into hard cash starts to shift?
When that cash conversion starts to shift, the full narrative for Daiichi Sankyo Company maps how Daiichi Sankyo Company’s oncology engine could accelerate dividends while risk stays in check.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Dividend stocks can stall while new themes pick up breakout momentum and leave latecomers caught holding dropping yields. Scan these under the radar lists and act now.
- Spot early turnaround potential in underfollowed companies by running the 75 high quality undiscovered gems that quietly pair resilient balance sheets with room for sentiment to catch up.
- Track where robust cash engines meet lower volatility by scanning the 21 resilient stocks with low risk scores and focusing on businesses built to absorb shocks while income stays in play.
- Target future picks and shovels for AI growth by reviewing the 88 AI infrastructure stocks supporting the hardware, data centers and tools powering the sector’s current momentum.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com