


Saul Centers (BFS) Could Be 39% Below Fair Value On Its Dividend Reset
Saul Centers (BFS) just reaffirmed its quarterly cash returns to investors by declaring dividends on both its common and preferred shares. This development puts the spotlight squarely on the REIT’s income profile today.
Recent trading tells a mixed story for Saul Centers. The share price is down about 9.2% over the past month and 19.2% over the past quarter, yet the 1 year total shareholder return of 3.49% and 3 year total shareholder return of 6.58% indicate that long term holders have still seen modest gains despite the recent loss of momentum.
Spot other real estate income plays that share Saul Centers’ focus on steady cash returns by scanning our curated list of 6 dividend fortresses.Saul Centers now trades well below both analyst targets and one intrinsic value estimate, after a sharp slide in recent months. So where does a reasonable fair value line actually fall in that gap?
Preferred P/E of 31.5x: Is it justified?
On the latest numbers, Saul Centers trades on a P/E of 31.5x, which prices the shares well above typical Retail REIT peers even after the recent pullback from $30.21.
P/E compares the current share price with earnings per share and is a common way investors judge how much they are paying for each dollar of profit. For a REIT like Saul Centers, a higher ratio often suggests the market is putting a premium on the stability of its cash flows or the perceived resilience of its property portfolio.
That premium sits awkwardly beside the fundamentals given. Earnings have declined by 5.2% per year over the past 5 years, profit margins slipped from 11.5% to 7.8%, and interest payments are not well covered by earnings. Against that backdrop, a 31.5x earnings tag implies investors are accepting a rich price relative to the recent earnings trend.
The comparison with listed peers brings this into sharper focus. Saul Centers is described as expensive on a P/E of 31.5x versus the US Retail REITs industry at 26.2x and a peer average of 19.9x, which points to a meaningfully higher valuation than both the broader group and closer comparables.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 31.5x (OVERVALUED).
Still, Saul Centers faces risks that could puncture that rich P/E story, including earnings pressure from weaker margins and interest costs that already strain current profits.
Find out about the key risks to this Saul Centers narrative.
Another View on Saul Centers’ Value
Saul Centers screens as expensive on a 31.5x P/E, yet our DCF model points in a different direction. On those cash flow assumptions, the stock screens as undervalued with a future cash flow value of $42.04 against a share price of $30.21, which leaves investors asking which lens deserves more weight.
Look into how the SWS DCF model arrives at its fair value.
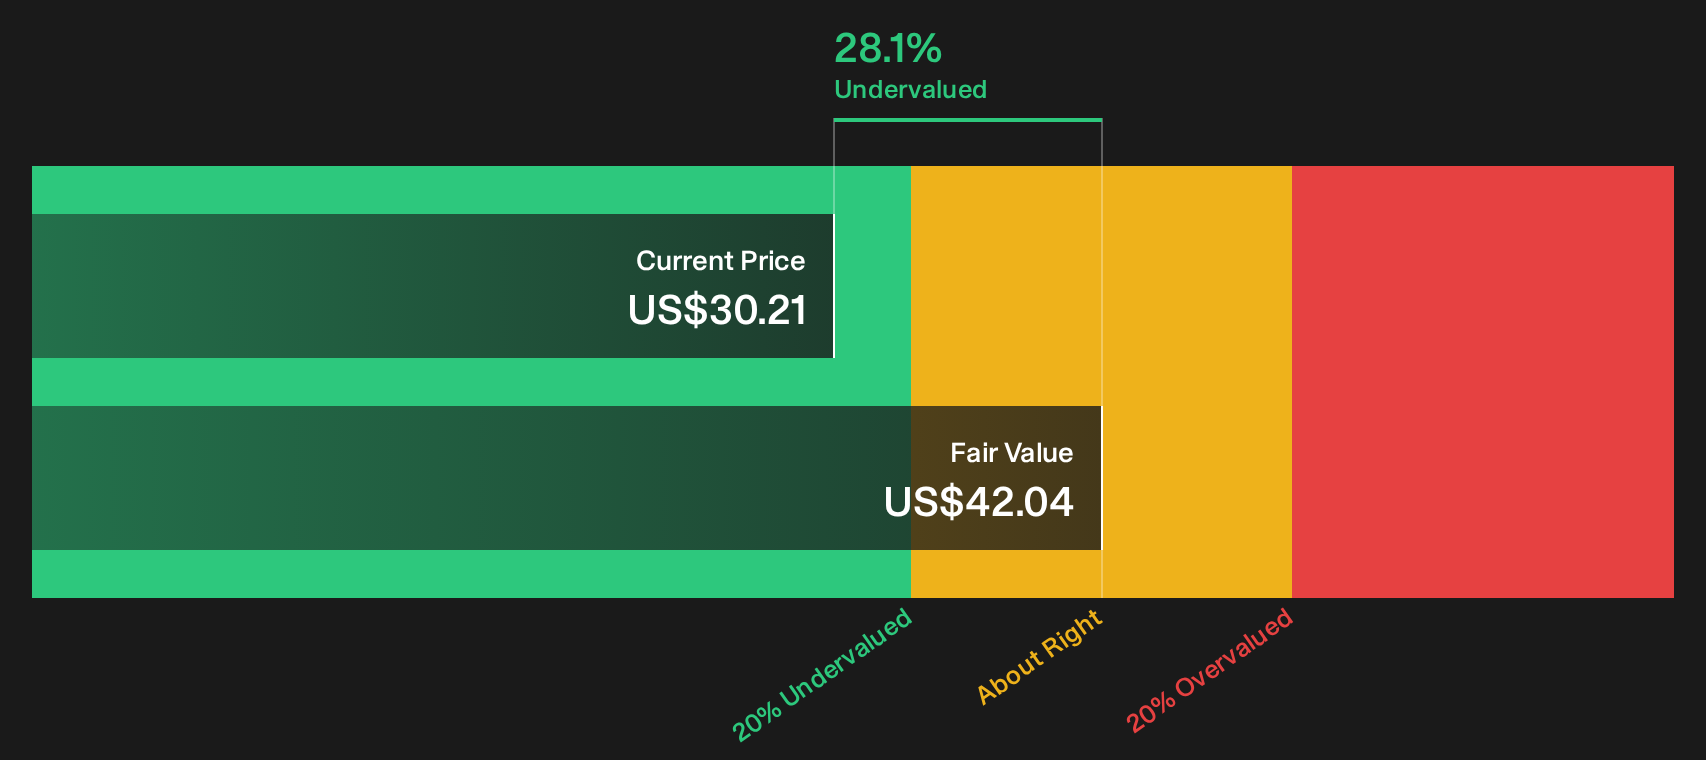
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Saul Centers for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals so far on Saul Centers. If you want to cut through conflicting valuation cues and sentiment, weigh the data yourself and stress test both sides of the story using the 2 key rewards and 3 important warning signs.
Ready for more ideas beyond Saul Centers?
If Saul Centers has you thinking harder about valuation and income, consider widening your opportunity set now so you can plan ahead rather than react to the next move.
- Target steady cash generation and filter for higher-yield options by reviewing our hand picked group of 6 dividend fortresses.
- Hunt for quality at a discount and compare Saul Centers against a broader pool of potentially mispriced opportunities with the 32 high quality undervalued stocks.
- Prioritize resilience first and focus on companies with stronger finances and healthier balance sheets using this curated list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com