


Nitto Boseki (TSE:3110) Joins FTSE All World Index, Is The Valuation Still Cheap?
Nitto Boseki (TSE:3110) has been added to the FTSE All-World Index (USD), a move that can draw attention from global index trackers and broad-based international funds.
Recent trading has been mixed for Nitto Boseki, with the share price easing over the past day and week, while still holding a positive 30 day share price return and a strong year to date gain. That sits alongside a very large 1 year total shareholder return and multi year total shareholder returns that suggest earlier investors have already seen substantial upside, so the index inclusion may now be reframing expectations around future growth and risk rather than starting a fresh momentum phase.
Spot opportunities around Nitto Boseki's index inclusion by comparing it with list of solid balance sheet and fundamentals (22 results), which could also attract attention from global funds.Nitto Boseki now has broader visibility and a long run of strong shareholder returns on the table. The next issue is simple: Does the current valuation still leave enough upside for new capital coming in today?
Preferred P/E of 12.5x for Nitto Boseki: Is it justified?
On simple earnings maths, Nitto Boseki trades on a P/E of 12.5x, which sits alongside a large discount to internal fair value estimates and a strong run in the share price over the past year. For anyone watching the FTSE All-World Index move, the key question is whether that earnings multiple already reflects much of the good news or still prices in some caution.
The P/E ratio compares the current share price to earnings per share. It effectively shows how many years of current profit the market is willing to pay for. This matters for a diversified industrial group like Nitto Boseki that spans electronic materials, medical products, composite materials and insulation.
Here, several pieces of evidence pull in different directions. On one hand, the business is labelled as good value relative to peers, with a P/E of 12.5x versus 34x for the comparison group and 12.7x for the JP Building industry. It is also described as good value versus an estimated fair P/E of 18.7x, which suggests the market is assigning a lower earnings multiple than a fair value model implies the stock could support.
On the other hand, the forecasts flag some pressure on the bottom line. Earnings are projected to decline by about 5.5% per year over the next three years, despite revenue being expected to rise 15.8% per year and outpace the broader JP market at 6.5%. That split hints that a chunk of the current profitability is tied to large one off items, including a very large ¥37.0b gain that affects the last twelve months through 30 June 2026 and limits how clean the trailing P/E really is.
Against that backdrop, the current P/E of 12.5x looks low compared with both peers at 34x and the fair P/E estimate of 18.7x. This frames the valuation as conservative relative to those benchmarks. The fair ratio level of 18.7x is described as the kind of multiple the stock could move toward if earnings normalise closer to underlying cash generation and one off effects fade.
Explore the SWS fair ratio for Nitto Boseki.
Result: Price-to-Earnings of 12.5x (UNDERVALUED)
Still, the earnings outlook and reliance on large one off gains leave room for disappointment if Nitto Boseki’s profitability normalises faster than the market expects.
Find out about the key risks to this Nitto Boseki narrative.
Another view on Nitto Boseki’s value
A second lens on Nitto Boseki comes from the SWS DCF model, which prices the shares at ¥3,055 against an estimated future cash flow value of ¥9,710.8. That points to a very large gap on the upside. The question is whether those long range cash assumptions will really hold.
Look into how the SWS DCF model arrives at its fair value.
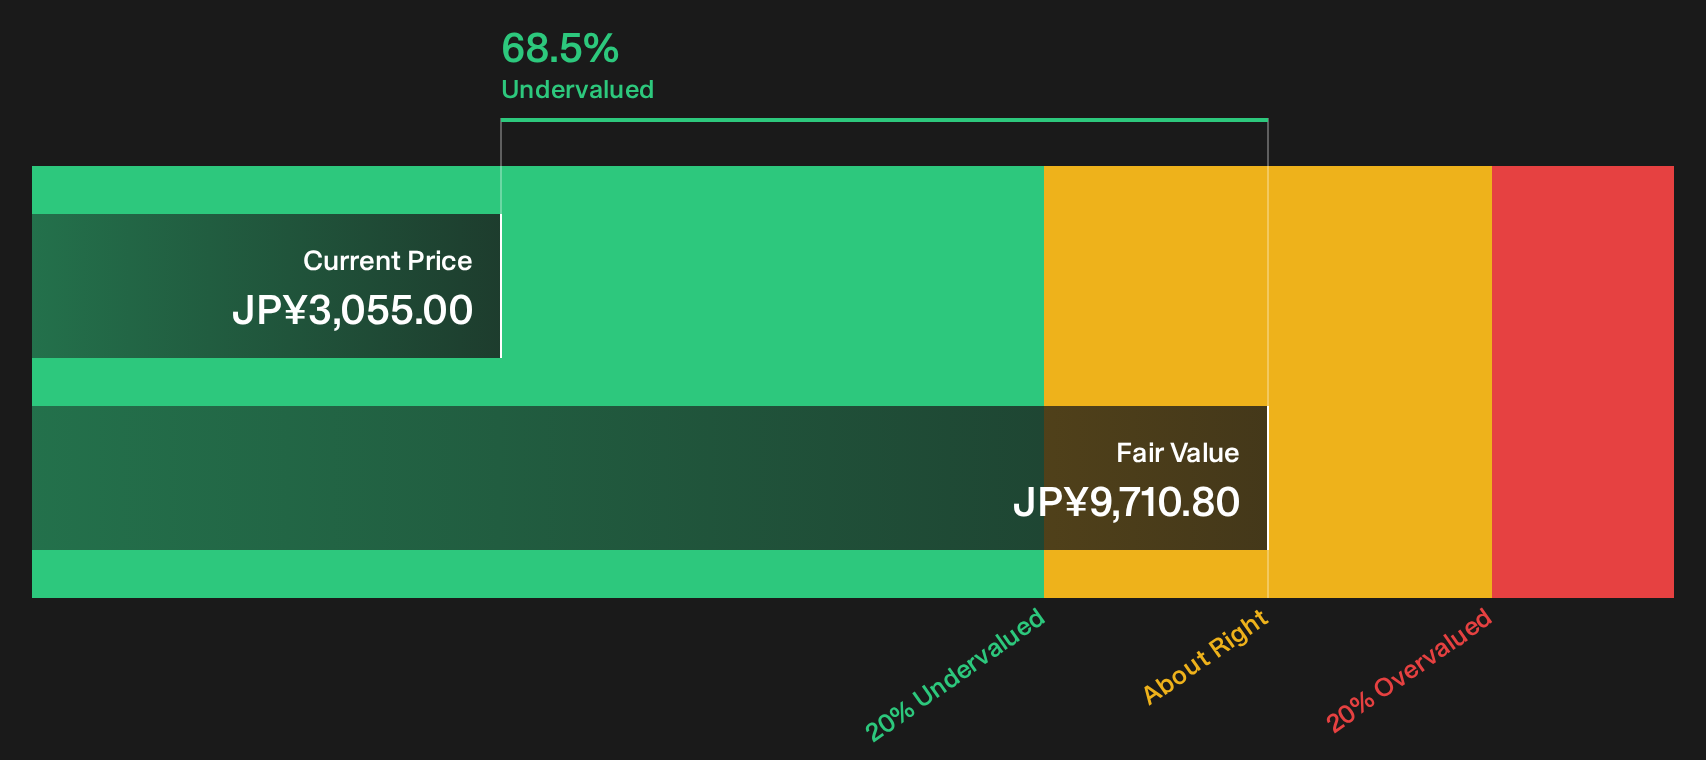
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nitto Boseki for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Nitto Boseki’s valuation and earnings outlook can feel messy, so it makes sense to review the full data and decide fast where you stand. To weigh up both sides of that story, take a closer look at the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Nitto Boseki?
Once you have formed a view on Nitto Boseki, it can be useful to compare it with other opportunities so you are not anchored to a single story.
- Target income resilience by scanning for companies with reliable payouts using the 20 dividend fortresses that filters for higher yielding dividend fortresses with a focus on stability.
- Hunt for mispriced quality by running through the 17 high quality undervalued stocks which highlights high quality undervalued stocks with solid cash flows and robust balance sheets.
- Prioritise capital preservation by reviewing the 21 resilient stocks with low risk scores and concentrating on resilient stocks with low risk scores before market sentiment shifts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com