


How Index Removal Will Impact StarHub (SGX:CC3) Investors
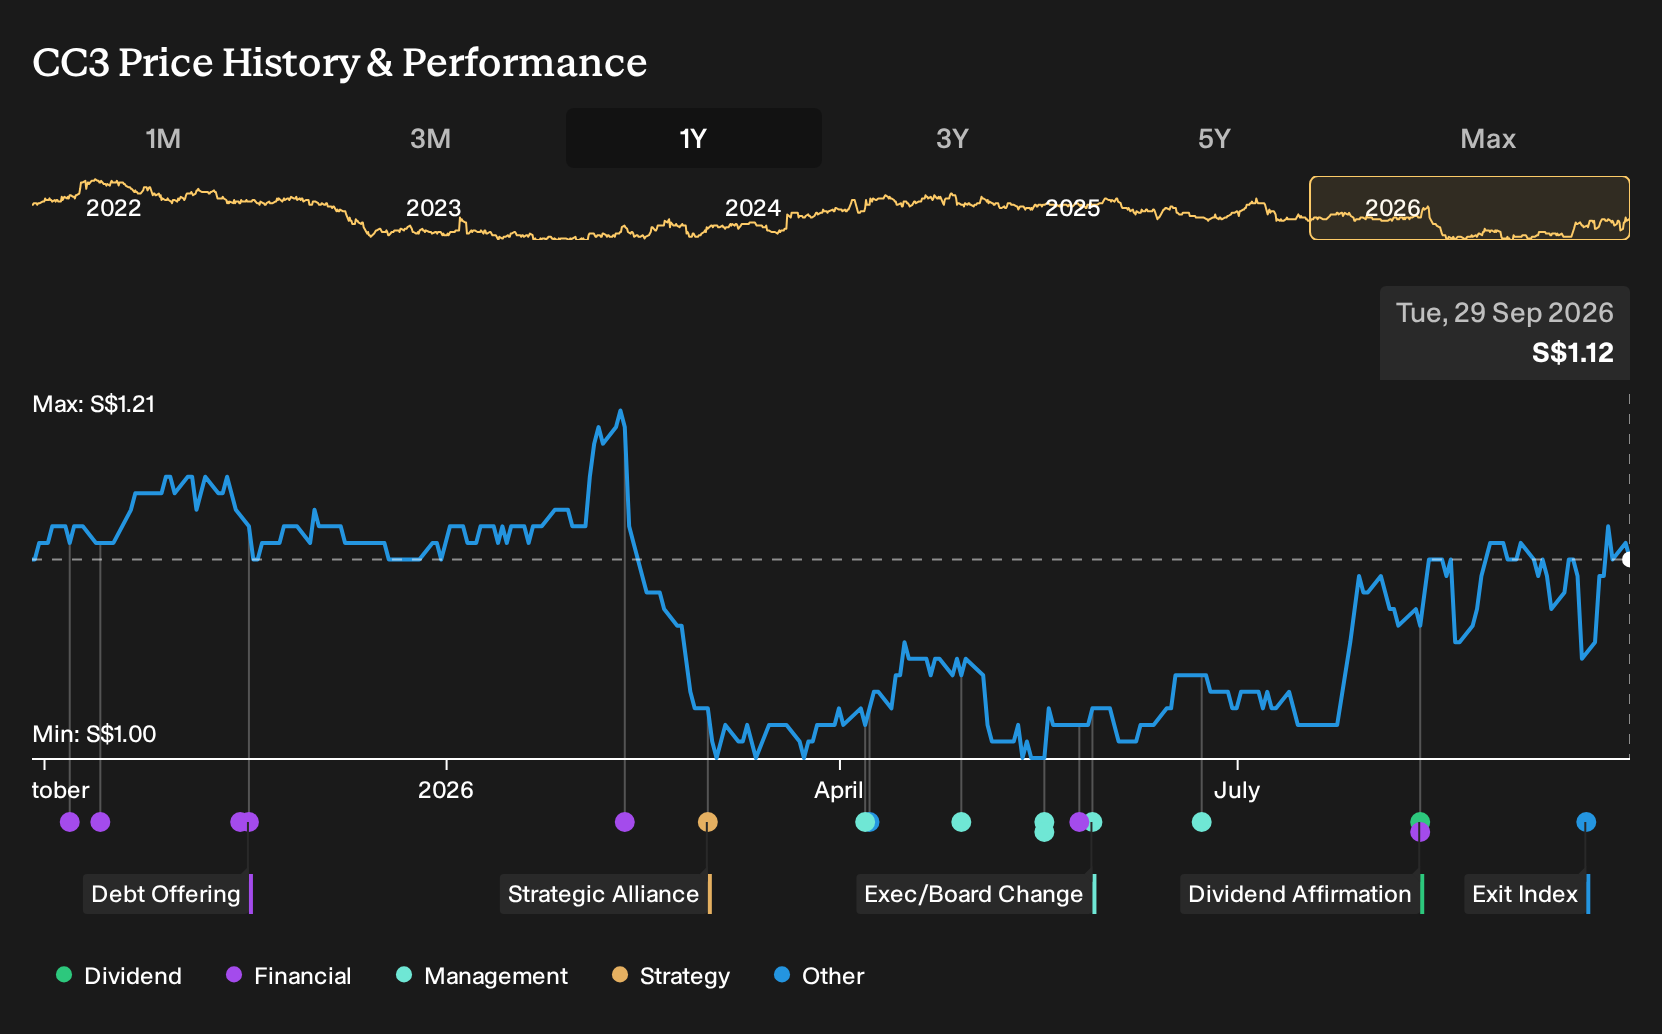
- StarHub Ltd was removed from the FTSE All-World Index (USD) in September 2026, prompting index-tracking investors to adjust their holdings.
- The exclusion highlights how StarHub's fundamentals and sector realities now play a more important role in capital access than passive index inclusion alone.
- We will now examine how StarHub's investment narrative could shift after its removal from the FTSE All-World Index.
Reassess where StarHub sits in your portfolio and scan a curated set of 198 high quality undervalued stocks that could benefit when index flows shift away from former constituents.
StarHub Investment Narrative Recap
To stay invested in StarHub, you need to be comfortable with a business that leans heavily on Singapore telecom and cybersecurity, while working through pressure in mobile, Pay TV and interest coverage. The big near term swing factor is execution in Ensign and the enterprise segment, which management expects to support earnings even as mobile revenue has come under strain.
The largest operational risk right now sits in earnings quality and cash demands. One off gains and DARE+ transformation costs blur the underlying run rate. At the same time, upcoming 700 MHz spectrum related spending and weaker entertainment revenue could test margins and any ambition to keep dividends steady.
There has not been a fresh announcement directly tied to the FTSE All World Index exit. The most relevant context for you is still the DARE+ transformation and the Q4 expectations for Ensign. Those plans remain operational in nature. Index removal itself does not change StarHub's ability to pursue cost efficiencies or enterprise growth.
This index change refocuses attention on whether those internal projects can offset softer mobile and entertainment trends and support interest coverage. If you stay on the stock, you are really watching contract wins and cost savings, not index status. The thesis now leans more on execution and less on passive flows.
What The New Analyst Path Implies For StarHub
StarHub's narrative projects SGD2.2b revenue and SGD109.9m earnings by 2029. This aligns with analyst assumptions that top line will stay broadly flat and reflects an earnings decrease of about SGD175.8m from current earnings of SGD285.7m.
Uncover why StarHub's fair value indicates a 4% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
One contrasting catalyst in the bullish narrative is StarHub’s enterprise order book growing at more than 20% a year, with longer 3 to 5 year contracts that could smooth earnings. The most optimistic analysts were pencilling in about SGD2.5b of revenue and SGD94.3m of earnings by 2029. Those views pre date the index exit, so you may want to compare them with your own expectations and consider how opinions could shift after the removal.
Explore 3 other StarHub fair value estimates, including one that suggests as much as 336% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your StarHub research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for StarHub. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate StarHub's overall financial health at a glance.
Looking for more StarHub sized investment ideas?
Once you have a clear view on StarHub, it can help to widen the search and see how other businesses stack up on quality, valuation and resilience. The Simply Wall St Screener can surface a broader watchlist that matches your risk tolerance and return goals.
- If capital protection comes first for you, focus on resilience and balance sheet strength by checking companies in our 223 resilient stocks with low risk scores that tend to show steadier fundamentals through different cycles.
- For investors who care most about quality at a reasonable entry point, compare StarHub with a curated 618 high quality undiscovered gems that may not yet be widely followed but have solid underlying metrics.
- If you want businesses that can better handle shocks, prioritise financial sturdiness and cash support by reviewing a list of solid balance sheet and fundamentals (203 results) that filters for stronger funding positions and fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com