


Ormat Technologies (ORA) Wins DOE Backing, Is The Stock Still Undervalued?
DOE funding puts Ormat’s geothermal projects in focus
Interest in Ormat Technologies (ORA) has picked up after the U.S. Department of Energy selected the company and its partners for up to $35 million in geothermal project funding.
The package covers an Enhanced Geothermal Systems effort at Dixie Valley in Nevada and hydrothermal work at Cove Fort in Utah, both tied to existing Ormat facilities and subject to final DOE award negotiations.
Ormat Technologies’ latest DOE grant news lands after a choppy stretch, with the share price down 3.49% over the past day and 20.55% year to date, while total shareholder return is down 5.04% over one year but up more than 35% over both three and five years. This indicates longer term holders have still seen gains even as recent momentum has faded.
Scan beyond Ormat Technologies and see how other grid and renewables plays are reacting to the same policy tailwinds with our curated 39 power grid technology and infrastructure stocks
Ormat Technologies appears to be a focused geothermal specialist benefiting from fresh DOE backing, yet the share price has slipped this year. Does that recent weakness leave the stock attractively priced or still demanding?
Most Popular Narrative: 33% Undervalued
Analyst models put Ormat Technologies’ fair value well above the last close of $90.36, which frames the recent price slide as a potential disconnect between narrative and market pricing.
Extension of production and investment tax credits (PTC/ITC) for geothermal and energy storage projects through at least 2033 reduces capital costs, decreases risk for new project development, and boosts net margins and earnings over the next decade. Elevated demand for reliable, carbon free baseload power driven by electrification trends (including data centers and industrial customers) is translating into premium power purchase agreement (PPA) pricing, supporting improved revenue visibility and margin expansion.
See why 11 investors see Ormat Technologies as 33% undervalued.
Result: Fair Value of $135.45 (UNDERVALUED)
Still, the bullish story for Ormat Technologies depends on heavy capex being rewarded and on US rules around Chinese battery content not tightening in a way that hits storage returns.
Find out about the key risks to this Ormat Technologies narrative.
Another View: Multiples Paint A Richer Picture For Ormat Technologies
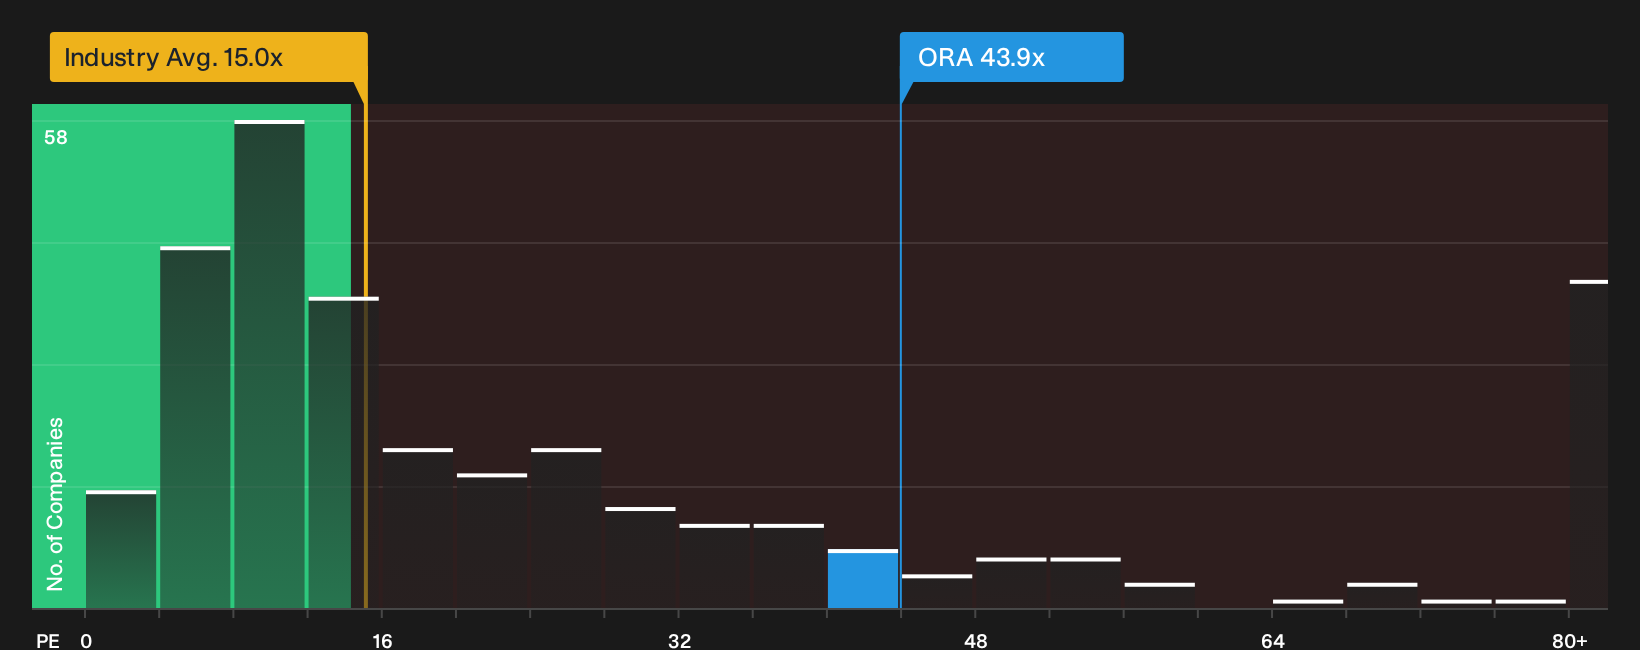
The first narrative frames Ormat Technologies as undervalued relative to analyst fair value, yet the current P/E of 43.9x tells a different story. That multiple sits well above the renewable energy industry on 14.9x, the peer group on 30.7x, and even the modelled fair ratio of 25.5x. For investors, that gap points to higher valuation risk if sentiment or earnings expectations cool.
For a closer look at how that pricing compares across sectors and peers, and where the fair ratio suggests the market could drift over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Ormat Technologies can be confusing. Move quickly, review the numbers yourself, weigh both sides of the story, and then decide whether the balance of risks and potential upside fits your portfolio with 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Ormat Technologies?
If Ormat Technologies has your attention, do not stop here. Broaden your watchlist with fresh ideas that match different risk levels and income goals.
- Target potential mispricing by scanning companies that combine quality fundamentals with appealing valuations through our 32 high quality undervalued stocks.
- Strengthen your income stream by reviewing resilient payers and their yields in the 6 dividend fortresses.
- Protect your capital by focusing on sturdier balance sheets and steadier fundamentals using the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com