


Earnings Preview: What To Expect From Wells Fargo's Report
With a market cap of $244.4 billion, Wells Fargo & Company (WFC) is a leading financial services company, offering a diversified range of banking, investment, mortgage, and consumer and commercial finance products and services. The company operates through four main segments: Consumer Banking and Lending; Commercial Banking; Corporate and Investment Banking; and Wealth & Investment Management.
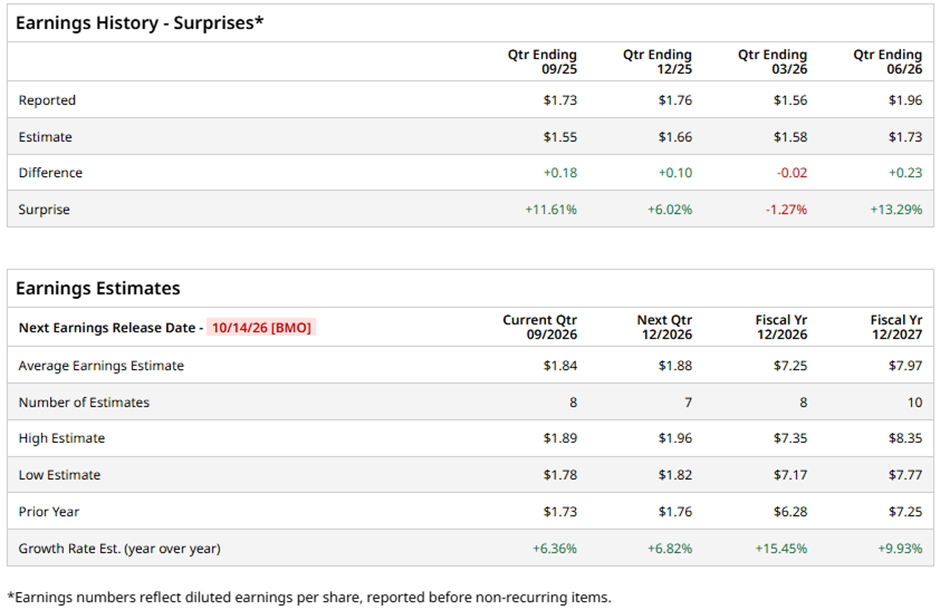
The San Francisco, California-based company is set to release its fiscal Q3 2026 results before the market opens on Wednesday, Oct. 14. Ahead of this event, analysts expect the company to report an EPS of $1.84, up 6.4% from $1.73 in the prior year's quarter. It has surpassed Wall Street's bottom-line estimates in three of the past four quarters while missing on another occasion.
For fiscal 2026, analysts forecast the banking giant to post EPS of $7.25, reflecting a 15.5% increase from $6.28 in fiscal 2025.
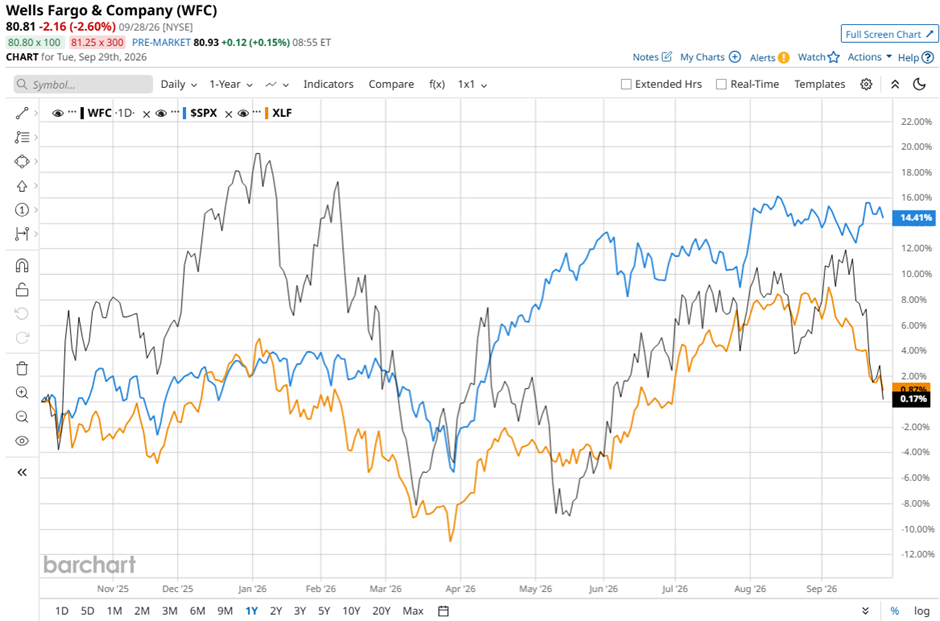
Shares of Wells Fargo have fallen 4.3% over the past 52 weeks, lagging behind the S&P 500 Index's ($SPX) 15.7% gain and the State Street Financial Select Sector SPDR ETF's (XLF) marginal return over the period.
Despite reporting better-than-expected Q2 2026 EPS of $2 and revenue of $22.62 billion, Wells Fargo shares fell 2.7% on Jul. 14 due to weaker net interest margin. Net interest margin declined to 2.43% from the prior quarter and a year earlier, below the estimate, with Wells Fargo maintaining its 2026 net interest income guidance of about $50 billion rather than raising it.
Analysts' consensus view on WFC stock is cautiously optimistic, with a "Moderate Buy" rating overall. Among 26 analysts covering the stock, 15 recommend "Strong Buy," three suggest "Moderate Buy," and eight indicate “Hold.” The average analyst price target of $101.38 is a premium of 25.5% to current levels.
On the date of publication, Sohini Mondal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.