


Pacira BioSciences (PCRX) Stock Looks Expensive Relative To Its Earnings Power
Pacira BioSciences has produced a mixed ride for shareholders, with the stock roughly flat over the past year but carrying a much weaker 5 year record. This naturally puts the spotlight on whether the current share price lines up with its earnings power. Investors now have to decide if the recent share price level around US$25 reflects what the business is actually earning or if expectations have drifted away from the underlying numbers.
- Over the past 5 years the share price has fallen 48.7%, which raises the question of whether earnings have also stepped down or if the market has simply marked the stock lower while the business kept building its profit base.
- The company’s profile as a specialty pharmaceutical business means future earnings may hinge on how effectively it converts its existing product portfolio into consistent cash generation and controls the costs tied to sales and research.
- Your read on Pacira BioSciences is one view; the desks covering it have another. See what analysts think Pacira BioSciences's shares could be worth.
The issue now is whether Pacira BioSciences’ current valuation is justified by the earnings investors can reasonably expect the business to produce.
If you want a benchmark while you weigh Pacira BioSciences against other earnings focused ideas, compare it with companies in the 32 high quality undervalued stocks
Is Pacira BioSciences Getting Expensive on Earnings?
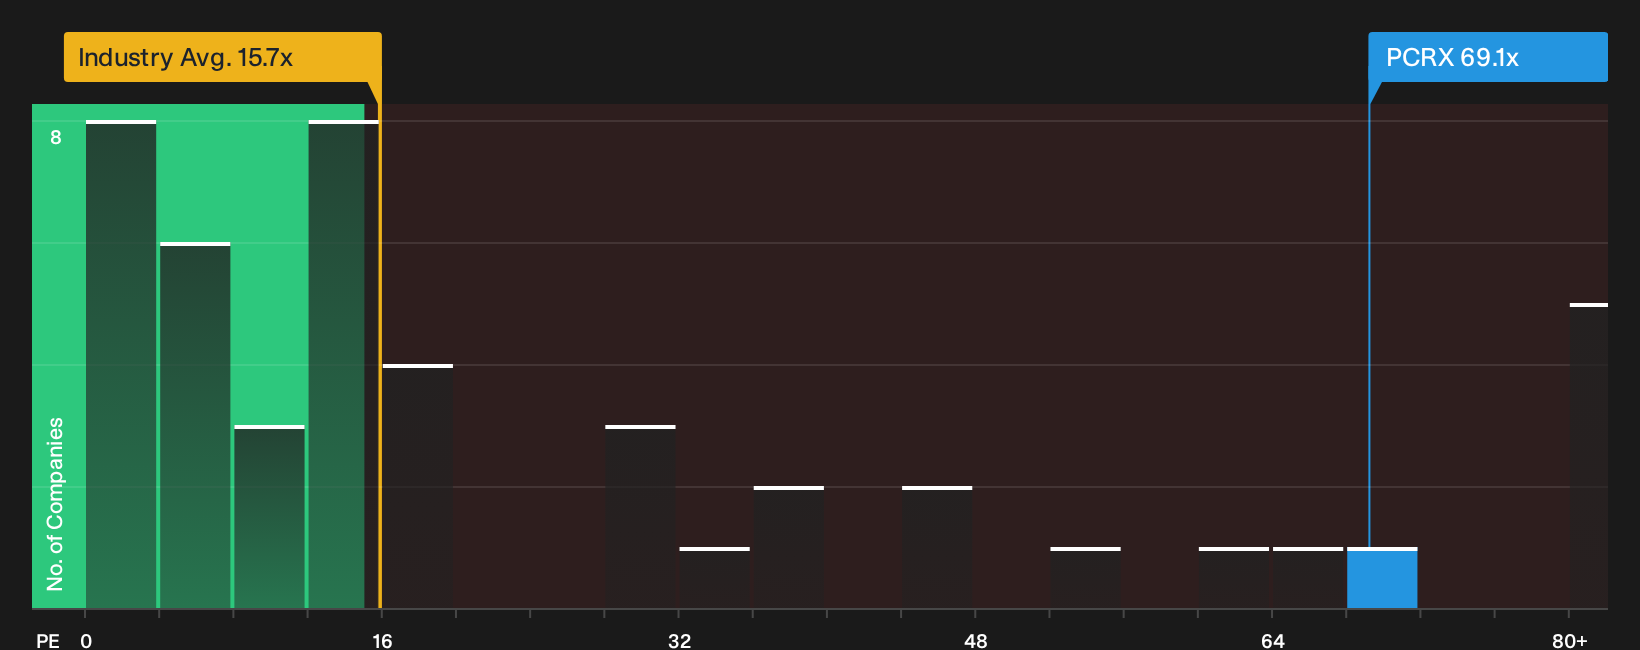
The P/E ratio works reasonably well for Pacira BioSciences because investors are mainly paying for its ability to turn existing products into ongoing earnings. At the current share price, Pacira BioSciences trades on a P/E of 69.1x, which is far above the Pharmaceuticals industry average of 15.7x and also well ahead of the broader peer group at 9.9x. That is a big gap for a business where the market already knows the main product set.
The tailored fair multiple, which blends in the company’s growth outlook, profitability profile and risk, comes out well below the present 69.1x level. The model is heavily penalising the stock on this framework, so the spread looks more like a warning flag that Pacira BioSciences screens very expensive on earnings rather than a precise estimate of where the P/E “should” land. Readers weighing the shares at today’s price are effectively being asked to pay a premium earnings tag and decide whether the underlying business quality justifies it. Explore the numbers behind Pacira BioSciences's P/E valuation.
The Pacira BioSciences Narrative: What Would Justify Today's Price?
Pacira BioSciences' high P/E creates a clear question for you as an investor, and Narratives are where that question gets spelled out in concrete terms. Each scenario on Simply Wall St's Community page explains what would need to happen to the firm's growth, margins and earnings for the stock to be worth materially more or less than it is today. Each one links a fair value to a specific mix of potential catalysts and risks so you can track which storyline is closest to reality over time.
Pacira BioSciences attracts two very different readouts from the community, with one camp seeing meaningful upside and the other flagging valuation risk.
Bull case: 33% undervalued
"The J&J MedTech partnership for ZILRETTA effectively doubles sales coverage and unlocks access to broad, untapped physician networks..."
Discover why this Narrative puts Pacira BioSciences at 33% undervalued.
Bear case: 15% overvalued
"With governments and private insurers intensifying efforts to contain healthcare costs, Pacira will face increasingly rigorous cost-effectiveness requirements..."
Explore why this Narrative puts Pacira BioSciences at 15% overvalued.
The Pacira BioSciences share price is only one piece of the decision
Before you decide how Pacira BioSciences fits into your portfolio, it helps to understand who is steering the business, what they are paid for, and how their incentives line up with your goals. See who runs Pacira BioSciences and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com