


USA Rare Earth (USAR) Stock Still Looks Reasonable After $3.1B Funding News
USA Rare Earth has delivered a strong 41.1% gain over the past three years, even though shorter term returns have been weaker. That mix of outcomes raises a straightforward question for you as an investor: Is the current share price still in step with what the company has built up on its balance sheet, particularly its book value, or has sentiment moved ahead of the underlying equity base?
- The 41.1% rise over three years puts real weight on whether USA Rare Earth's current valuation can be explained by the capital already invested in the business and recorded as book value.
- The recent US$3.1b funding package and new technology partnerships may support a larger asset base over time, which can reshape how the book value story lines up with today’s market price.
- The analysts covering USA Rare Earth have run their own numbers. See what analysts think USA Rare Earth's shares could be worth.
The issue now is whether USA Rare Earth's current market value is adequately supported by its book value once you line it up against the industry average.
If you want to explore the same book value question beyond USA Rare Earth, you can broaden your watchlist with 36 best rare earth metal stocks.
Does USA Rare Earth Look Undervalued on Book Value?
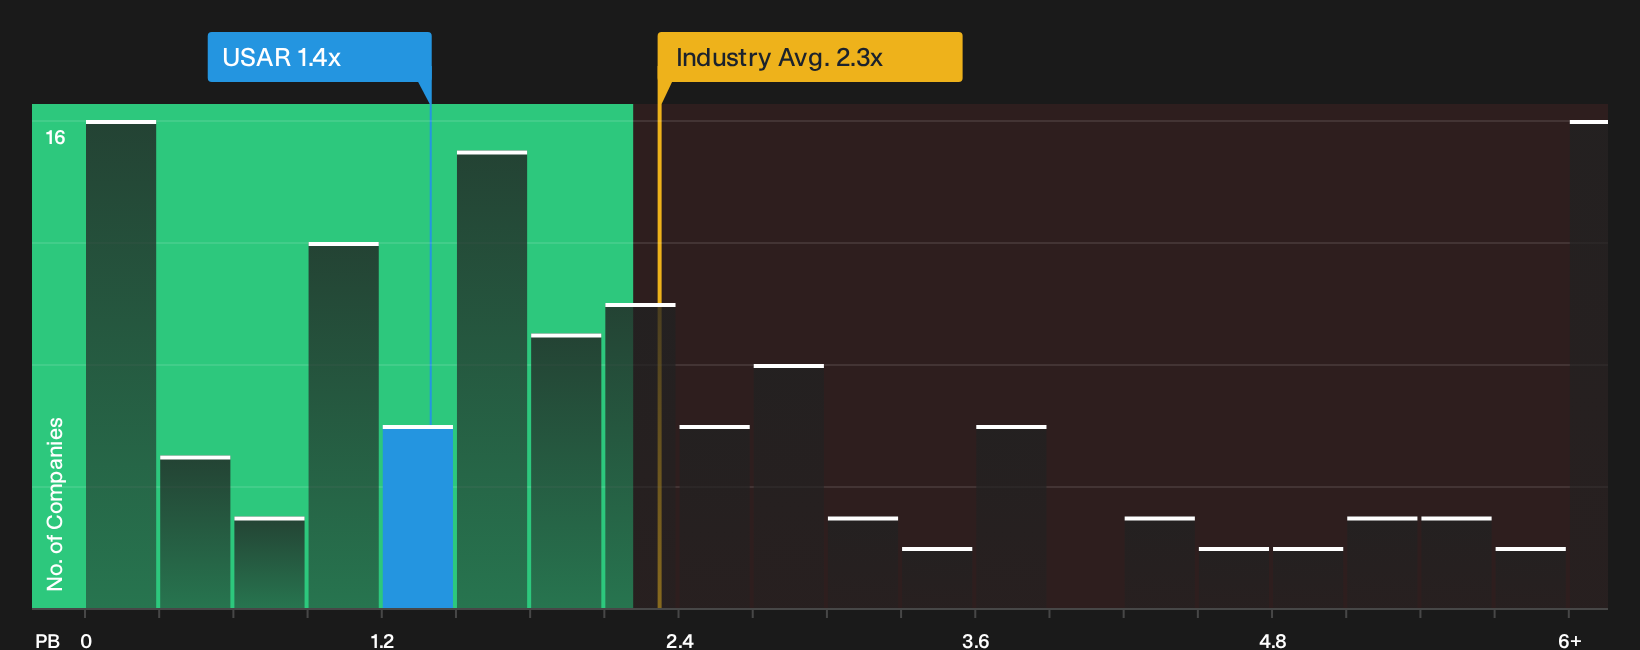
P/B is a useful lens for USA Rare Earth because the business is currently more about assets and project build out than mature earnings. On this measure, the stock trades at roughly 1.4x its book value, while the wider Metals and Mining group averages about 2.3x. That gap suggests the market is pricing USA Rare Earth’s equity base at a discount to what investors typically pay for balance sheets in the sector.
The P/B comparison appears even more pronounced against peers, where similar companies cluster closer to about 6.3x book. Despite the recent US$3.1b funding package lifting attention on USA Rare Earth, the current multiple still values the share price below both the industry and peer benchmarks on this metric. That leaves you weighing whether the concerns highlighted in recent news fully explain the lower P/B or whether the gap simply reflects current market views on risk and execution for this project. Explore the numbers behind USA Rare Earth's P/B valuation.
The USA Rare Earth Narrative: What Would Justify Today's Price?
Narratives for USA Rare Earth pick up where the P/B question leaves off and spell out which future paths for growth, margins and earnings would make the current valuation look stretched or conservative. Each storyline on Simply Wall St's Community page links today’s market price to a specific set of business outcomes, so instead of a single ratio or model output, you see the underlying assumptions you can watch over time.
Community views on USA Rare Earth are split between those who see a vertically integrated rare earth chain taking shape and others who focus on execution and funding risks.
Bull case: 59% undervalued
"USA Rare Earth is building an integrated rare earth supply chain, from mining and processing to metal, alloy and magnet manufacturing…"
Discover why this Narrative puts USA Rare Earth at 59% undervalued.
Bear case: 4268% overvalued
"CEO Barbara Humpton described the DOE selection as “an important validation of our team’s cutting edge work to build a resilient rare earth value chain”…"
Explore why this Narrative puts USA Rare Earth at 4268% overvalued.
One more angle on USA Rare Earth that could shift how you see today’s price
Balance sheet metrics tell part of the story for USA Rare Earth, yet broker models sketch where they think cash flows and projects might land a few years from now. Explore where analysts expect USA Rare Earth to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com