


IDACORP (IDA) Raises Its Dividend, Is The Stock Cheap Or Expensive?
Why IDACORP’s Higher Dividend Matters Now
IDACORP (IDA) just approved a higher regular quarterly dividend of $0.90 per share, lifting the indicated annual payout to $3.60. The move signals management’s confidence in the utility’s cash generation and shareholder return approach.
IDACORP’s share price has cooled in recent months, with the stock down 5.13% on a 1 month share price basis and 14.86% over 3 months. Even as the latest US$128.81 level sits slightly ahead year to date, long term total shareholder returns of 57.44% over 3 years and 42.19% over 5 years still point to a solid historical payoff for patient investors.
Compare IDACORP’s higher payout with a curated group of income-focused opportunities by reviewing the 6 dividend fortresses, which may offer resilient cash distributions alongside potential share price upside.
IDACORP looks like a solid utility with rising dividends and steady earnings, yet the share price has slipped in recent months. Is the stock now a fair deal, or is it still asking too much?
Most Popular Narrative: 19% Undervalued
On the latest figures, the prevailing valuation narrative pegs IDACORP’s fair value at $158.10. This sits above the recent $128.81 close and frames the stock as trading at a discount that hinges heavily on execution of its long range growth plan.
Robust customer and population growth in IDACORP's service area, combined with significant new large scale industrial investments (e.g., Micron fabs, data centers), is cited as a factor that may contribute to sustained above average electricity demand well into the 2030s, which in turn is viewed by some as supportive of long term revenue growth.
Electrification trends, including increased deployment of EV fast-charging infrastructure and broader electrification of end uses, are described as drivers of incremental kWh sales and recurring revenue, with additional load growth potential from new projects that are not yet included in official load projections.
See why 4 investors see IDACORP as 19% undervalued.
Result: Fair Value of $158.10 (UNDERVALUED)
Still, the IDACORP story can change quickly if hydro conditions stay unfavorable or if regulators push back on the recovery of rising grid and generation costs.
Find out about the key risks to this IDACORP narrative.
Another Take: SWS DCF Model Paints A Tougher Picture
The popular narrative frames IDACORP as about 19% undervalued around $158.10, yet the SWS DCF model points the other way. On that cash flow view, IDACORP at $128.81 trades above an estimated value of $112.08, which implies the stock screens as expensive on this metric. So which story do you trust more: the growth narrative or the cash flows?
Look into how the SWS DCF model arrives at its fair value.
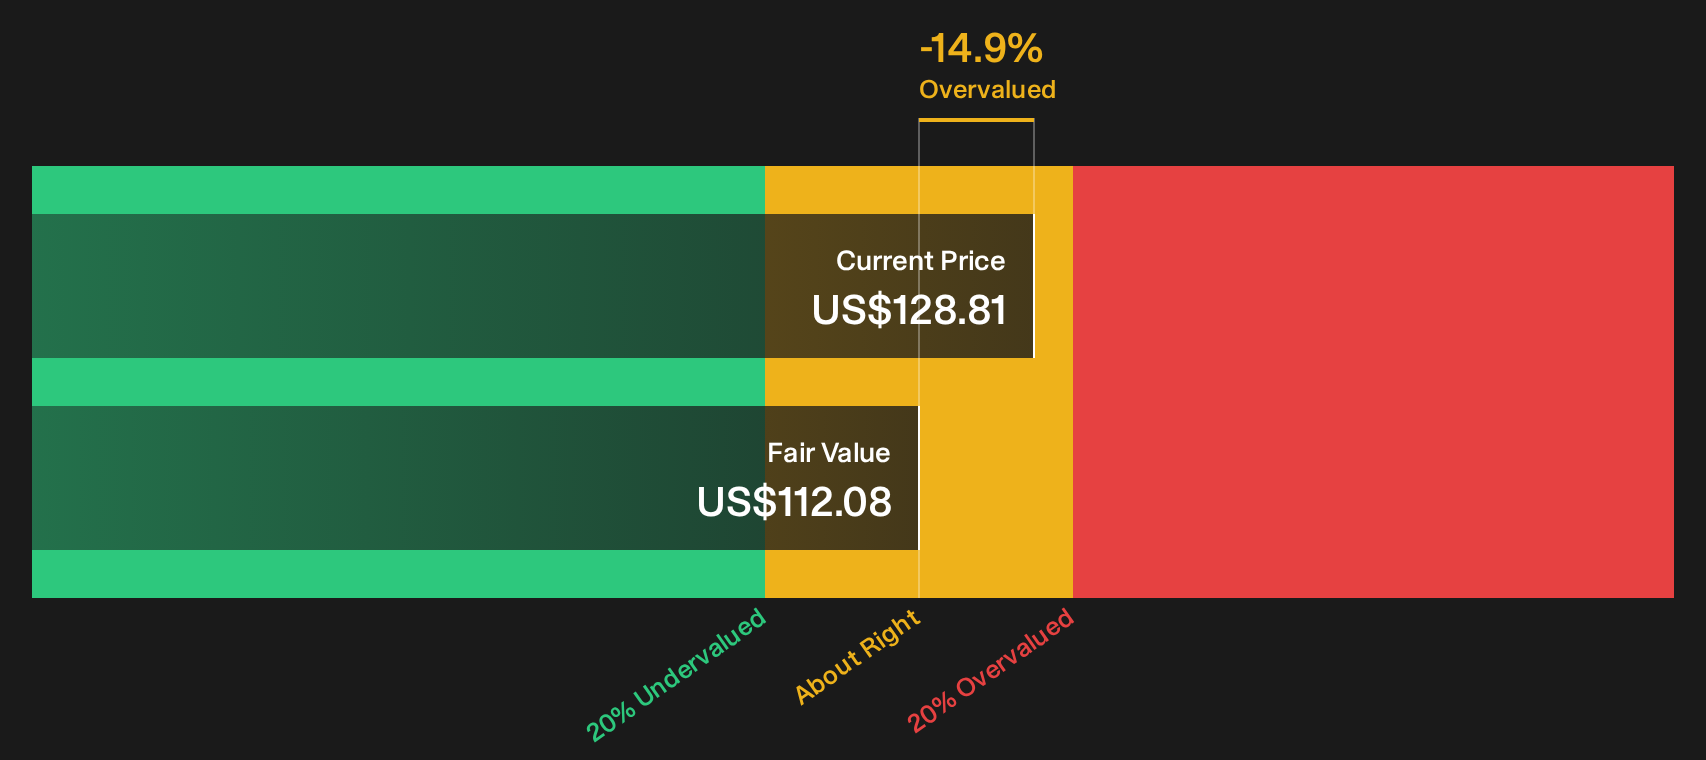
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out IDACORP for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and concern around IDACORP feels familiar, treat it as your cue to move fast and test the data yourself. Weigh the upside case against the red flags by checking the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond IDACORP?
If IDACORP has your attention, do not stop with a single ticker. Broaden your watchlist so you can compare income, quality and potential upside side by side.
- Target stronger income streams by reviewing the 6 dividend fortresses that focus on firms aiming to maintain sizable cash payouts to shareholders.
- Hunt for mispriced opportunities with the 32 high quality undervalued stocks that highlights businesses combining solid fundamentals with potentially attractive entry points.
- Prioritise resilience first through the 30 resilient stocks with low risk scores that filters for companies with steadier profiles and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com