


Copper Rebrand Could Be A Game Changer For McEwen Stock (MUX)
- McEwen has rebranded from McEwen Mining, highlighting a broader mix of producing assets and copper-focused exploration projects across the Americas.
- Increased emphasis on copper exposure and a potential McEwen Copper spin out is sharpening attention on how efficiently operations convert into durable earnings.
- We will now examine how McEwen's refreshed identity and copper-centric portfolio shape the broader investment narrative for the business.
Compare McEwen's copper driven story with a curated 36 elite gold producer stocks that could benefit from similar themes in metal prices and long term demand for hard assets.
McEwen Investment Narrative Recap
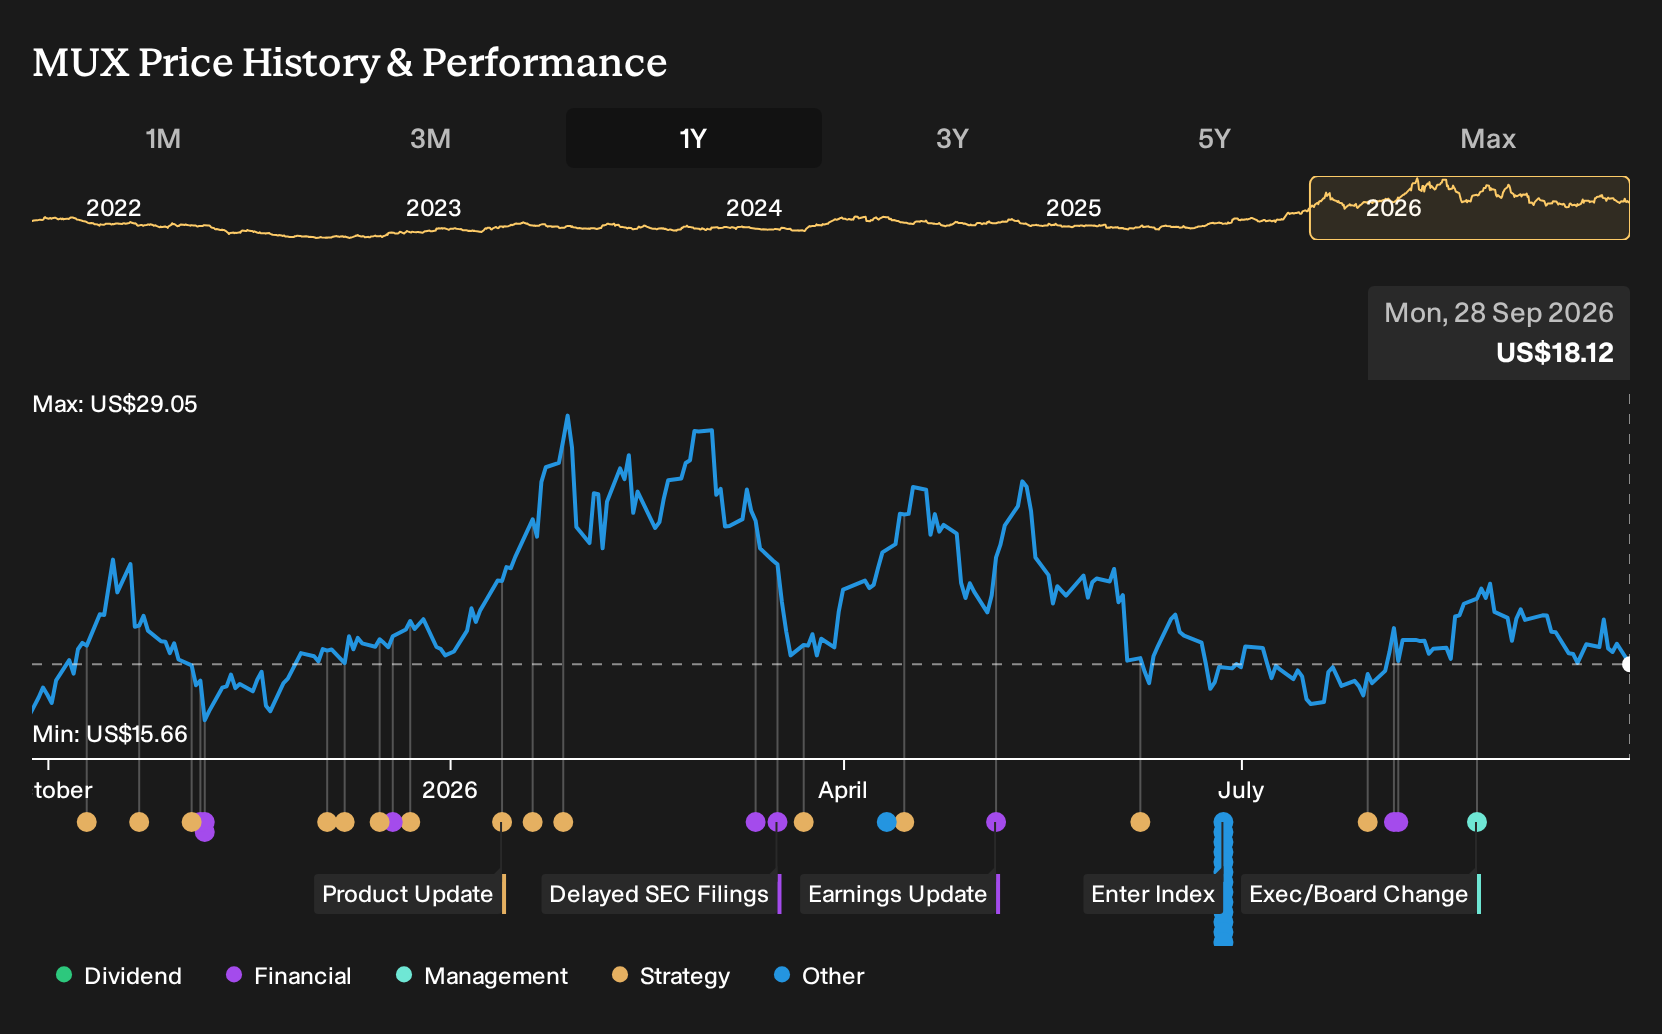
To own McEwen, you need to believe the copper and precious metals portfolio can translate into consistent earnings rather than just asset stories. The recent pullback after a strong multi year run puts more focus on whether existing mines, like Gold Bar and Fox, can keep operations tight on costs and recovery. In the near term, the key swing factor is how efficiently those producing assets sustain cash generation to support project spending.
The biggest operational risk is still execution on large projects such as Los Azules and the Tartan restart, where delays, cost creep, or permitting friction could stretch capital needs. Recent trading volatility does not materially change that picture. It simply sharpens attention on whether management can deliver projects without leaning too hard on fresh equity or expensive debt.
The most relevant recent development for this story is McEwen’s rebrand away from McEwen Mining toward a broader identity that explicitly includes copper. That shift frames the business less as a pure gold and silver producer and more as a diversified metals platform with a flagship growth project in Los Azules.
For you, the important question is execution. Progress on Los Azules, including feasibility work and permitting, will likely sit alongside day to day performance at Gold Bar and Fox as the main catalysts to watch. Any signs of schedule slippage, cost pressure, or extended regulatory timelines would feed directly into that core debate about how durable McEwen’s earnings base really is.
What Analysts Are Building Into The McEwen Story
Consensus estimates sketch a punchy growth arc for McEwen that leans heavily on copper. Analysts are assuming revenue can expand by 38.9% a year over the next three years, supported by higher profit margins as projects mature and operating issues are addressed.
On the earnings line, the same group expects profit to move from $74.1 million today to $350.0 million by 2029. That is an increase of about 4.7x, which is a big step up in absolute dollars and in how efficiently the portfolio would need to turn metal into cash flow.
McEwen's narrative projects $631.8 million revenue and $350.0 million earnings by 2029. This implies 38.9% yearly revenue growth and about a 4.7x earnings increase from $74.1 million.
Those forecasts sit inside a wider set of moving parts. Profit margins are assumed to rise from 31.4% today to 55.4% in three years, while the share count is expected to climb by 7.0% per year over the same period. That combination means any improvement in the headline profit pool has to work hard just to offset the effect of issuing more stock.
The valuation bridge relies on the market applying a lower P/E multiple to a much larger earnings base. Analysts frame their price target around McEwen trading at 8.6x projected 2029 earnings of $350.0 million, compared with 13.7x today and an industry level quoted at 18.0x. For you, the question is not only whether those profit figures feel realistic, but also whether a lower multiple on higher earnings matches your own sense of risk in this copper tilted story.
Uncover why McEwen's fair value indicates a 77% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts treat the McEwen rebrand as a springboard for multiple new mines, not just Los Azules. They were already penciling in revenue of US$577.2 million and earnings of US$126.7 million by 2029, backed by a rich project pipeline. That is far more bullish than consensus and could shift again once this latest news fully filters through.
Explore 5 other McEwen fair value estimates, including one that suggests as much as 2223% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own view.
- A great starting point for your McEwen research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for McEwen. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate McEwen's overall financial health at a glance.
Looking For More Ideas Beyond McEwen?
If the McEwen story has sharpened your thinking about risk, reward, and balance sheets, it can help to compare it with other stocks that fit clear, well defined filters using the Simply Wall St Screener.
- If you want potential mispricings with quality in mind, scan through a 32 high quality undervalued stocks that pairs solid fundamentals with attractive valuations.
- If resilience matters more to you than excitement, review a 30 resilient stocks with low risk scores that focuses on companies with lower overall risk scores.
- If balance sheet strength is your starting point, work through a list of solid balance sheet and fundamentals (25 results) to find businesses with financial structures built to absorb shocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com