


Does Fuel Price Cap Change The Bull Case For Eni Stock?
- Eni introduced a temporary fuel price cap at Enilive stations, setting diesel at €2.19 per liter and petrol at €1.99 to support consumers facing high pump costs.
- The decision to compress near term fuel margins highlights that Eni is willing to trade some downstream profitability for stronger customer loyalty and brand visibility in its retail network.
- We will now look at how Eni's choice to cap pump prices reshapes the broader investment narrative around its downstream business.
Scan how Eni's consumer friendly move compares with other resilient fuel and energy plays by checking out a hand picked set of 198 high quality undervalued stocks.
Eni Investment Narrative Recap
To own Eni, you need to be comfortable with a large integrated energy group that is leaning into LNG, upstream gas and lower carbon fuels while still carrying legacy refining and chemicals. The near term story depends heavily on execution in LNG and biorefining, as well as keeping cash generation steady as traditional oil and gas projects mature.
The Enilive fuel price cap looks small in the context of a group that generated €89.9b in revenue, so it does not materially change the near term drivers. The bigger swing factors remain progress on LNG projects and whether loss making Versalis and capital hungry Plenitude pull harder on group cash flows than expected.
The headline action most closely tied to this is the earlier push to scale Enilive as a separate mobility platform alongside biorefining. Capping pump prices stresses that segment in the short run but also puts more attention on how Enilive and the broader refining and chemicals division can eventually move toward higher quality, lower carbon earnings.
For you as a shareholder, the key question is how this fits with the wider catalyst set that includes LNG growth, restructuring at Versalis and gradual expansion of Plenitude. The retail move may help support fuel volumes and brand reach, while the heavier operational risk still sits in big ticket LNG projects and in the long dated path to cash flow neutrality for renewables.
What The Forecasts Say About Eni
Eni's narrative projects €86.6b revenue and €5.9b earnings by 2029. This assumes revenue declines by 1.2% per year and an earnings increase of roughly €0.1b from €5.8b today.
Uncover why Eni's fair value indicates a 5% potential upside to its current price that may not last much longer.
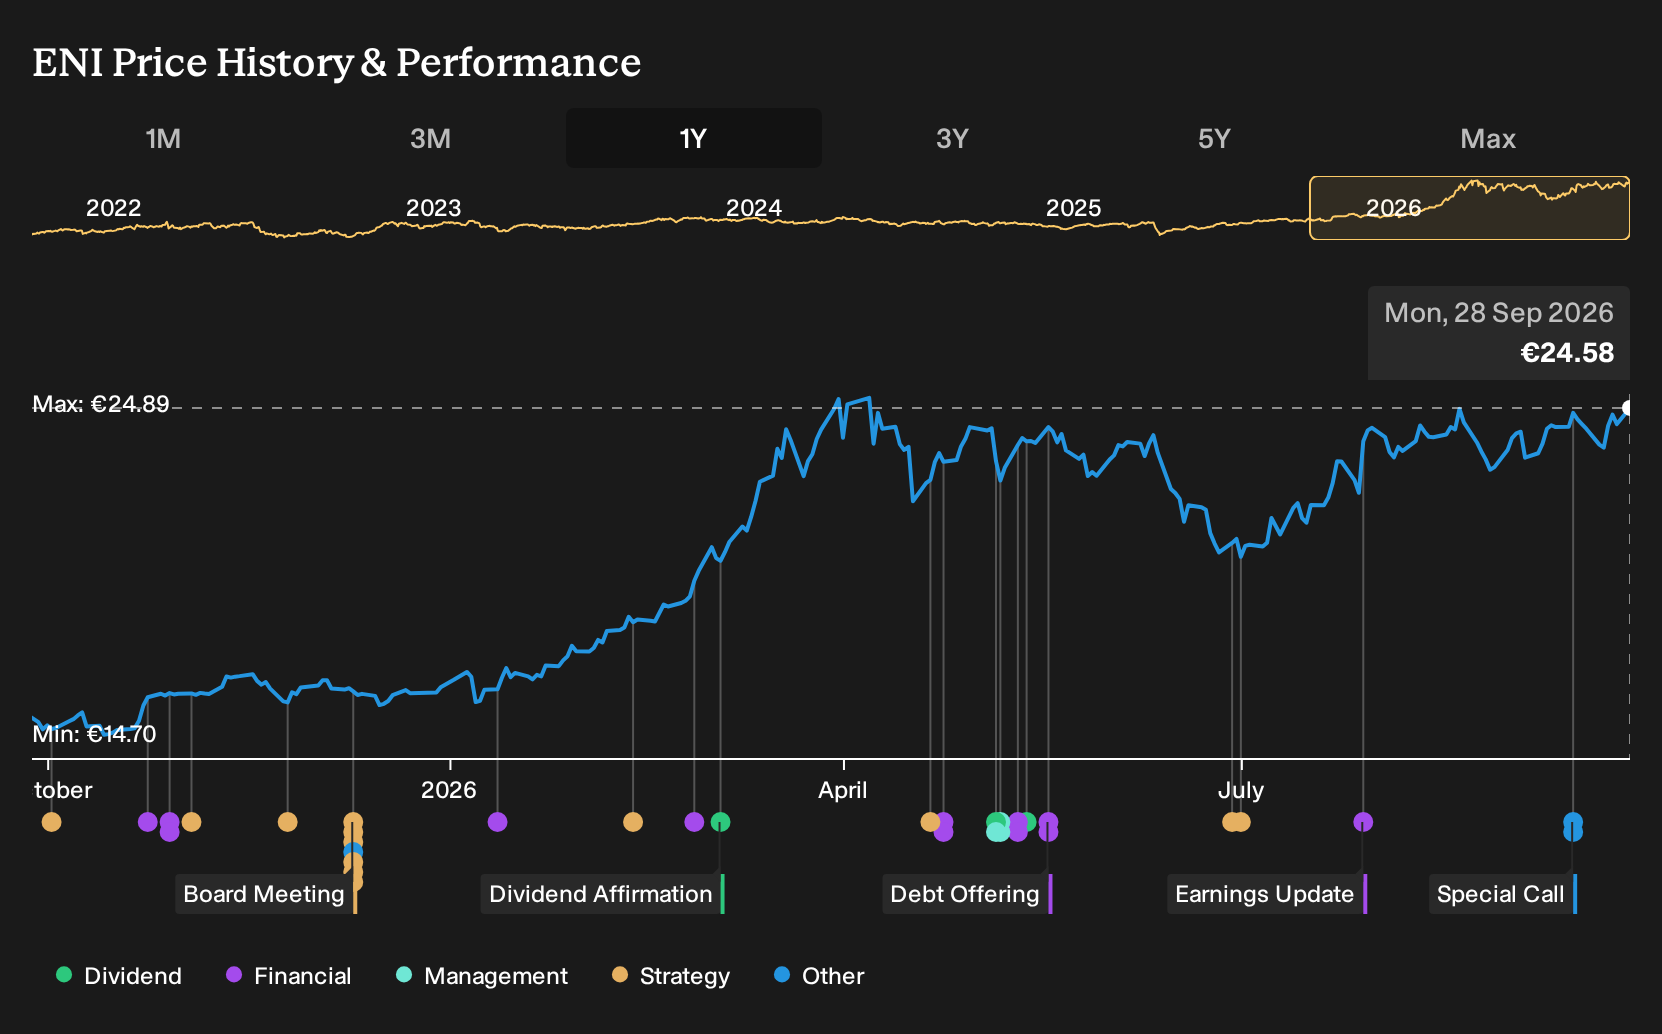
Exploring Other Perspectives
You are seeing one clear point of tension. Consensus leans on LNG and lower carbon projects, while the most bearish analysts worry about Eni’s heavy push into capital hungry gas and data center backed power. Those lower estimates assume revenue closer to €64.1b and earnings near €4.5b by 2029. Before this fuel price cap, that group already saw much tougher economics, so this move could easily shift their story again. Exploring both sets of assumptions helps you judge where you personally feel comfortable on Eni’s risk and reward.
Explore 3 other Eni fair value estimates, including one that suggests it could be worth just €25.85.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Eni research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Eni. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eni's overall financial health at a glance.
Looking For More Investment Ideas Beyond Eni?
If the Eni story has sharpened your thinking about risk, return and balance sheet strength, it can help to line it up against other opportunities using the Simply Wall St Screener. You can filter by quality, income profile or downside risk and quickly see which stocks deserve a closer look.
- For investors who care most about financial resilience, start with a list of solid balance sheet and fundamentals (203 results) that aim to keep funding risk in check even when conditions turn harder.
- If lower volatility and capital protection sit higher on your list, review a curated group of 223 resilient stocks with low risk scores that score well on stability metrics.
- When you want to get ahead of the crowd, scan a focused set of 618 high quality undiscovered gems that pair solid fundamentals with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com