


Unusual Machines (UMAC) On Defense Demand And Factory Expansion What Is The Valuation Story
Unusual Machines (UMAC) is back in focus after rapid Q2 growth acceleration tied to Enterprise demand and U.S. defense programs, with management increasing manufacturing and supply chain capacity in anticipation of future orders through 2027.
Over the past year, Unusual Machines has seen strong momentum build, with a year-to-date share price return of 76.57% and a 1-year total shareholder return of 73.62%, even as the 7-day and 1-day share price moves have been slightly negative.
Scan for other drone and defense suppliers showing similar momentum to Unusual Machines by reviewing the hand picked 92 robotics and automation stocks, which are building out critical unmanned and automation capabilities.
After a 76.57% year to date surge and a recent pause, Unusual Machines now trades well below the average analyst target. So where does a reasonable fair value range actually cluster for this stock today?
Most Popular Narrative: 39% Undervalued
Analysts following Unusual Machines see a fair value of $39.00, well above the last close at $23.96, and link that gap directly to expectations around U.S. drone demand, rising margins, and government-backed capacity buildouts.
Significant government policy changes and increasing U.S. federal investment in drone technology are set to unlock material new demand for domestically sourced drone components. Unusual Machines' expectation of imminent and sizable government orders, including multiple customers vying for contracts like the $500 million PBAS program, positions the company to capture a large share of a rapidly expanding market, which is likely to drive sequential revenue growth over the next several quarters.
See why 40 investors see Unusual Machines as 39% undervalued.
Result: Fair Value of $39.00 (UNDERVALUED)
Still, the upbeat Unusual Machines story leans heavily on large U.S. government contracts and smooth factory ramp up; any funding shift or execution slip could quickly test that thesis.
Find out about the key risks to this Unusual Machines narrative.
Another View on Unusual Machines' Valuation
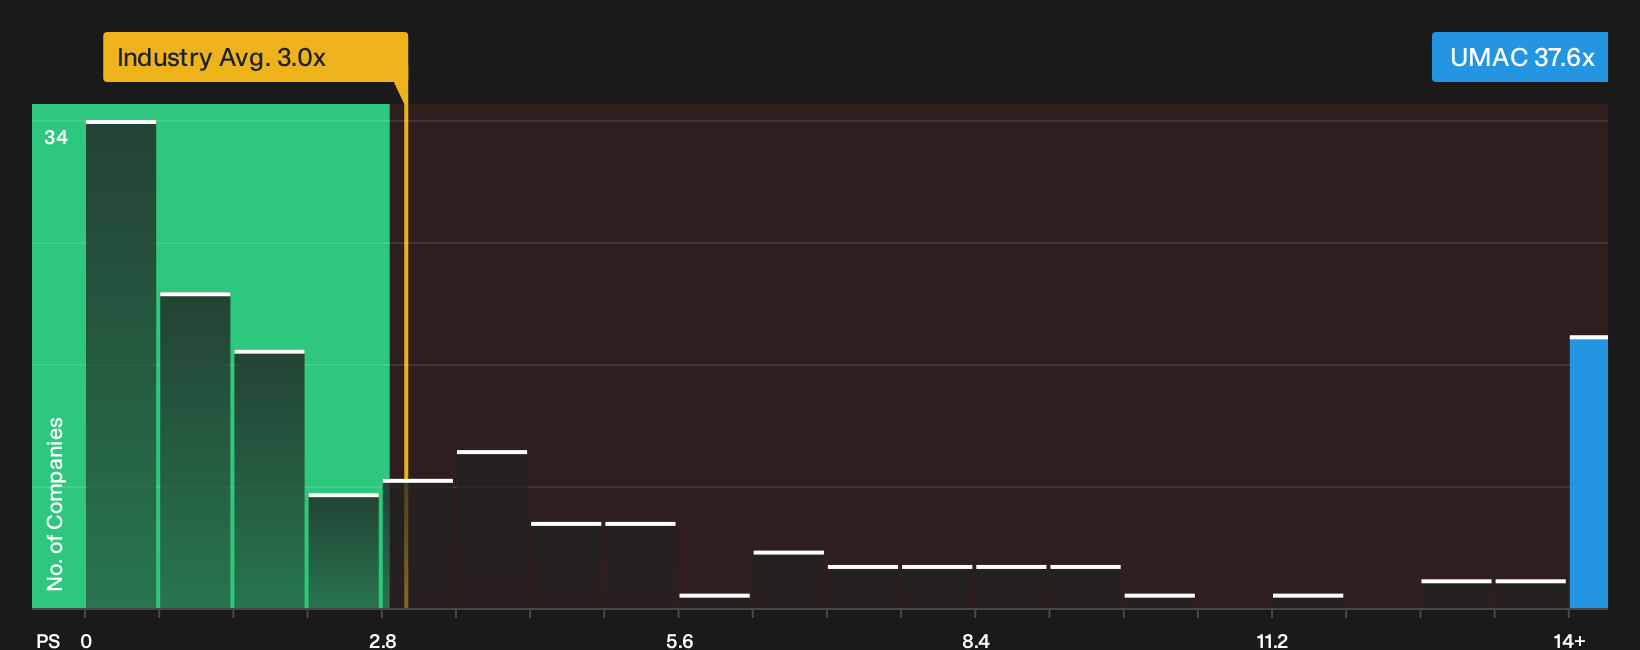
The fair value story around Unusual Machines changes quickly once the focus shifts from analyst targets to current pricing on sales. The stock trades on a P/S ratio of 37.6x, while the fair ratio is 5.8x, the US Electronic industry sits at 3x, and peers average 18.3x. That wide gap points to a valuation that already bakes in a lot of success and leaves less room for error if growth or margins come in below expectations. How comfortable are you paying such a premium for that upside narrative?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Unusual Machines so far. If both the bullish story and the premium valuation give you pause, consider acting quickly and pressure testing the thesis yourself by weighing 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Unusual Machines?
If Unusual Machines has sharpened your interest, do not stop here. Broader opportunities exist, and the right shortlist can seriously improve your next move.
- Target resilient balance sheets and steady fundamentals by reviewing the list of solid balance sheet and fundamentals (25 results) that might better match your risk tolerance.
- Hunt for quality at a discount and compare Unusual Machines against a broader pool of potential bargains with the 32 high quality undervalued stocks before prices move away from you.
- Build a watchlist of potential future leaders by scanning the 16 high quality undiscovered gems that many investors may be overlooking right now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com