


Fortune Brands (FBIN) Could Be 33% Undervalued As Governance Questions Stir Debate
Fortune Brands Innovations (FBIN) is back in focus after a shareholder investigation by Purcell & Lefkowitz LLP raised governance questions, just as some investors argue the stock trades below its estimated cash flow value.
Recent trading tells you sentiment has cooled. The share price is down 15.5% over the past 30 days and about 30% over 90 days. The 1 year total shareholder return has declined roughly 26%, pointing to fading momentum even as some investors focus on a possible valuation gap.
Compare this governance overhang and valuation debate at Fortune Brands Innovations with a curated set of potential value opportunities in our 32 high quality undervalued stocks screen.
Fortune Brands Innovations now sits at a price that some investors read as fresh opportunity, while others see it as evidence that most of the rebound is already gone. Which camp does the current valuation actually support?
Most Popular Narrative: 33% Undervalued
On the most followed narrative, Fortune Brands Innovations screens as undervalued, with an implied fair value of $57.15 against a last close of $38.43, and that gap is tied directly to how future cash flows and margins are expected to evolve under the current business plan.
The company's strategic investments in digital products, such as connected water management, smart locks, and a new subscription-based recurring revenue model, are supporting a transition toward higher-margin, tech-enabled solutions, contributing to both improved net margins and earnings growth. Market share gains and long-term contracts in Water (notably with major builders and retail partners), together with strong brand recognition among professional users, are described as laying the groundwork for sustainable above-market revenue and share growth.
See why 3 investors see Fortune Brands Innovations as 33% undervalued.
Result: Fair Value of $57.15 (UNDERVALUED)
Still, the Fortune Brands Innovations story can break the wrong way if U.S. housing stays weak or connected-product adoption continues to lag internal expectations.
Find out about the key risks to this Fortune Brands Innovations narrative.
Another View: What Multiples Say About Fortune Brands Innovations
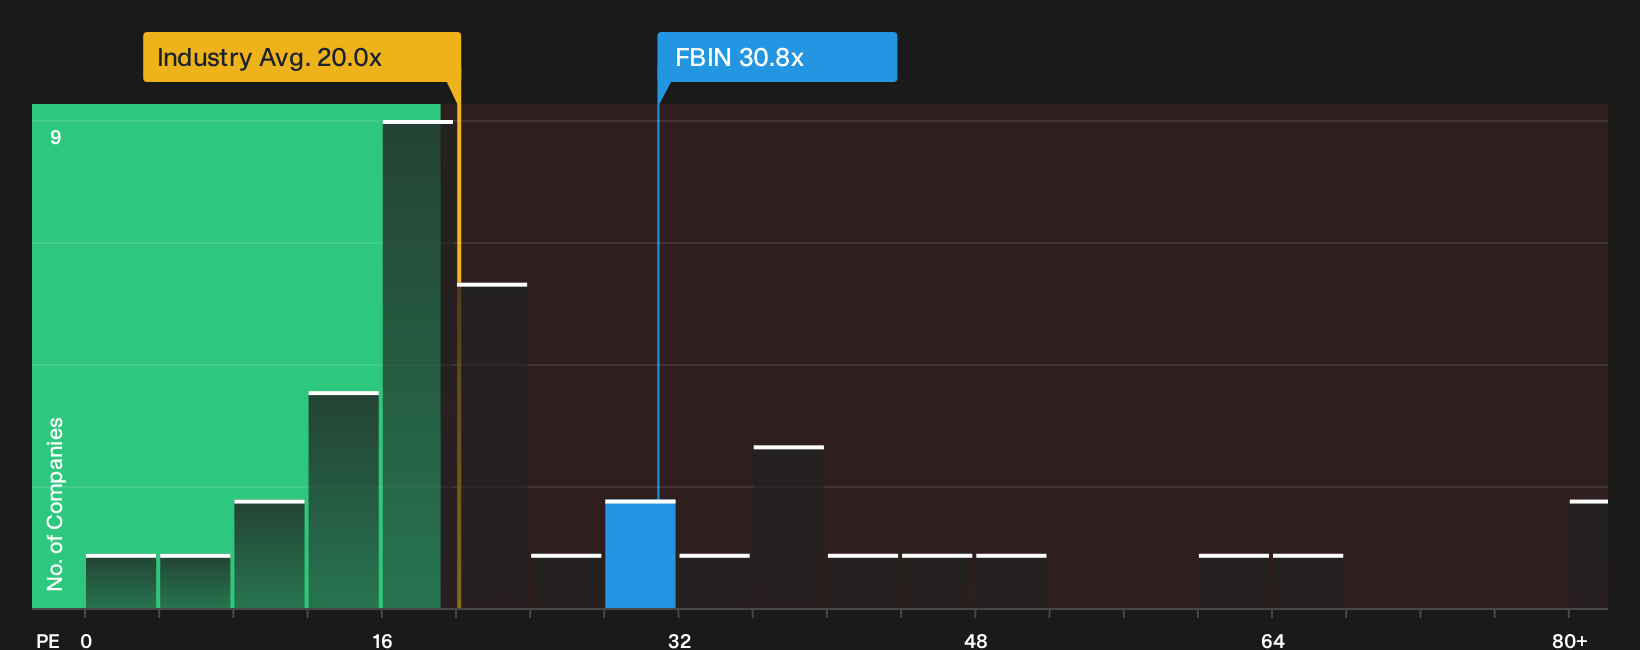
That 33% undervaluation story leans heavily on future cash flows. Looking at the current P/E instead, Fortune Brands Innovations trades at 30.8x earnings. The broader US Building industry is at 20.1x, while direct peers are nearer 37.3x, and the fair ratio is estimated at 35.4x.
This mix points to a stock that appears expensive relative to the sector, but cheaper than close comparables and below the level where the fair ratio indicates the market might eventually settle. For investors, that split raises a simple question: is this a value gap opening, or a potential warning sign on earnings risk?
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Fortune Brands Innovations is clearly split right now, and the market is moving. Check the underlying numbers, weigh both the risks and the upside potential, then decide where you stand by reviewing the 3 key rewards and 4 important warning signs.
Looking for more ideas beyond Fortune Brands Innovations?
If Fortune Brands Innovations has you rethinking valuations, do not stop here. The right watchlist today can shape your returns for years.
- Target reliable income and potential resilience by zeroing in on companies with robust payouts and balance sheets through the 6 dividend fortresses.
- Hunt for mispriced opportunities where quality and valuation intersect by scanning the 32 high quality undervalued stocks that surfaces candidates for deeper research.
- Spot financially sound businesses that may be flying under the radar by reviewing the list of solid balance sheet and fundamentals (25 results) before the crowd catches on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com