


ABN AMRO Bank (ENXTAM:ABN) Heads To CEO Conference As Valuation Views Split
ABN AMRO Bank (ENXTAM:ABN) heads into the Bank of America 31st Annual Financials CEO Conference in London on 24 September 2026, with CFO Ferdinand G. Vaandrager set to outline the bank’s current positioning for investors.
Recent trading has been strong for ABN AMRO Bank, with the share price at €43.74 and a year to date share price return of 44.64%. The 1 year total shareholder return of 68.92% and very large 5 year total shareholder return suggest momentum has been building rather than fading.
Scan other banking stocks showing similar momentum and balance sheet strength with our curated list of list of solid balance sheet and fundamentals (203 results) to compare against ABN AMRO Bank’s recent run.
After a 68.92% 1 year total return and a share price near the latest analyst target, ABN AMRO Bank now raises a sharper question. Is that 42% intrinsic discount pointing to more runway, or just marking what has already played out in the price?
Most Popular Narrative: 1% Overvalued
The most followed narrative on ABN AMRO Bank pegs fair value at about €43.18, just below the latest close at €43.74. This frames today’s pricing as tight against long term assumptions built on a 6.41% discount rate.
Rapid acceleration of digital capabilities, demonstrated by the swift launch of BUUT (a neobank for Gen Z) and significant modernization of banking applications, positions ABN AMRO to capture new, younger demographics and achieve further cost efficiencies supporting long term cost to income improvement and potential net margin expansion.
See why 55 investors see ABN AMRO Bank as 1% overvalued.
Result: Fair Value of €43.18 (OVERVALUED)
Still, the ABN AMRO Bank story can be knocked off course if higher regulatory capital demands or persistent compliance costs squeeze returns more than analysts currently allow for.
Find out about the key risks to this ABN AMRO Bank narrative.
Another View On ABN AMRO Bank’s Value
The SWS DCF model tells a very different story for ABN AMRO Bank. On that framework, the shares at €43.74 are trading at a 42.5% discount to an estimated future cash flow value of €76.04. This frames current pricing as cautious rather than stretched. That gap raises a simple question. Is the market too conservative about how much cash this bank can return over time, or are the cash flow assumptions too generous?
Look into how the SWS DCF model arrives at its fair value.
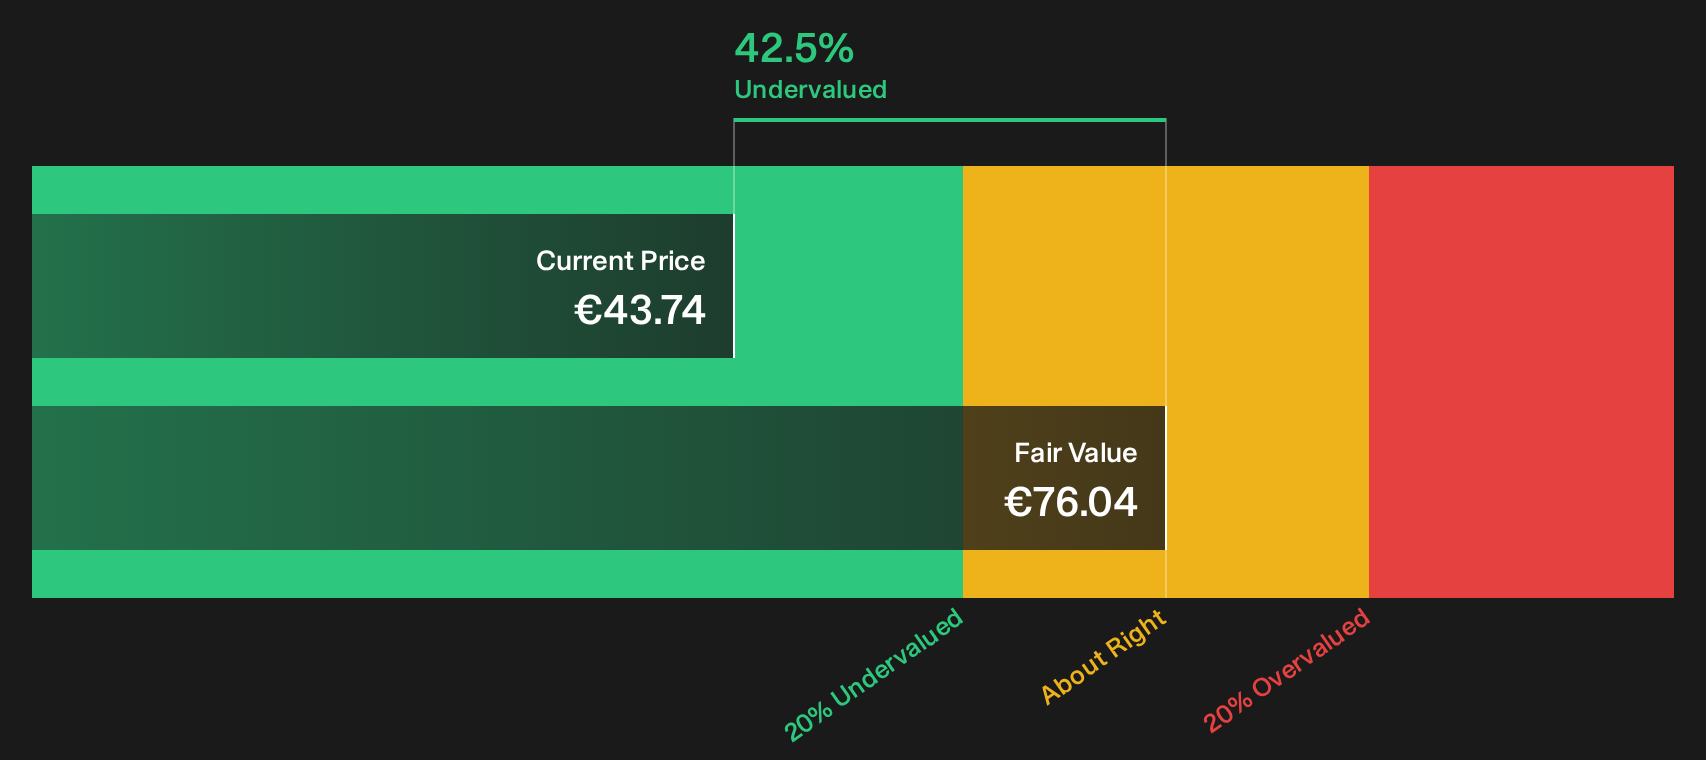
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ABN AMRO Bank for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 198 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around ABN AMRO Bank’s value story make this a moment to look directly at the numbers yourself and move quickly while the picture is fresh. To weigh both sides of that debate, walk through the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond ABN AMRO Bank?
If the ABN AMRO Bank setup is on your radar, do not stop there. Use the screener to line up alternatives while this conference spotlight is still fresh.
- Target steadier journeys by scanning 223 resilient stocks with low risk scores that aim to keep volatility in check while still offering room for thoughtful investors to stay engaged.
- Hunt for pricing gaps by reviewing 198 high quality undervalued stocks where fundamentals and current market quotes appear out of sync and may reward deeper research.
- Stack potential income streams by assessing 165 dividend fortresses that combine higher yields with business profiles built around regular cash returns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com