


AST SpaceMobile (ASTS) Stock Looks Stretched As Its 15x Run Continues
AST SpaceMobile has delivered an extremely strong multiyear share-price run, which puts a lot of focus on whether the current US$61.00 level is supported by what sits on its balance sheet. With that kind of performance now meeting fresh headlines and legal scrutiny, the question is how much of the story is already embedded in the book value per share.
- Over the past 3 years the stock has returned a very large gain of roughly 15x. This makes the gap or alignment with its underlying book value a key issue for anyone thinking about valuation today.
- Recent news around a planned space based cellular network launch, large customer backlog, and securities class action lawsuits all feed into expectations for future capital needs and balance sheet risk. These factors can matter a lot when you are judging a company against its book value.
- There is a second opinion on AST SpaceMobile worth weighing. See what analysts think AST SpaceMobile's shares could be worth.
The issue now is whether AST SpaceMobile's current share price can be explained by its book value once you stack it up against the industry average.
If you are questioning whether AST SpaceMobile's 3 year, roughly 15x run still lines up with its book value, it can help to compare that puzzle with 32 high quality undervalued stocks
Does AST SpaceMobile Look Pricey on Book Value?
P/B fits AST SpaceMobile because investors are closely watching the strength of its equity base as it funds a capital heavy satellite build out.
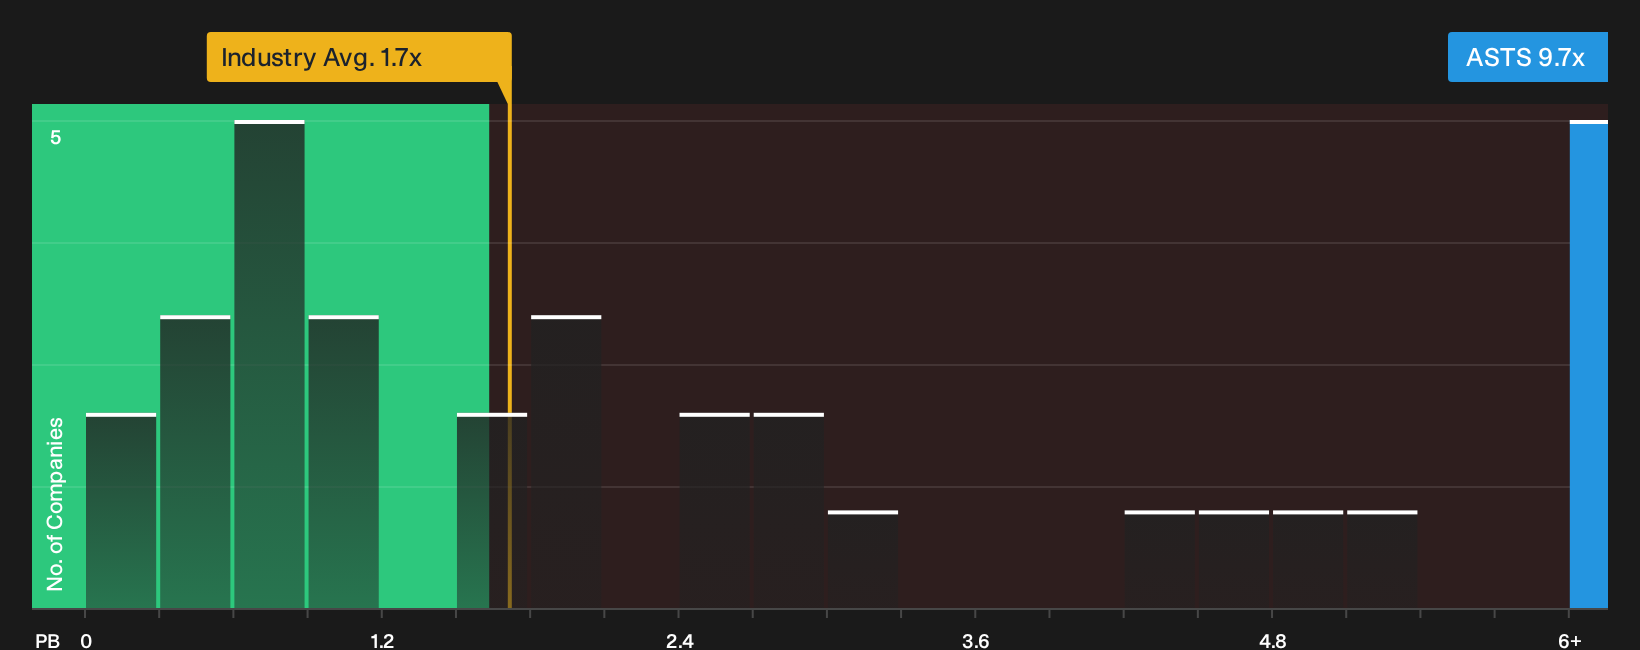
The stock currently trades around 9.7x P/B, compared with a Telecom industry average near 1.7x and a peer group around 13.3x. Pricing at this level puts AST SpaceMobile at a large premium to the broad sector, while still below the narrower peer set that investors use for high growth satellite and connectivity plays, which lines up with a verdict of overvalued on this metric. Because the class action lawsuits allege issues around capital requirements and dilution, such a rich P/B multiple means you are paying a high price for each dollar of book equity despite those highlighted risks. Explore the numbers behind AST SpaceMobile's P/B valuation.
The AST SpaceMobile Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the book value puzzle leaves off for AST SpaceMobile by spelling out which mix of future growth, profitability and earnings would need to play out for the share price to sit meaningfully above or below where it trades today on the Community page. Each narrative treats AST SpaceMobile's implied worth as a clear, testable idea about how the business might develop over time rather than a one off snapshot.
Community views on AST SpaceMobile split between a moonshot buildout story and a stock that some holders already see as priced for perfection.
Bull case: 64% undervalued
"AST SpaceMobile is one of the most ambitious infrastructure stories in the market, the company is trying to build a space-based cellular broadband network..."
Discover why this Narrative puts AST SpaceMobile at 64% undervalued.
Bear case: 52% overvalued
"At $90.94, ASTS is a victim of its own success, priced for a flawless future that ignores a $1.2B annual burn and a newly aggressive Amazon..."
Explore why this Narrative puts AST SpaceMobile at 52% overvalued.
AST SpaceMobile's valuation still hinges on one unanswered question
Behind AST SpaceMobile's headline story, the people choosing where each new dollar goes and how they are rewarded for it can tilt the whole risk and reward profile. See who runs AST SpaceMobile and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com