


Northwest Natural Holding (NWN) Has Slipped Recently, Is The Stock Cheap Enough Now?
Northwest Natural Holding (NWN) has drawn fresh attention after recent price weakness, with the share price down about 5% over the past month and roughly 4% over the past 3 months.
That recent slide comes after a period in which Northwest Natural Holding’s short-term share price momentum has faded, even as longer-term total shareholder returns have been stronger, with the 1-year total shareholder return at 8.75% and the 3-year total shareholder return at 45.63%.
Scan beyond Northwest Natural Holding and identify other regulated utilities experiencing similar price moves with our hand-picked 30 resilient stocks with low risk scores.
For Northwest Natural Holding, a 5% pullback sits alongside multiyear gains and a discounted gap to analyst targets. Does that set up a reasonable entry now, or argue for patience and a lower price first?
Most Popular Narrative: 19% Undervalued
On the most followed view, Northwest Natural Holding’s fair value of $57.50 sits well above the latest $46.80 close. This puts the recent pullback against a still supportive long term valuation story that depends heavily on future earnings delivery.
Ongoing investments in infrastructure modernization and system upgrades, combined with supportive regulatory outcomes (recent rate increase and higher allowed ROE), are likely to improve net margins, operating efficiency, and future earnings reliability.
See why 7 investors see Northwest Natural Holding as 19% undervalued.
Result: Fair Value of $57.50 (UNDERVALUED)
Still, Northwest Natural Holding relies heavily on supportive regulators and on Texas construction trends, so any tougher rate decisions or a housing slowdown could quickly challenge that undervalued narrative.
Find out about the key risks to this Northwest Natural Holding narrative.
Another View: What Multiples Say About Northwest Natural Holding
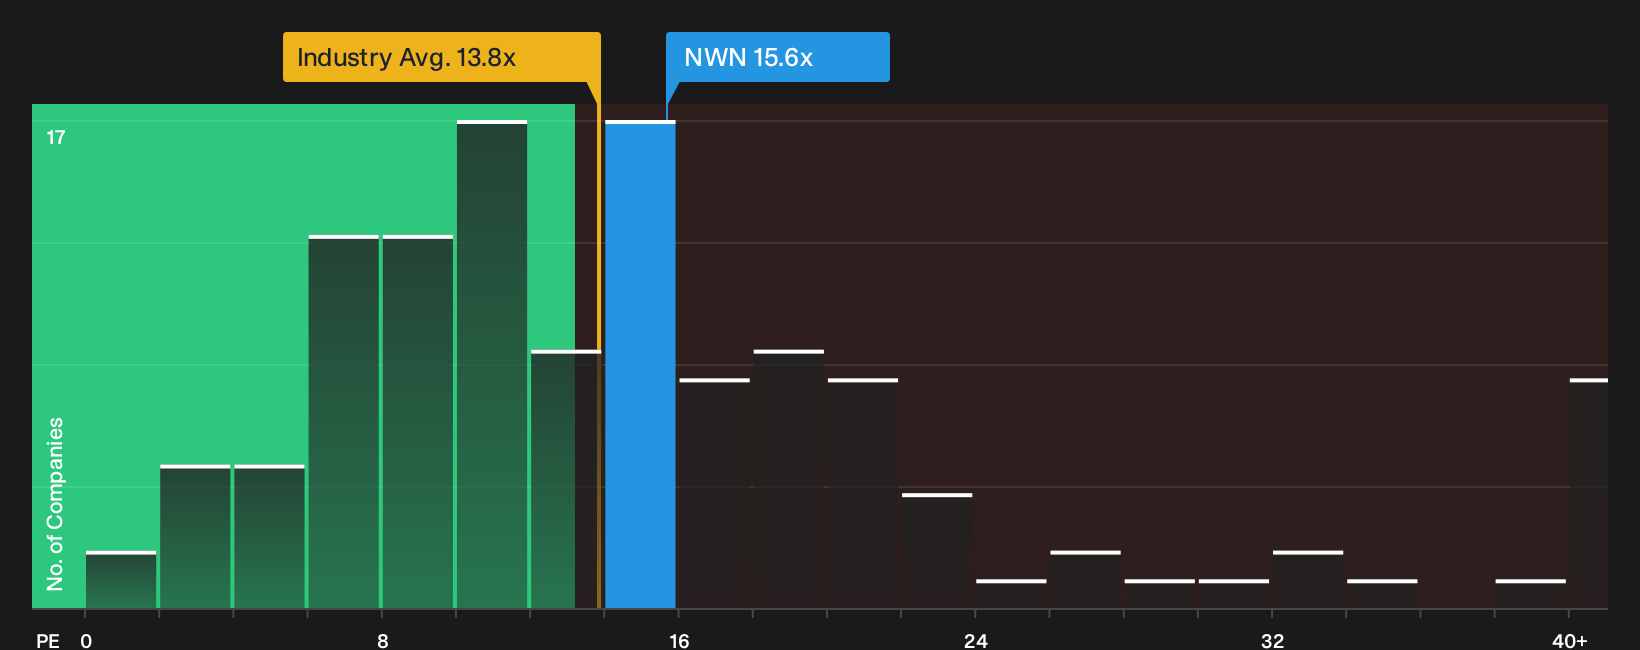
There is a different read on Northwest Natural Holding when you look at simple P/E math instead of analyst targets. The stock trades on a 15.6x P/E, while the global gas utilities group sits at 13.8x and direct peers at 15.3x. That points to a modest premium rather than a clear bargain, even though the fair ratio of 18.6x suggests the market could move higher over time. For an investor weighing entry points, this premium can be evaluated as either a reasonable price for quality or as a sign to seek a wider margin of safety.
For a closer look at how this earnings multiple compares against the fair ratio and sector peers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Northwest Natural Holding’s valuation and risk can pull you in both directions, so move quickly, review the numbers yourself, and weigh the 4 key rewards and 2 important warning signs.
Ready for more ideas beyond Northwest Natural Holding?
Do not stop with Northwest Natural Holding. Use the Simply Wall St screener to uncover fresh, data driven opportunities that match your risk comfort and return goals.
- Target potential bargains by scanning a curated set of undervalued businesses through the 32 high quality undervalued stocks.
- Strengthen your income stream by reviewing a focused group of higher yielding candidates using the 6 dividend fortresses.
- Dial back portfolio risk by zeroing in on companies with sturdier finances via the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com