


3 Undervalued Small Caps In Global With Recent Insider Action
In recent weeks, global markets have experienced a mixed bag of economic signals, with the Russell 2000 Index pulling back amid inflation concerns and fluctuating interest rates. As small-cap stocks navigate this volatile landscape, investors often seek opportunities in companies that demonstrate strong fundamentals and potential for growth despite broader market challenges.
Top 10 Undervalued Small Caps With Insider Buying Globally
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Q Technology (Group) | 3.5x | 0.2x | 43.51% | ★★★★★☆ |
| China Aircraft Leasing Group Holdings | 7.2x | 1.0x | 36.90% | ★★★★★☆ |
| Transcontinental | 2.5x | 0.2x | -102.99% | ★★★★☆☆ |
| Franchise Brands | 27.9x | 2.1x | 46.51% | ★★★★☆☆ |
| Pizza Pizza Royalty | 11.7x | 9.0x | 42.05% | ★★★★☆☆ |
| Trifast | NA | 0.6x | 10.03% | ★★★★☆☆ |
| Saniona | 7.1x | 3.1x | 33.48% | ★★★★☆☆ |
| Linc | 12.2x | 12.6x | 33.99% | ★★★★☆☆ |
| Yellow Pages | 8.6x | 0.9x | 26.66% | ★★★☆☆☆ |
| Coveo Solutions | NA | 1.9x | -23.06% | ★★★☆☆☆ |
Below we spotlight a couple of our favorites from our exclusive screener.
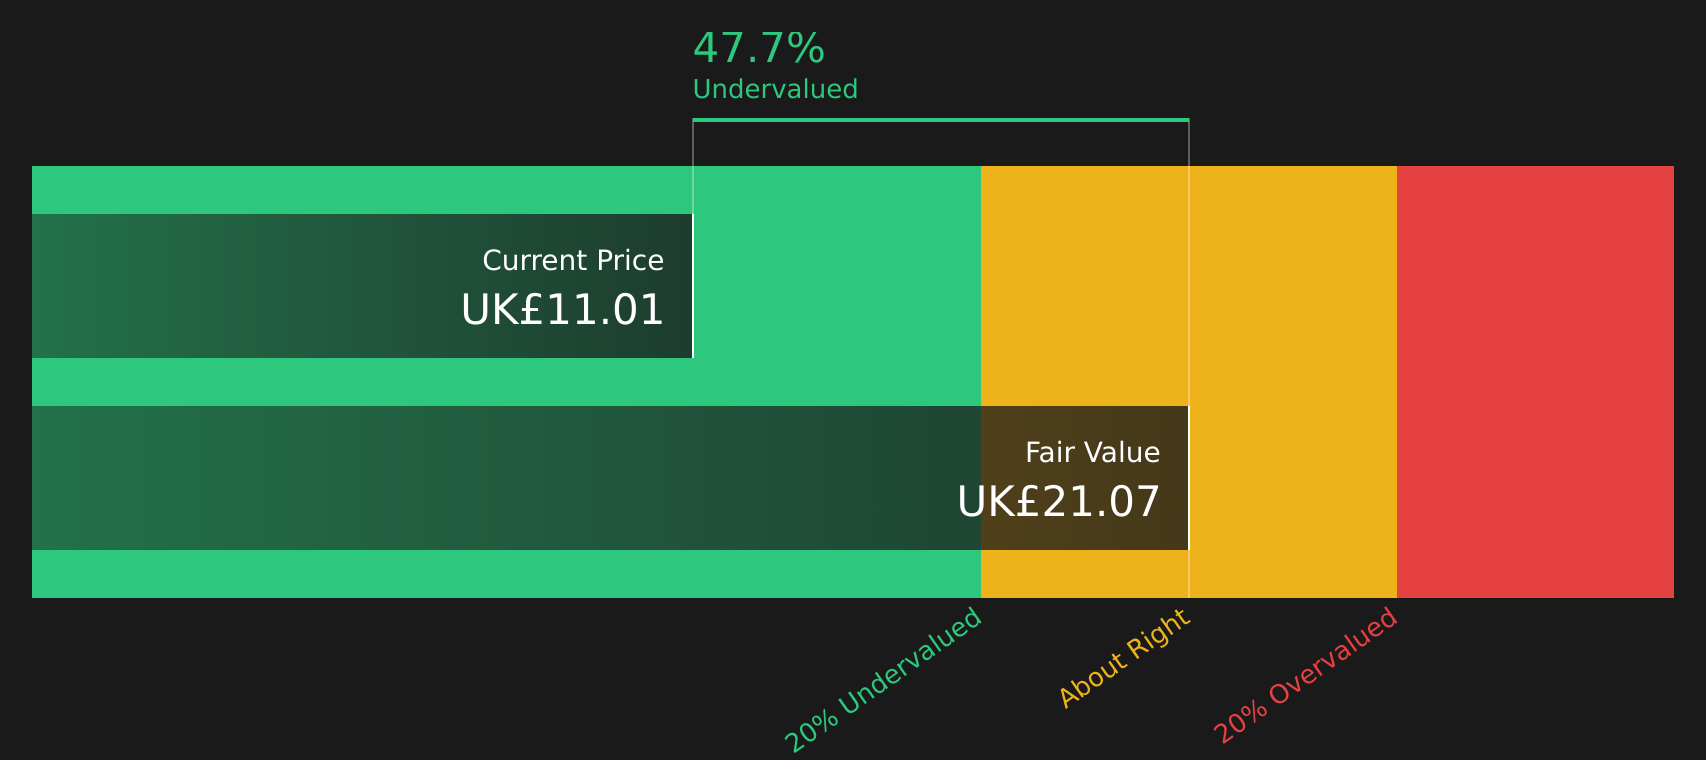
Wizz Air Holdings (LSE:WIZZ)
Simply Wall St Value Rating: ★★★★★☆
Overview: Wizz Air Holdings is a European low-cost airline focused on providing affordable air travel, with a market capitalization of approximately €3.65 billion.
Operations: Wizz Air Holdings generates revenue primarily from its airline operations, with a recent gross profit margin of 18.84%. The company incurs significant costs in cost of goods sold (COGS) and operating expenses, with depreciation and amortization being notable components.
PE: -5.3x
Wizz Air Holdings, a smaller player in the airline sector, shows potential for growth despite recent challenges. The company reported a net loss of €198.6 million in Q1 2026 but saw significant passenger growth with 21.2 million carried, up from 17 million the previous year. Capacity also increased by over 4 billion seat kilometers year-over-year. Although reliant on external borrowing, insider confidence is evident through share purchases earlier this year, suggesting optimism about future profitability and strategic initiatives discussed at their recent Analyst Day on September 17th.
- Get an in-depth perspective on Wizz Air Holdings' performance by reading our valuation report here.
Assess Wizz Air Holdings' past performance with our detailed historical performance reports.
Aztech Global (SGX:8AZ)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Aztech Global is a technology company primarily engaged in manufacturing and distributing electronic products, with a market cap of approximately S$1.14 billion.
Operations: Aztech Global generates revenue primarily from its manufacturing and distribution segments, with the latter contributing SGD 405.05 million and the former SGD 371.39 million. The company's net income margin has shown variability, reaching a high of 11.67% in recent periods, reflecting fluctuations in profitability over time.
PE: 12.1x
Aztech Global, a smaller company in its industry, recently saw insider confidence with a purchase of 100,000 shares by an individual for S$71,500. Despite earnings and sales declining in the first half of 2026 compared to last year—sales fell from S$185.42 million to S$151.36 million and net income dropped from S$16.08 million to S$9.37 million—the company's forecasted annual earnings growth of 6.13% suggests potential for future improvement amidst current challenges like reduced dividend payouts and reliance on external borrowing for funding.

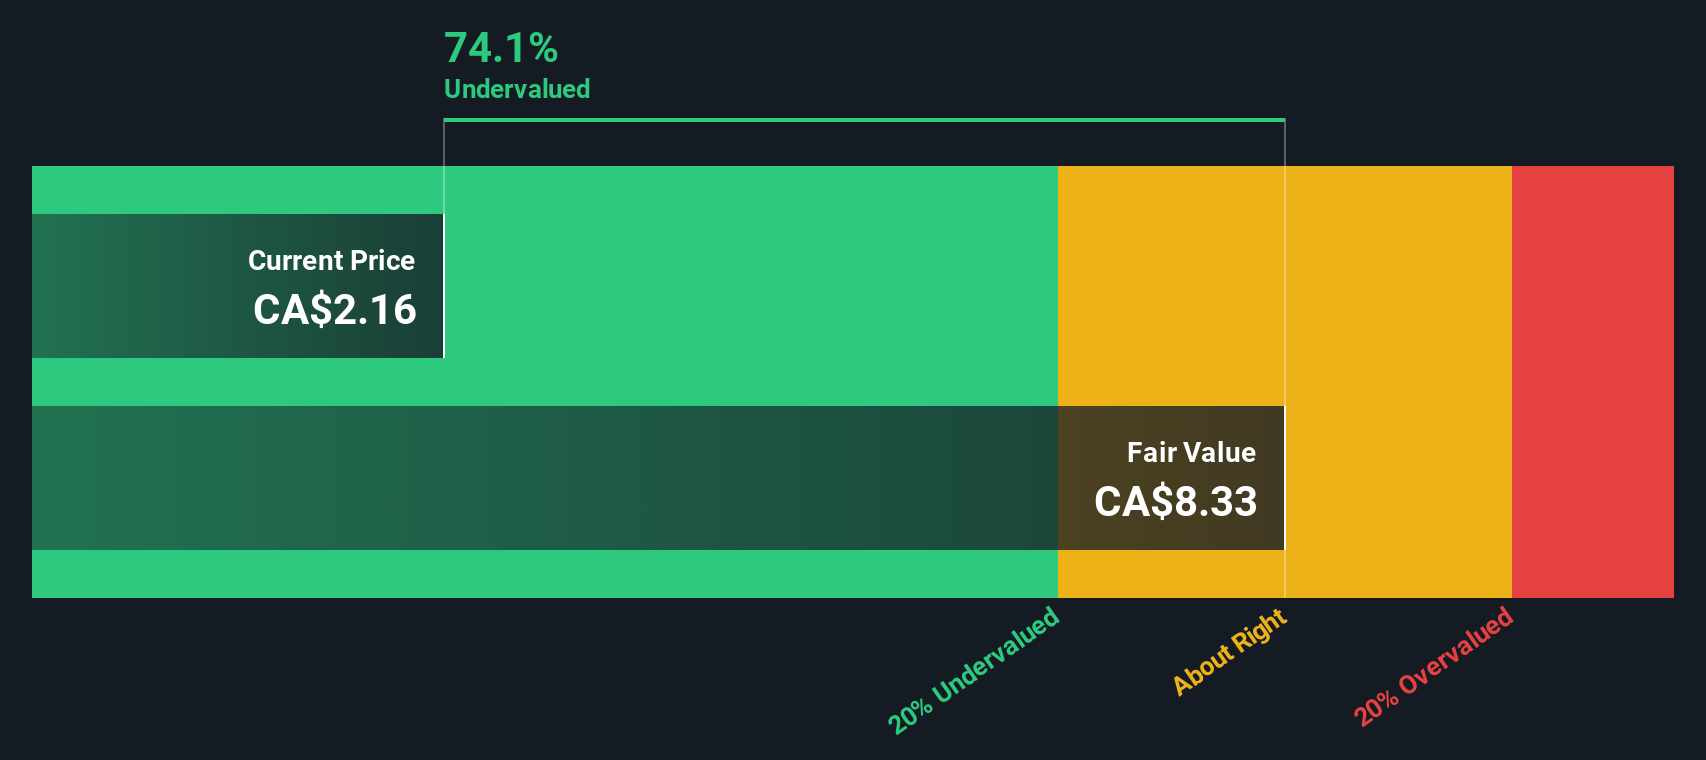
Ur-Energy (TSX:URE)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Ur-Energy is a mining company focused on uranium production and development, with a market capitalization of approximately CAD $0.33 billion.
Operations: The company generates revenue primarily from the metals and mining sector, with a recent quarterly revenue of $35.08 million. Its cost of goods sold (COGS) significantly exceeds its revenue, leading to negative gross profit margins, such as -1.64%. Operating expenses and non-operating expenses further contribute to net losses, with a net income margin of -2.52% in the latest quarter.
PE: -5.1x
Ur-Energy, a uranium producer with operations in Wyoming, recently began shipping from its Shirley Basin mine to the Lost Creek processing plant. Despite reporting a net loss of US$16.69 million for Q2 2026, sales increased to US$14.37 million from the previous year. The company is positioned for growth with plans to ramp up production and expand operations, though it faces financial constraints with less than one year of cash runway and reliance on external borrowing. Insider confidence is evident as insiders have been purchasing shares over recent months, signaling potential optimism about future prospects despite current challenges.
- Unlock comprehensive insights into our analysis of Ur-Energy stock in this valuation report.
Understand Ur-Energy's track record by examining our Past report.
Where To Now?
- Navigate through the entire inventory of 120 Undervalued Global Small Caps With Insider Buying here.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Ready For A Different Approach?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com