


Learn Why The Bull Case For Truist Financial Stock Could Change Following Earnings Beat
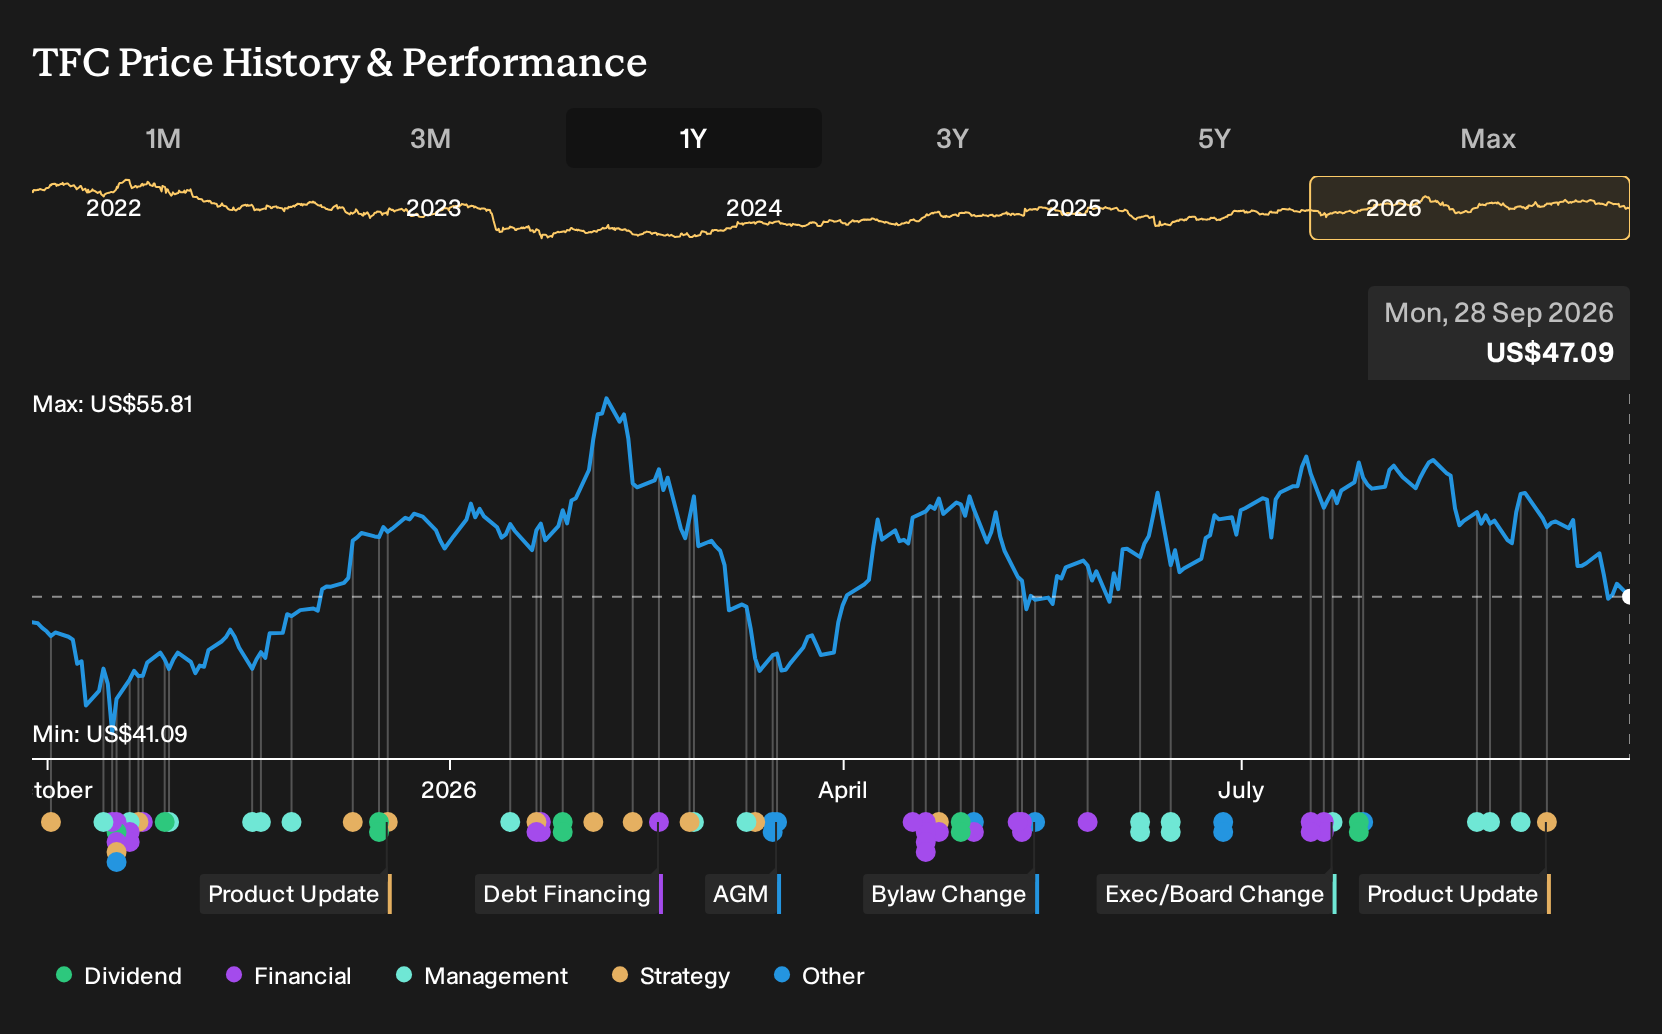
- Truist Financial recently posted quarterly results where revenue and earnings per share were above analyst estimates, while net interest income fell short and overall revenue growth lagged diversified banking peers.
- The slowest revenue growth in its peer group highlights pressure on Truist Financial’s core banking engine, even as headline results cleared consensus forecasts.
- We will now look at how Truist Financial's mixed revenue and net interest income performance could reshape the existing investment narrative.
Truist Financial Investment Narrative Recap
To own Truist Financial, you need to be comfortable with a traditional regional bank that is leaning hard into digital, while still carrying a sizable branch footprint and exposure to commercial real estate. The latest quarter, with revenue above expectations but the weakest growth versus peers, keeps attention squarely on execution in core lending and fee income rather than changing the long term story.
In the near term, the main swing factor is whether Truist Financial can stabilise net interest income while keeping credit costs contained, particularly in commercial real estate. The biggest operational risk remains that a slower shift away from branches and higher regulatory and technology costs keep pressure on margins. The recent earnings miss on net interest income reinforces that margin sensitivity, but does not yet fundamentally alter it.
There were no fresh company specific announcements tied directly to this earnings release in the feed provided, so the most relevant context is the existing setup investors are already trading against. Truist Financial is viewed as offering a relatively high dividend yield of 4.42%, and is trading on a P/E of 10.4x, which sits below both its own fair value estimate and the US banks industry average.
That combination of income and valuation support is what many shareholders are watching against the current catalysts and risks. Continued progress in digital adoption, Sunbelt expansion and fee based services could help offset pressure from branch costs, commercial real estate exposure and tighter regulation. If these areas do not progress as hoped, the recent share price reaction to softer net interest income illustrates how quickly sentiment can shift based on earnings quality and the mix of growth drivers.
Truist Financial Earnings and Revenue Assumptions
Analysts currently frame Truist Financial around a simple earnings bridge. The business is reported to earn about US$5.2b today and the consensus view points to US$6.1b of profit by 2029, which is an increase of roughly US$0.9b. That future outcome is tied to forecast annual revenue expansion of 8.9% and a model that accepts slightly lower profit margins as the price of heavier technology and regulatory spending.
Truist Financial's narrative projects US$24.1b revenue and US$6.1b earnings by 2029. This requires 8.9% yearly revenue growth and an earnings increase of roughly US$0.9b from US$5.2b today.
Uncover why Truist Financial's fair value indicates a 19% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community cluster between US$55.88 and US$74.54, so private investors already span a wide band on Truist Financial. Set that against branch cost risks, commercial real estate exposure and heavier regulation, and you see why opinions differ and why it helps to explore multiple angles.
Explore another Truist Financial fair value estimate, including one that suggests it could be worth just $55.88.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Truist Financial research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Truist Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Truist Financial's overall financial health at a glance.
Looking For More Investment Ideas Beyond Truist Financial?
If the Truist Financial story has sharpened your thinking and you want to widen your watchlist, the Simply Wall St Screener can help you quickly filter for other opportunities that better fit your risk profile, income needs, or value focus.
- For investors who prioritise steady income and resilience, consider a curated 6 dividend fortresses that focuses on businesses aiming to pair higher yields with durable cash generation.
- If capital preservation and lower volatility matter most to you, scan a 30 resilient stocks with low risk scores that screens for companies with more resilient financial profiles and fewer red flags.
- When you want to get ahead of the crowd, review a targeted 16 high quality undiscovered gems that highlights underfollowed stocks with stronger fundamentals than their limited attention might suggest.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com