


Earthquake Warning Might Change The Case For Investing In Tohoku Electric Power Stock (TSE:9506)
- A magnitude 7.5 earthquake struck off northeastern Japan in late September 2026, triggering tsunami warnings and evacuations, while Tohoku Electric Power Company reported no abnormalities at its idled nuclear facilities.
- The event has sharpened attention on Tohoku Electric Power Company's exposure to seismic risk, potential infrastructure stress, and the operational burden of safeguarding assets in a region with recurring earthquake activity, alongside recently declined annual revenue.
- Attention now turns to how Tohoku Electric Power Company's investment narrative absorbs this new test of earthquake resilience and infrastructure risk management.
Compare Tohoku Electric Power Company's earthquake risk story with other grid and energy players by scanning our hand-picked 39 power grid technology and infrastructure stocks, positioned at the fault line of infrastructure resilience and opportunity.
What Is Tohoku Electric Power Company's Investment Narrative?
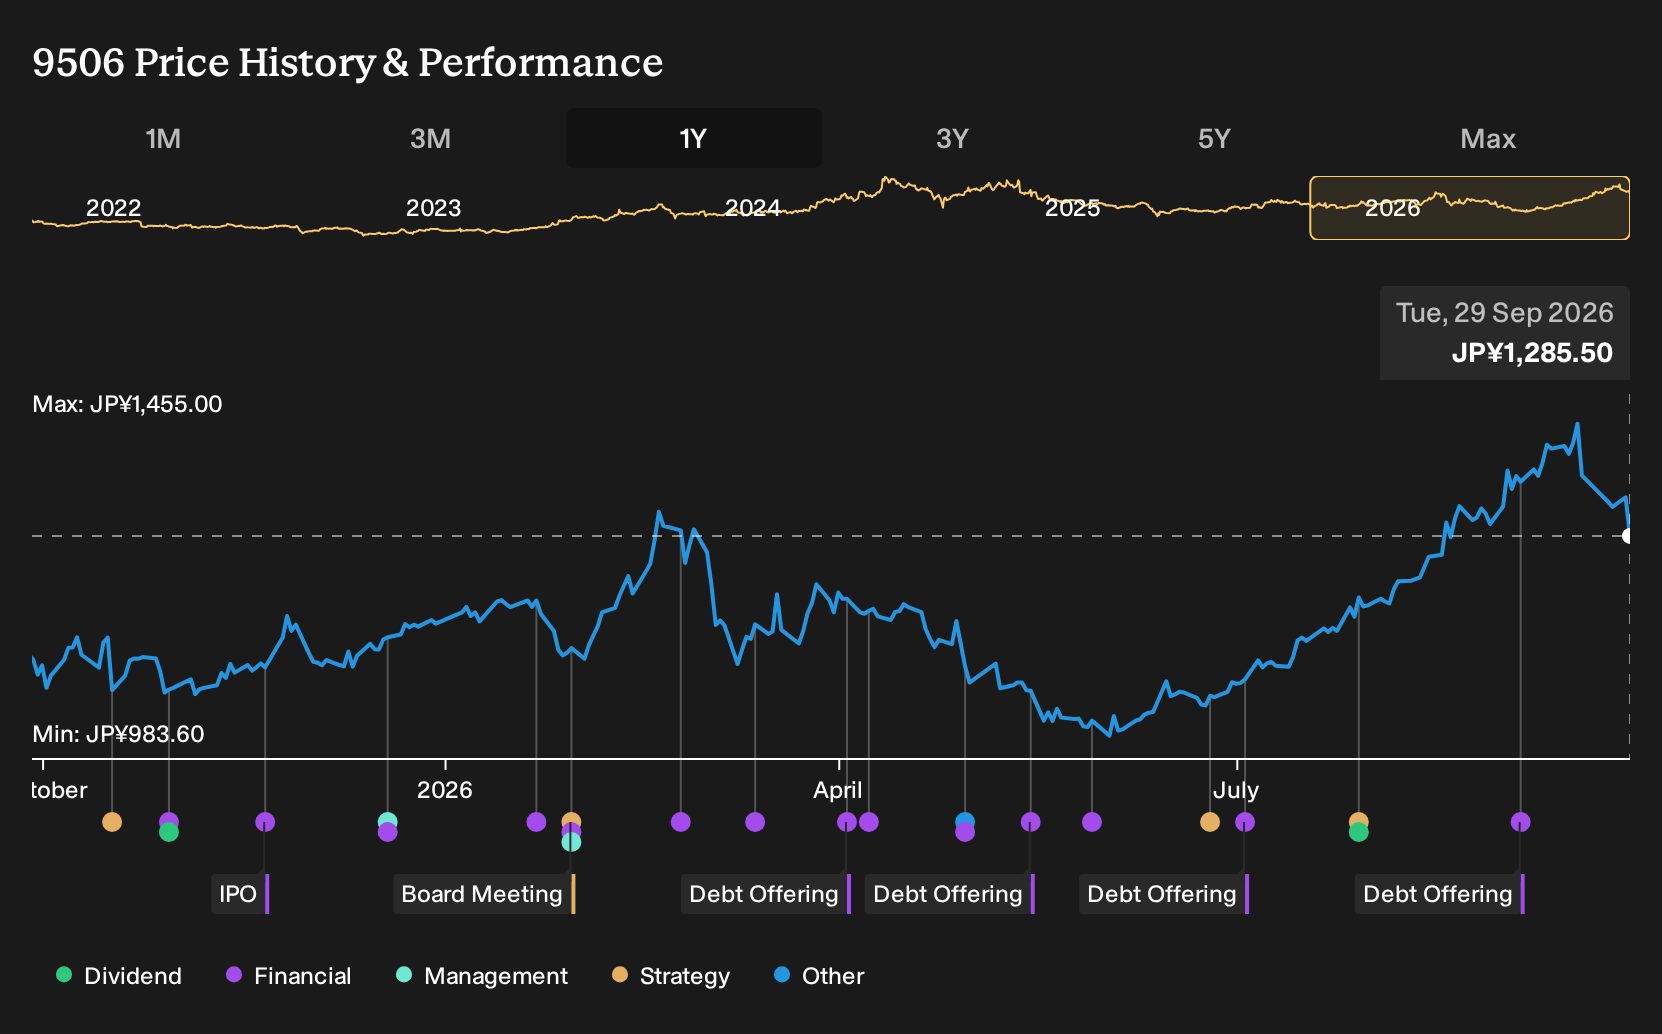
To own Tohoku Electric Power Company, you need to be comfortable with a capital heavy utility whose story is about keeping a complex grid running in a seismically active region while squeezing earnings out of fairly modest margins. The recent 7.5 quake tested that setup. With no reported abnormalities at its idled nuclear facilities, the immediate operational hit looks limited, and the recent pullback after a strong 1 year share return reads more like a sentiment reset rather than a clear break in the thesis.
In the short term, the real swing factors are still basic execution, tariff conditions and how management funds an asset base that produced ¥2,622,344 in revenue on relatively thin 3.2% profit margins. Debt is not well covered by operating cash flow, the dividend is not well backed by free cash, and revenue is forecast to decline even as earnings are expected to rise 3.9% a year. Earthquake headlines plug directly into that funding question, because every future grid hardening project and safety upgrade will feed into the same balance sheet that already leans on higher risk borrowing.
Even so, one aspect of Tohoku Electric Power Company's risk profile tends to get far less attention than the seismic story, and it sits in...
There's only one way to know the right time to buy, sell or hold Tohoku Electric Power Company. Head to Simply Wall St's company report for the latest analysis of Tohoku Electric Power Company's Fair Value.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Tohoku Electric Power Company research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Tohoku Electric Power Company. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tohoku Electric Power Company's overall financial health at a glance.
Looking For More Investment Ideas Beyond Tohoku Electric Power Company?
If this earthquake focused story around Tohoku Electric Power Company has sharpened your view on risk, it can help to line it up against a wider watchlist. The Simply Wall St Screener lets you quickly filter for different combinations of quality, balance sheet strength, income, or lower volatility so you can see where this utility fits among other opportunities.
- If you care most about resilient financial footing, start with a list of solid balance sheet and fundamentals (22 results) and see which businesses pair sturdy balance sheets with more flexible capital options.
- For readers hunting for potential mispricings, scan through a 19 high quality undervalued stocks and compare those candidates with how you see risk and reward lining up at Tohoku Electric Power Company.
- Income focused investors can anchor their research on a 20 dividend fortresses that screens for higher yields while still keeping an eye on fundamentals and payout support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com