


3 Chip Equipment Stocks Retail Investors Are Watching On US China Trade Hopes
Optimism around U.S.-China trade talks has lit a fresh spark under large-cap tech, with chipmakers and cloud software stocks at the center of the story. When tariffs and intellectual property disputes look closer to a truce, investors start rethinking which companies might benefit most if global supply chains run more smoothly. This article walks through 3 stocks from our screener that appear especially exposed to this shift and explains what that could mean for your portfolio decisions.
The three tickers highlighted next are just a starting sample, and the full screen surfaced 24 more large-cap tech companies with equally compelling narratives that are not covered here. To spot candidates that best fit your own risk tolerance and time horizon, head straight into the U.S.-Listed Large-Cap Technology Growth Stocks screener to identify and analyze the highest-conviction plays.
Onto Innovation (ONTO)
Onto Innovation sits in the sweet spot of this large-cap tech growth screen, supplying process control gear that chip fabs rely on when they ramp production for semiconductors and cloud hardware. This is exactly where improving U.S. and China trade sentiment is being felt first.
Onto Innovation generates essentially all of its US$1.12b revenue from semiconductor equipment and services, supplying inspection and metrology tools and software across global chip fabs, and carries a market value of roughly US$14.1b.
"The company’s Dragonfly platform recently passed TSMC’s New Tool Selection Committee qualification process for 2.5D advanced packaging applications. This is a significant milestone that could materially expand Onto’s role in the semiconductor ecosystem over the next several years."
What happens if that single, tightly linked demand driver scales faster than the rest of Onto Innovation’s business is where the story gets interesting.
That tipping point is exactly what the full narrative for Onto Innovation unpacks. It shows how Onto Innovation’s momentum could either accelerate or stall as chip demand and trade flows keep shifting.

Nova (NVMI)
Nova is one of the clearest examples of what this large-cap tech growth screen is trying to surface: a U.S.-listed process control specialist whose tools sit at the intersection of global chip capex, trade-sensitive supply chains, and advanced logic and packaging investments.
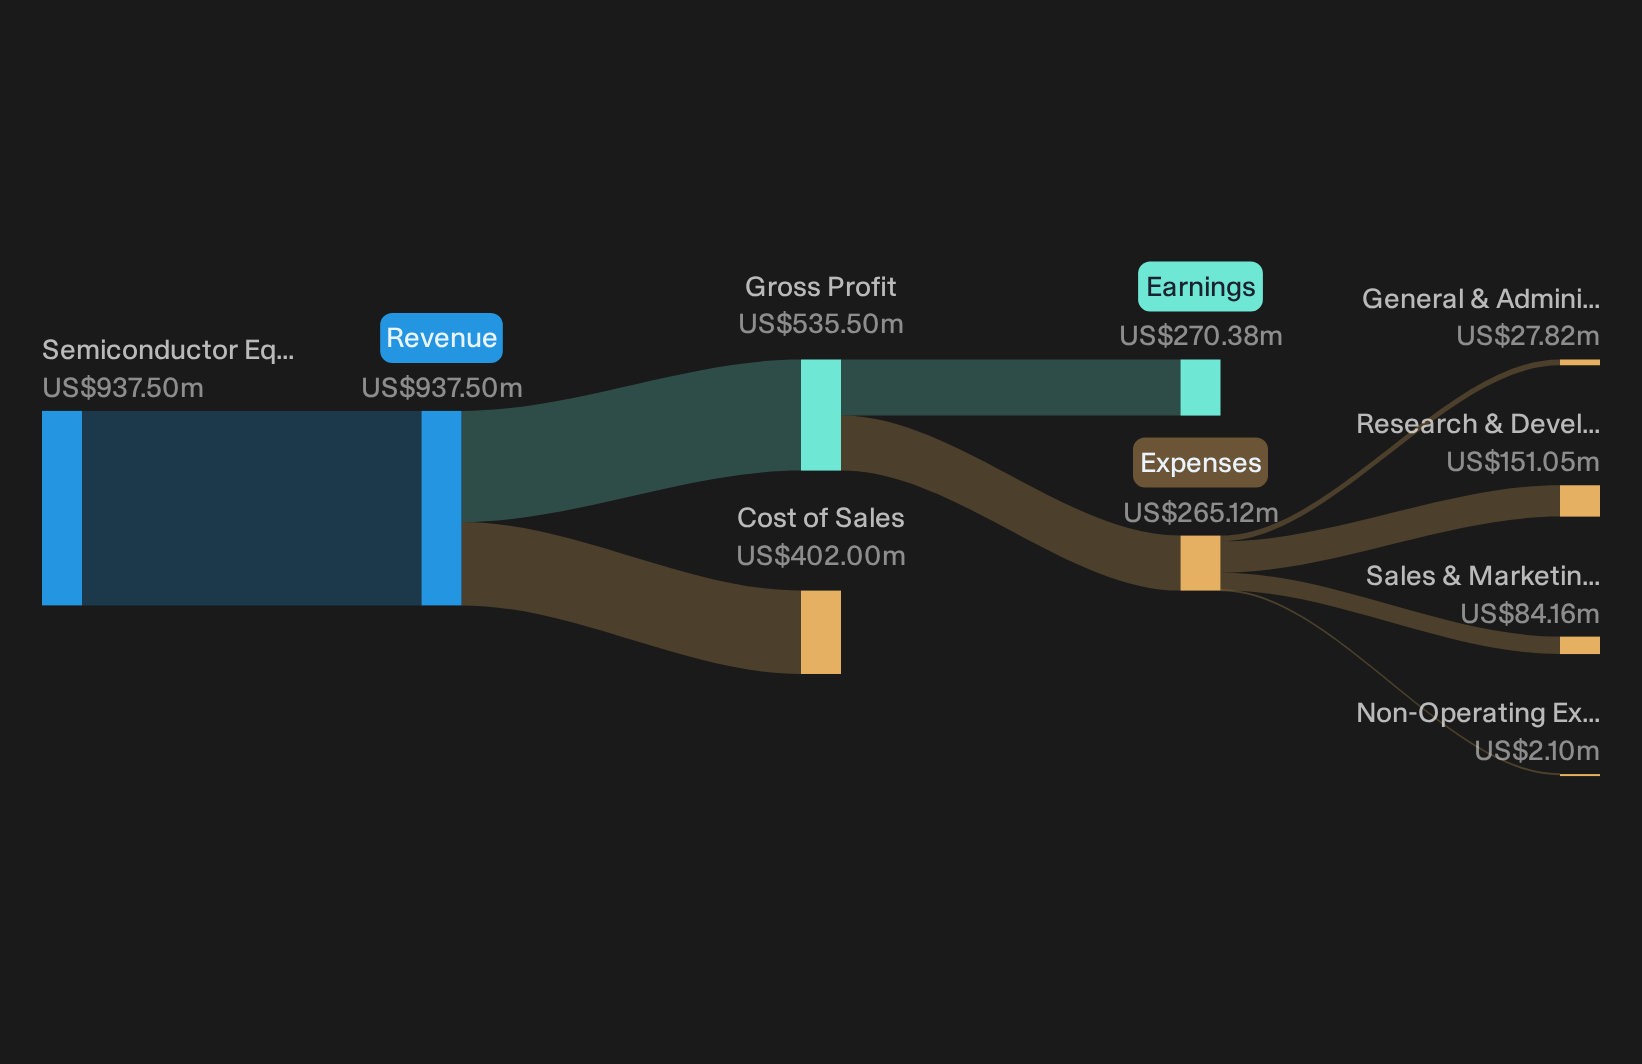
Nova designs and sells metrology and process control systems used across key semiconductor steps, generating about US$937 million from semiconductor equipment and services, and carries a market value of roughly US$11.7b.
"The accelerating complexity of semiconductor devices, driven by AI, larger die sizes, advanced nodes, and heterogeneous packaging, continues to fuel demand for Nova's advanced metrology solutions across both logic/foundry and memory segments."
What matters next is how one unresolved pressure on profitability interacts with demand for Nova’s tools.
That unresolved pressure is exactly what the full narrative for Nova unpacks, revealing where Nova’s metrology demand could decouple from margin strain and how that balance might accelerate.
KLA (KLAC)
KLA is the purest expression of this screener’s theme, a US$245.2b process control heavyweight whose inspection, metrology, and specialty tools help keep global chip production on track, with most of its US$13.6b in revenue coming from Semiconductor Process Control and smaller contributions from Specialty Semiconductor Process and PCB and Component Inspection.
KLA is exactly the kind of large-cap semiconductor equipment stock this screen is looking for, because its process control tools sit right where global capex, AI build outs, and trade sensitive supply chains intersect.
"Rising AI infrastructure and high bandwidth memory investment is lifting wafer equipment demand, and KLA’s backlog of around US$12.5b with lead times that extend into 2027 and 2028 supports multi year visibility that can translate into higher revenue and earnings quality."
What investors really need to watch now is how one less visible pressure on margins and cash generation interacts with that long-dated backlog.
That margin pressure is exactly where the full narrative for KLA picks up, revealing how KLA’s backlog, cash engine, and risk factors could be evolving beneath the surface.

Seeking Alternatives Before The Crowd?
Fresh opportunities can move quickly as breakout themes gain momentum and early pricing edges emerge. These trends may remain under the radar for now, so consider exploring them promptly.
- Spot income workhorses built for resilience while yields stay elevated by scanning the curated 6 dividend fortresses that keep cash returns front and center.
- Track early movers in core infrastructure for AI build outs by scanning the hand picked 39 power grid technology and infrastructure stocks positioned for heavy data and energy demand.
- Target future facing automation leaders before they gain broader attention by combing through the focused 91 robotics and automation stocks quietly building long term momentum.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com