


Verisk Analytics (VRSK) Is Back In The Spotlight, But What Is Driving It?
Verisk Analytics (VRSK) has appointed Greg Alling as president of casualty solutions, placing a seasoned casualty claims and digital transformation specialist in charge of this core insurance analytics segment for the business.
Verisk Analytics shares trade at US$167.77 after a sharp 12.52% decline in the 1 month share price return and a 24.09% fall year to date, while the 1 year total shareholder return is down 31.88%, pointing to fading momentum even as management refreshes its casualty leadership bench.
Scan how Verisk Analytics compares with a hand-picked 32 high quality undervalued stocks that have stronger momentum or more resilient sentiment in this part of the market.
After a slide in Verisk Analytics shares and a fresh leader stepping into casualty solutions, you face a simple fork in the road. Is this reset already reflected in the price, or is patience the better entry here?
Most Popular Narrative: 118.3% Overvalued
Verisk Analytics closed at $167.77, while the most followed narrative on the stock pegs fair value at $76.85, implying a steep valuation gap that frames how investors interpret the recent share price slump and leadership change.
Verisk Analytics is a regulatory-grade data toll on the US property & casualty insurance industry, monetized through approximately 83% subscription revenue with approximately 92% client retention. VRSK's narrow-moat franchise produces FCF with an unusually high degree of predictability, durable enough to justify a 15× exit multiple at a 35% margin of safety. The 2022 to 2025 portfolio simplification (Energy, Argus, 3E, Marketing Solutions all divested) has produced a cleaner pure-play with structurally higher margins (Adj EBITDA 56.2% in 2025 vs. 53.5% in 2023) and a shrinking share count (approximately 19% reduction since 2019). What the investor is paying for here is a regulatory annuity with an embedded MSD price-and-volume escalator, and walking away from any thesis premised on this becoming a HSD-to-DD revenue compounder.
See why 7 investors see Verisk Analytics as 118% overvalued.
Result: Fair Value of $76.85 (OVERVALUED)
Still, Verisk Analytics leans heavily on US property and casualty insurance workflows, so any regulatory shift or client pushback on pricing could disrupt that subscription engine.
Find out about the key risks to this Verisk Analytics narrative.
Another View: Verisk Analytics Through A Cash Flow Lens
A very different picture emerges when you look at Verisk Analytics through the SWS DCF model. On this view, VRSK at $167.77 is trading below an estimated future cash flow value of $290.52, which implies the stock is undervalued on cash generation rather than earnings multiples alone. That split between the narrative fair value of $76.85 and a DCF figure above $290 raises a simple question for you: Which set of assumptions feels more realistic for how this business will actually convert its contracts into long term cash?
Look into how the SWS DCF model arrives at its fair value.
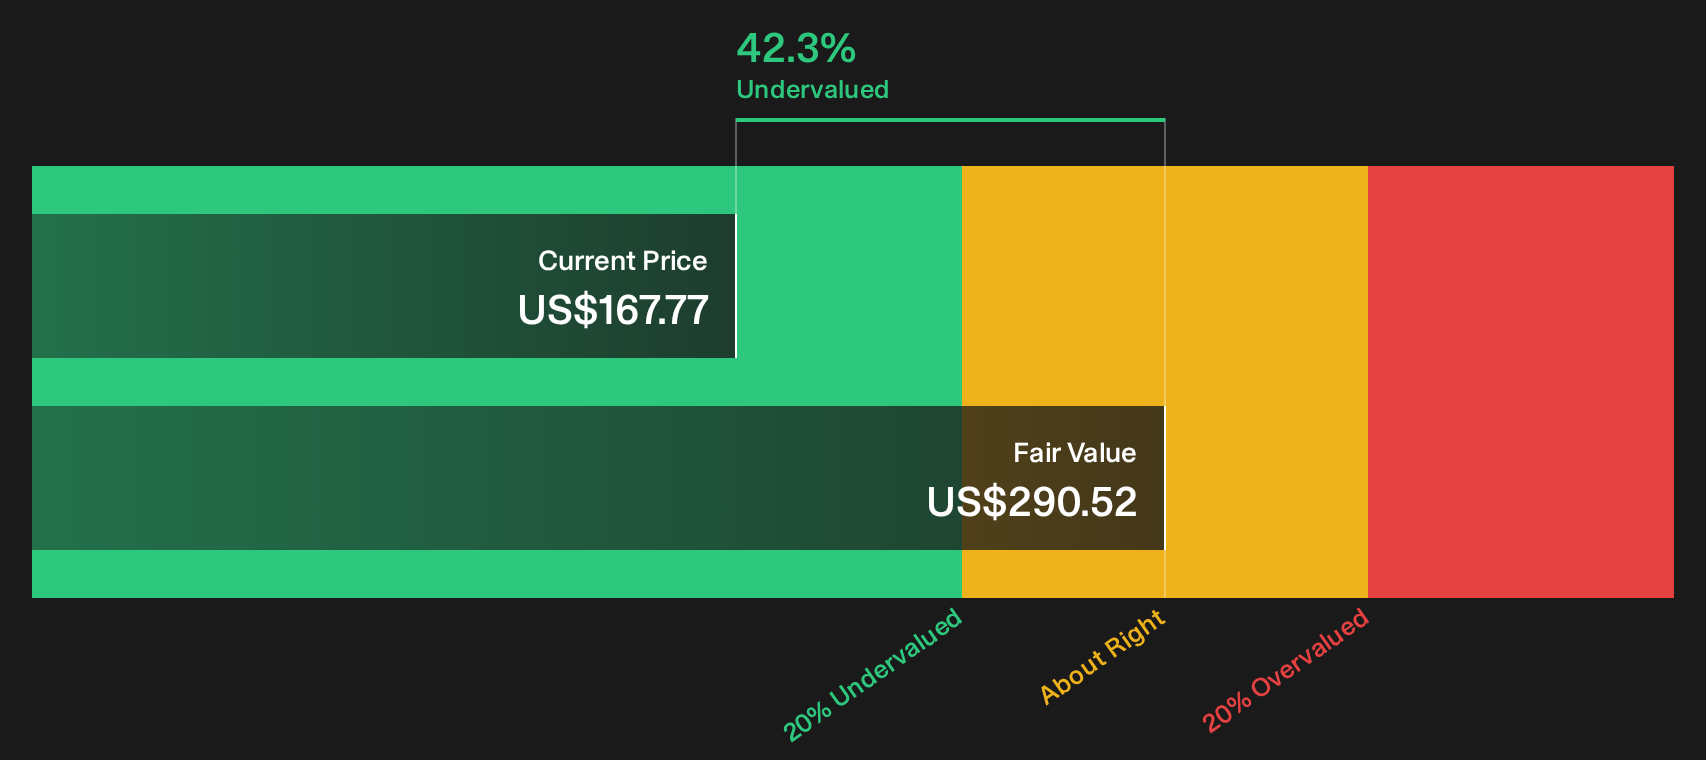
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Verisk Analytics for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Opinions on Verisk Analytics are split. This makes it a moment to move quickly, review the data yourself, and decide where you land. To see both sides of the story in one place, take a look at the 3 key rewards and 1 important warning sign.
Looking for more Verisk Analytics style investment ideas?
If the split views on Verisk Analytics have you thinking more broadly, use this moment to scan for other opportunities before they move without you.
- Target potential mispriced opportunities by reviewing a curated universe of quality businesses that screen as undervalued on fundamentals with the 32 high quality undervalued stocks.
- Prioritize resilience and capital strength by focusing on companies with cleaner finances using the list of solid balance sheet and fundamentals (25 results).
- Hunt for under-the-radar prospects that still show solid fundamentals by filtering through the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com