


Should Salesforce Contact Center Expansion Require Action From Bandwidth (BAND) Investors?
- Bandwidth expanded its collaboration with Salesforce, becoming the first certified carrier supporting Salesforce's AI-powered, CRM-native Contact Center across more than 25 countries via its Maestro platform.
- The deeper Maestro integration into Salesforce workflows gives enterprises tighter control and visibility over global customer communications. This directly ties into Bandwidth's focus on higher value, AI-driven usage rather than just raw calling volume.
- We will explore how Bandwidth's investment narrative evolves as Maestro underpins Salesforce's global, AI-native Contact Center rollout for enterprise clients.
Scan beyond Bandwidth and see which other communications players are building AI-ready customer contact platforms with the curated 84 AI infrastructure stocks.
Bandwidth Investment Narrative Recap
To own Bandwidth, you need to believe Maestro can keep shifting the business toward higher value, AI-centric communications rather than pure traffic volume. The expanded Salesforce Contact Center rollout reinforces that story, since it keeps Maestro embedded in a large CRM workflow. The near term swing factor still looks like how quickly enterprises adopt those AI voice and messaging use cases.
The biggest risk stays the same. Heavy reliance on Maestro and a concentrated, regulated enterprise base could hurt if large customers slow AI deployment or rework contracts. Rising network and R&D spend to support deeper Salesforce integration might also pressure margins if usage or pricing does not keep pace.
With no other fresh announcements on the tape, this expanded Salesforce collaboration is the key operational update for Bandwidth. It connects directly to the catalysts analysts have focused on, mainly higher revenue per call from AI use cases and larger, more complex enterprise deals as customers move off on premises systems.
The Maestro BYOC role inside Salesforce's Contact Center creates another test of execution. Management has to prove it can scale high touch support, keep regulatory compliance tight across more than 25 countries, and manage costs while global traffic shifts onto the platform. How that balance plays out will shape how investors view both growth durability and risk.
Bandwidth's current analyst story points to US$1.1b in revenue and US$72.9m in earnings by 2029, based on an assumed 11.2% yearly top line growth rate and an increase in earnings of about US$70.6m from US$2.3m today.
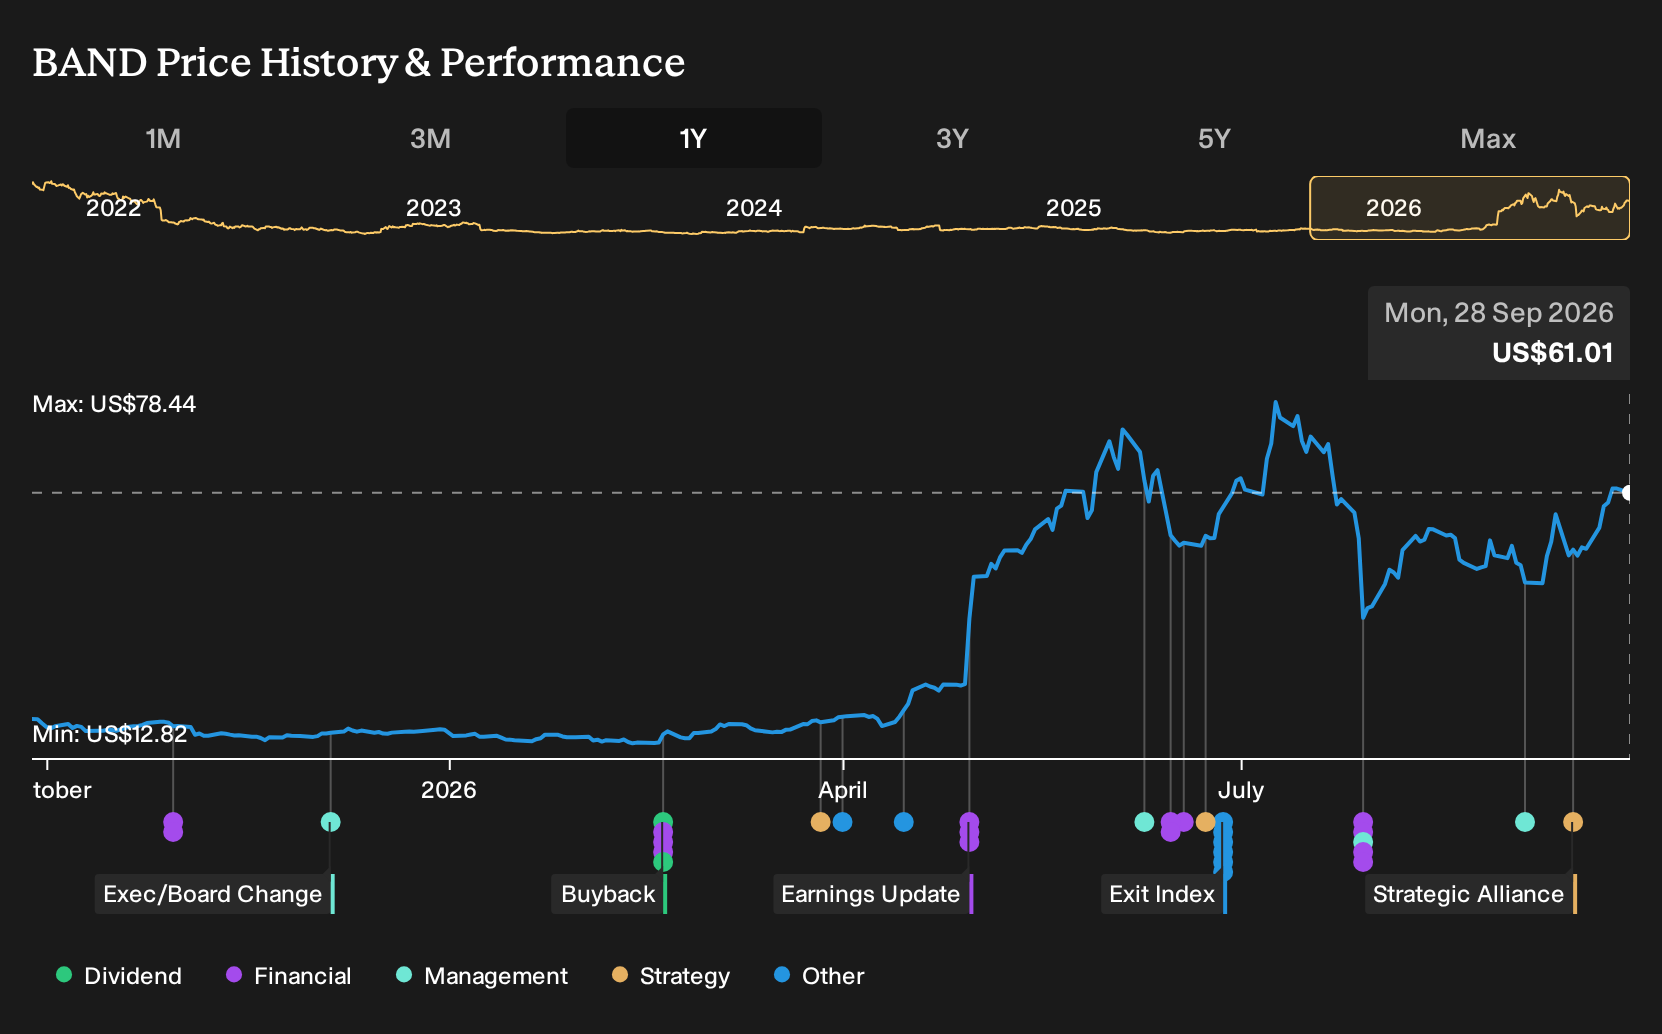
Uncover why Bandwidth's fair value indicates a 10% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
You are seeing only one version of Bandwidth today, while the most optimistic analysts picture something bigger. Their pre news models pointed to about US$1.2b in revenue and US$91.2m in earnings by 2029, assuming Maestro turns AI voice into a powerful revenue multiplier. Those views may shift as this Salesforce expansion sinks in.
Explore 3 other Bandwidth fair value estimates, including one that suggests as much as 207% potential upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Bandwidth research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Bandwidth. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bandwidth's overall financial health at a glance.
Looking For More Ideas Beyond Bandwidth?
If the Bandwidth story has sharpened your thinking about AI communications, broaden your watchlist by scanning other businesses that fit clear, disciplined criteria using the Simply Wall St Screener.
- If you want potential upside with a value tilt, filter for companies trading below their estimated worth using the 32 high quality undervalued stocks.
- If balance sheet strength matters most to you, narrow your focus to firms with robust finances through the list of solid balance sheet and fundamentals (25 results).
- If you prefer opportunities the market may be overlooking, hunt for quieter quality stories with the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com