


Alliance Resource Partners (ARLP), Why Is It Back In The Spotlight?
Alliance Resource Partners (ARLP) has drawn attention after recent trading left the units down about 5% over the past month, even as the past 3 months still show a positive total return.
For context, Alliance Resource Partners units have eased in the near term, with the 7 day share price return down 3.8% and the 30 day share price return down 5.2%. However, the year to date share price return of 6.6% and a 5 year total shareholder return of 248.5% point to momentum that has built over a longer horizon as investors have reassessed both income potential and risk around the current US$24.83 price.
Scan beyond Alliance Resource Partners and compare this recent pullback with other income focused enterprises on our hand picked list of 6 dividend fortresses.
Alliance Resource Partners units have slipped in the short term while longer term holders still see sizable gains, so the real puzzle is whether you step in at about US$24.83 now or wait for a cheaper valuation.
Preferred P/E of 12.1x for Alliance Resource Partners: Is it justified?
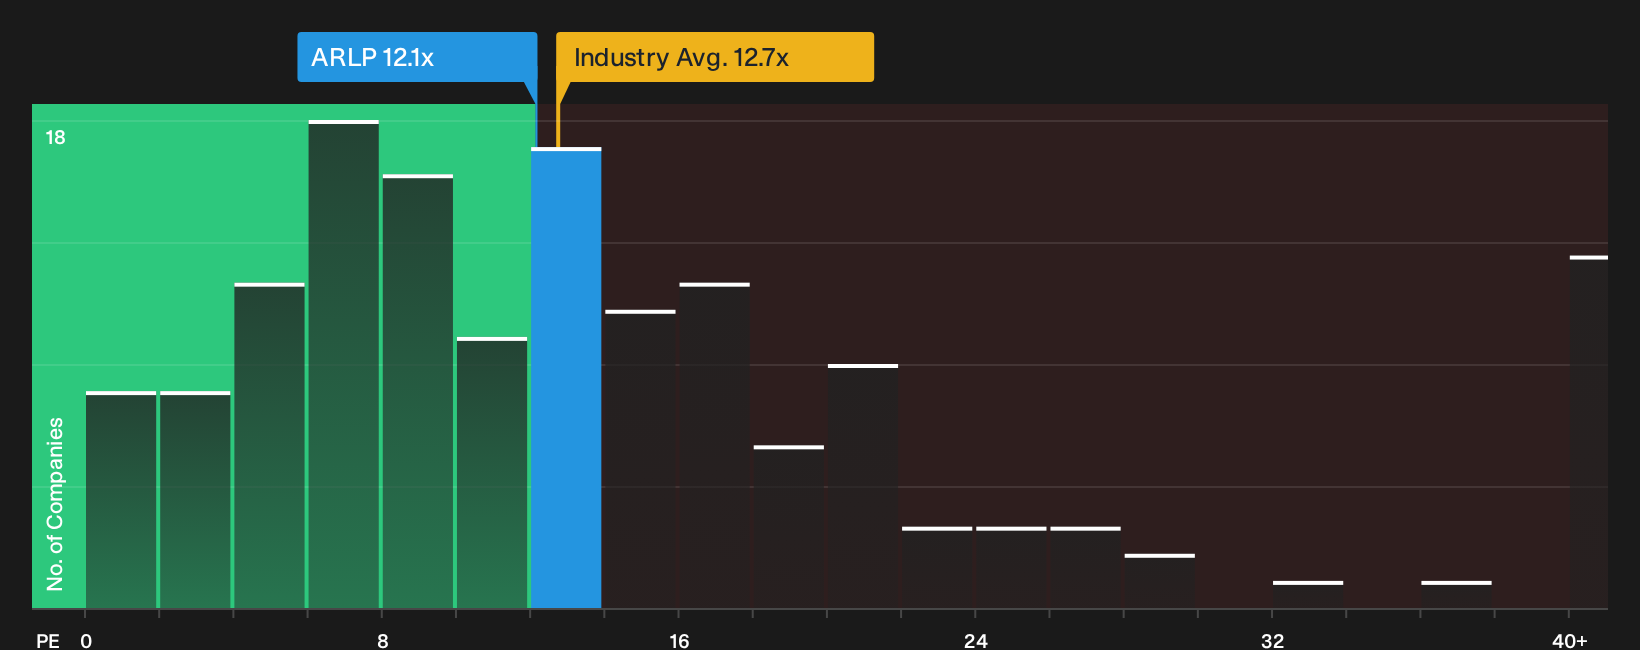
On simple valuation terms, Alliance Resource Partners looks inexpensive with a P/E of 12.1x at a last close of $24.83, while still showing a sizable gap to both industry averages and an estimated fair level for the multiple.
The P/E ratio compares the current unit price with per unit earnings, so it effectively tells you how many dollars investors are paying for each dollar of profit. For a coal and royalties focused partnership like Alliance Resource Partners, this matters because earnings are closely tied to commodity cycles and contract structures rather than high growth expectations.
Against that backdrop, the current P/E of 12.1x appears favorable compared to the US Oil and Gas industry average of 12.7x and a higher peer group average of 33.4x. The estimated fair P/E of 18.2x is above where the units trade today, which indicates there is a notable gap between the current and estimated fair earnings multiple.
Explore the SWS fair ratio for Alliance Resource Partners.
Result: Price-to-earnings of 12.1x (UNDERVALUED)
Still, the investment case for Alliance Resource Partners can be knocked off course if coal demand weakens or if regulatory costs eat into earnings.
Find out about the key risks to this Alliance Resource Partners narrative.
Another View on Alliance Resource Partners’ valuation
The earlier P/E checkpoints suggest Alliance Resource Partners looks inexpensive at 12.1x earnings, particularly when compared with the US Oil and Gas average of 12.7x, a peer group around 33.4x and a fair ratio of 18.2x that the market could move toward over time. That gap indicates both upside potential and the risk that expectations do not close it. See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Alliance Resource Partners for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Alliance Resource Partners can leave the picture feeling incomplete, so check the key numbers, weigh both sides, and move quickly to shape your own stance. To see how risks and rewards compare in one place, review the 5 key rewards and 1 important warning sign
Looking for more investment ideas beyond Alliance Resource Partners?
If Alliance Resource Partners has sharpened your focus on value and income, do not stop here. Broaden your watchlist with a few targeted, data driven ideas that could sharpen your next move.
- Target resilience by scanning a 30 resilient stocks with low risk scores that can help you focus on businesses with steadier risk profiles and fewer balance sheet surprises.
- Hunt for mispriced quality through a 16 high quality undiscovered gems and see which under followed stocks still pair strong fundamentals with attractive valuations.
- Anchor your income plans with a 6 dividend fortresses that highlights companies offering higher yields backed by underlying business strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com