


Why Marathon Petroleum (MPC) Is Drawing Fresh Attention Today
Marathon Petroleum (MPC) moved back into focus after political comments about a possible U.S. diesel export ban and renewed attention on energy supply disruptions pushed refining stocks higher in recent trading.
Despite the latest pullback, with a 1-day share price return of 1.04% lower and a 7-day share price return of 3.22% lower, Marathon Petroleum has experienced a strong upswing over 2026, with a year-to-date share price return of 135.82% and a 1-year total shareholder return of 101.53%. This indicates sustained momentum rather than a short-lived spike.
Scan beyond Marathon Petroleum and explore other refiners and energy plays that screen well on value, cash flows, and balance sheet strength with our curated list of solid balance sheet and fundamentals (25 results)
After a run that has already delivered a triple digit 1 year return, the question now is whether Marathon Petroleum still offers meaningful upside or if most of the easy gains are already in the rear-view mirror.
Most Popular Narrative: 20% Overvalued
At a last close of $389.44 versus a widely followed fair value estimate of $324.56, the current price sits well above the narrative-based valuation for Marathon Petroleum and puts more pressure on the underlying thesis to hold up.
Ongoing strong demand for gasoline, diesel, and jet fuel, driven by resilient U.S. transportation needs, continued ICE vehicle prevalence (especially in states like California), and sustained global population and urbanization trends, positions Marathon for high throughput volumes and stable-to-rising revenue streams for the remainder of the decade.
See why 62 investors see Marathon Petroleum as 20% overvalued.
Result: Fair Value of $324.56 (OVERVALUED)
Still, if electrification or tighter environmental rules hit demand for refined fuels faster than expected, Marathon Petroleum’s large refining footprint could face pressure.
Find out about the key risks to this Marathon Petroleum narrative.
Another View on Marathon Petroleum’s Valuation
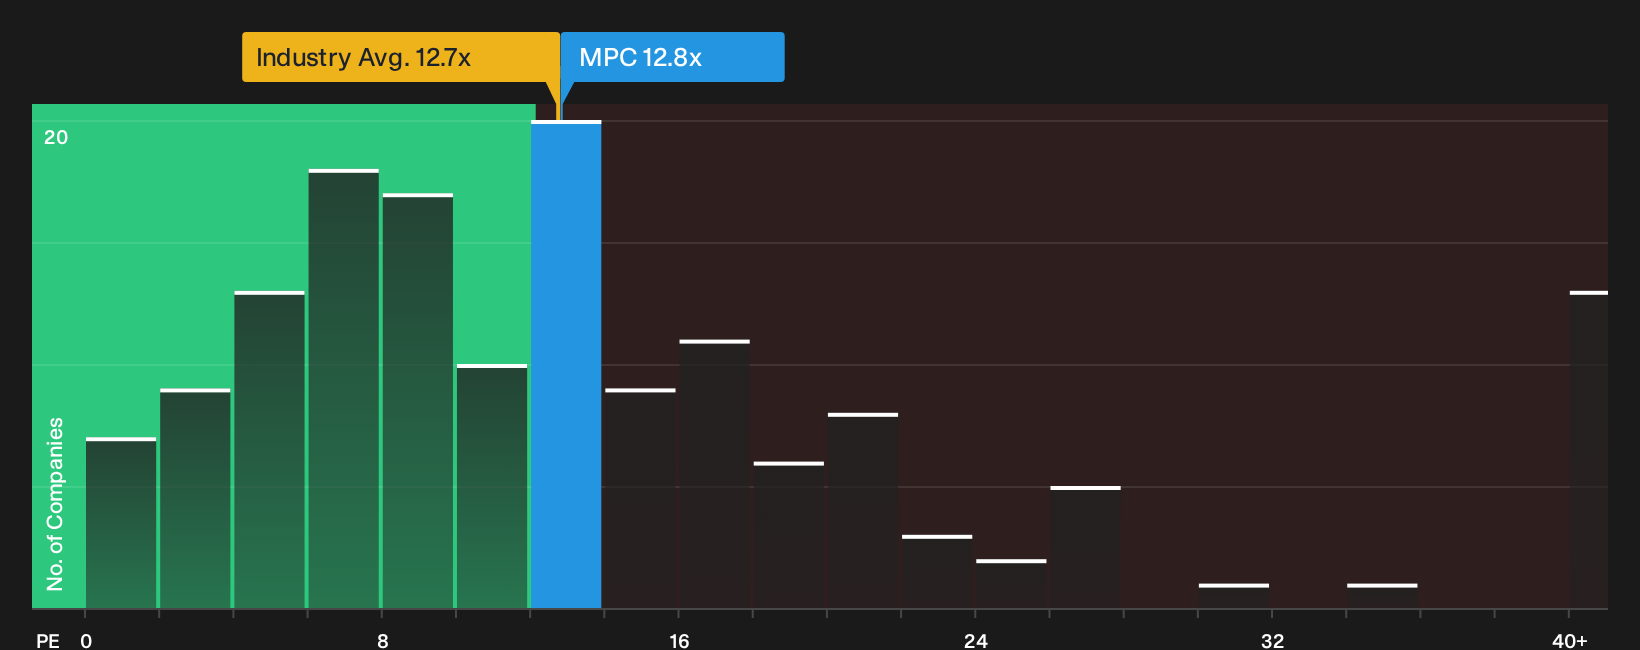
While the dominant narrative pegs Marathon Petroleum as about 20% overvalued versus the $324.56 fair value estimate, the picture shifts once simple earnings ratios are used. On a P/E of 12.8x versus a fair ratio of 13.4x, the stock looks modestly cheap, even though it trades slightly above both the US Oil and Gas industry at 12.7x and a peer average of 11.6x. That mix of a small discount to the fair ratio but a premium to competitors raises a practical question for you: Is this pricing a cushion, or is it a signal that expectations already assume a lot going right?
To see how that earnings multiple stacks up in more detail, including where valuation risk may sit if sentiment shifts, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on valuation and sentiment only matter if you use them. Review the data, pressure test your thesis, and weigh the 2 key rewards and 3 important warning signs.
Looking for more Marathon Petroleum investment ideas?
If Marathon Petroleum has sharpened your appetite for opportunity, do not stop here. Use focused screeners to spot other stocks that fit your criteria before the crowd does.
- Target potential mispricings by scanning companies that combine strong fundamentals with appealing valuations using our 16 high quality undiscovered gems.
- Focus on resilience and sleep-better-at-night holdings through a curated 30 resilient stocks with low risk scores that filters for stronger balance sheets and lower risk scores.
- Zero in on quality at a fair price by checking our 32 high quality undervalued stocks built to surface financially solid stocks that may not yet reflect their fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com