


What Do Amazon.com (AMZN) Investors Need To Watch After Three New Risks?
- Amazon.com (NasdaqGS:AMZN) is assessing damage to AWS data centers in the Middle East after reported Iranian drone strikes disrupted services.
- Senate Democrats have opened a formal inquiry into tax incentives tied to AI and data center spending by Amazon and other large tech groups.
- Consumer advocates in the UK have revived a lawsuit against Amazon that challenges how products are ranked and presented to shoppers.
- These AWS disruptions, new Senate scrutiny, and the renewed UK consumer case deserve to be weighed against our other findings on Amazon. Check out 4 other big wins that Amazon.com investors should know about.
For a broader view on how AI demand and data center spending are reshaping listed businesses, widen the lens to 84 AI infrastructure stocks.
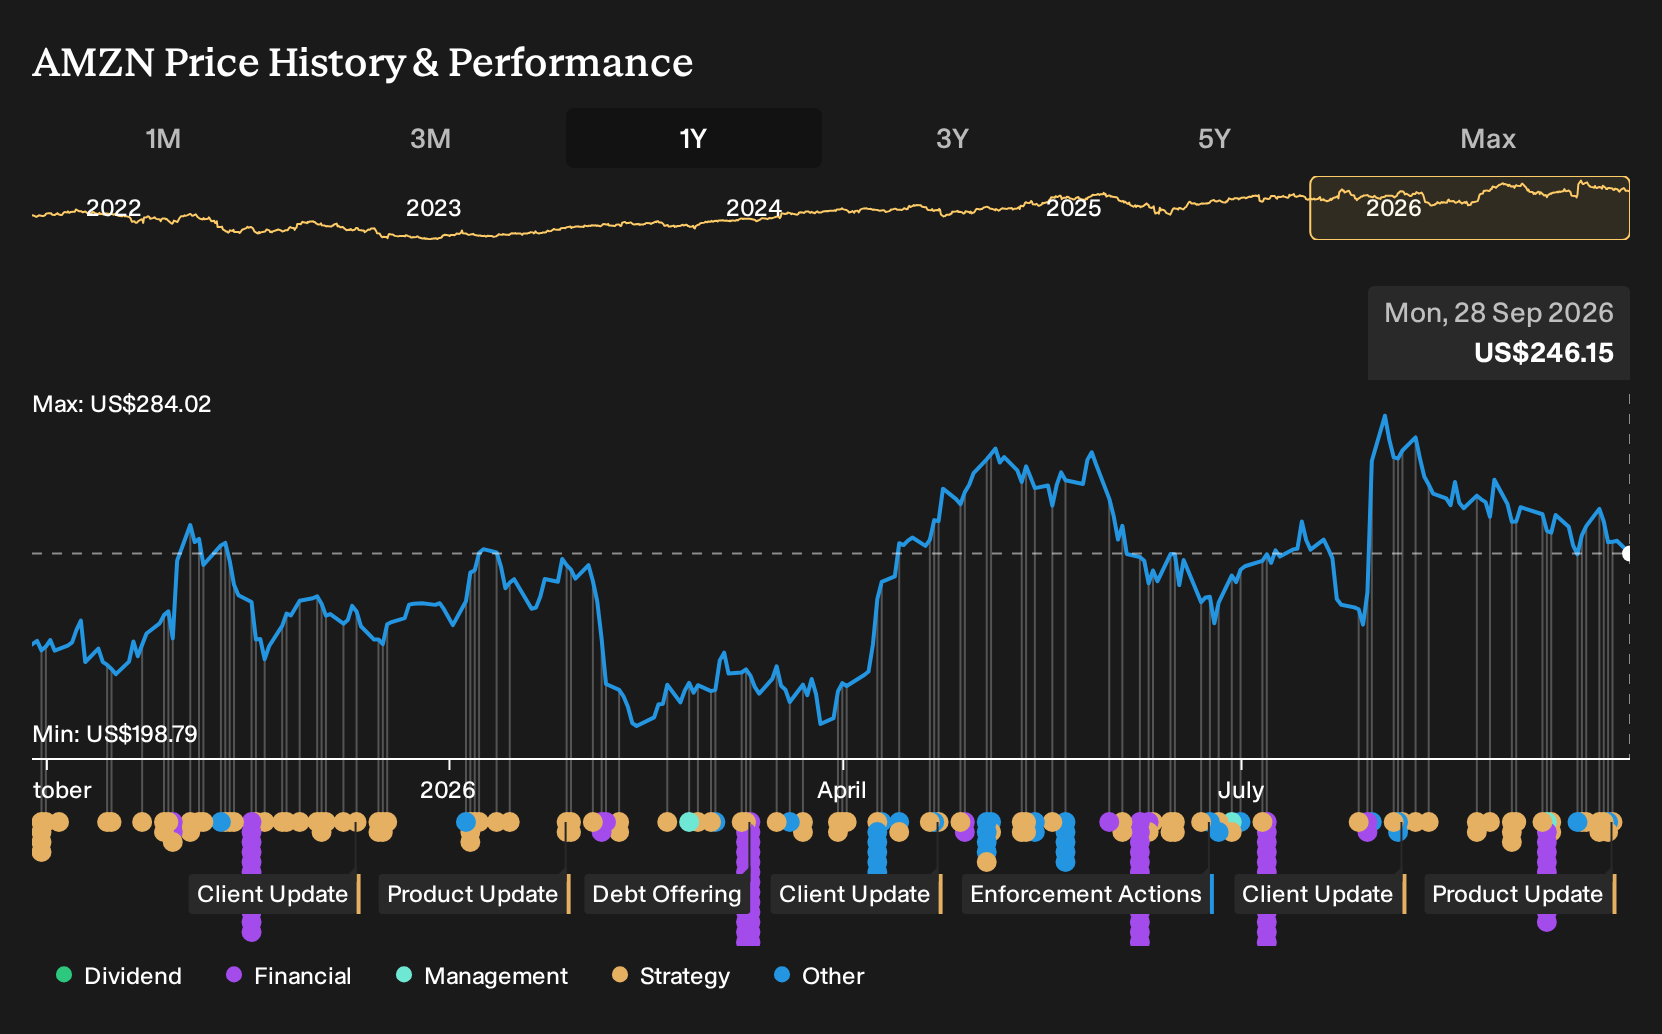
Amazon.com runs a global mix of online stores, physical retail, subscription services and advertising, all of which are increasingly tied to its cloud arm that powers much of the internet’s plumbing. Those sprawling operations mean questions about data center resilience, tax treatment of AI spending and how products surface on its marketplace all feed directly into how the group earns and allocates cash.
See how Amazon.com's balance sheet measures up.
What this AWS disruption, tax scrutiny, and UK lawsuit really test for Amazon investors
For Amazon.com, this cluster of setbacks pokes directly at the weak spots in its Narrative. Data center damage in the Middle East stresses the assumption that AWS can keep scaling AI infrastructure while holding service quality, a key plank in the story that heavy capex improves returns over time. The Senate inquiry into AI related tax breaks and the revived UK consumer case both lean into the existing risk that regulatory and legal pressure raise costs and restrict how the retail and cloud engines operate. None of this rewrites the AI and logistics upside, but it does make the cost and compliance side of the thesis harder to ignore.
See how these catalysts shape Amazon.com's path to a $327 fair value.
The cleanest early check on whether this is under control will be the next few quarterly updates on AWS uptime and segment operating margin alongside disclosed legal and regulatory expenses. If Amazon.com can keep cloud profitability broadly in line with recent history while quantifying any fines, remediation spending, or structural compliance costs from these issues, investors will have a clearer read on whether the long term AI and logistics cash story is holding up against the new shocks.
Add Amazon.com to your Watchlist and get alerts as these catalysts play out.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com