


How New Estate Concept Will Impact RH (RH) Investors
- RH opened RH Estates, The Gallery on Greenwich Avenue, its first freestanding Gallery in North America, after previewing the concept in Milan and London. A second RH Estates location in Los Angeles is planned for 2027.
- The RH Estates concept pushes RH further into immersive, destination retail. This can reshape store economics, capital needs, and how the brand reaches high-end home customers globally.
- We will now look at how RH's investment narrative could be influenced by the RH Estates destination concept in Greenwich.
Scan beyond RH and compare this destination retail shift with other high-end consumer and design companies using our curated list of 16 high quality undiscovered gems.
RH Investment Narrative Recap
To own RH, you need to believe the brand can turn its luxury positioning and gallery footprint into higher quality earnings while managing a heavy debt load and a fragile housing backdrop. The key near term swing factor remains execution on gallery productivity and design driven sales. The Greenwich RH Estates opening signals deeper commitment to high capital, high touch retail, which may amplify both upside and execution risk.
The biggest operational risk still sits around macro sensitive demand, tariffs, and the cost of carrying debt when interest payments are not well covered by earnings. Greenwich does not change that overnight. It does, however, raise the bar on RH proving that destination formats can support margins after startup costs and international expansion drag.
The Greenwich RH Estates launch aligns with the broader gallery rollout that includes 7 Design Galleries and 2 Outdoor Galleries planned for 2025. The same basic idea is playing out: larger, more immersive locations intended to lift sales per address and reinforce RH as a full lifestyle platform rather than a traditional furniture retailer.
That makes execution at Greenwich directly relevant to the wider expansion plan. If RH can show healthy traffic, strong ticket sizes, and disciplined capital returns from RH Estates, it strengthens the case for those future galleries. If returns disappoint, the combination of international startup costs, tariff uncertainty, and interest coverage pressure becomes a more pressing concern for shareholders monitoring both growth ambitions and balance sheet resilience.
RH's analyst narrative points to revenues of US$4.4b and earnings of US$260.4m by 2029, based on 8.9% yearly revenue growth and an earnings increase of about US$157m from US$103.1m today.
Discover how RH's fair value indicates a 43% potential upside to its current price that may not last much longer.
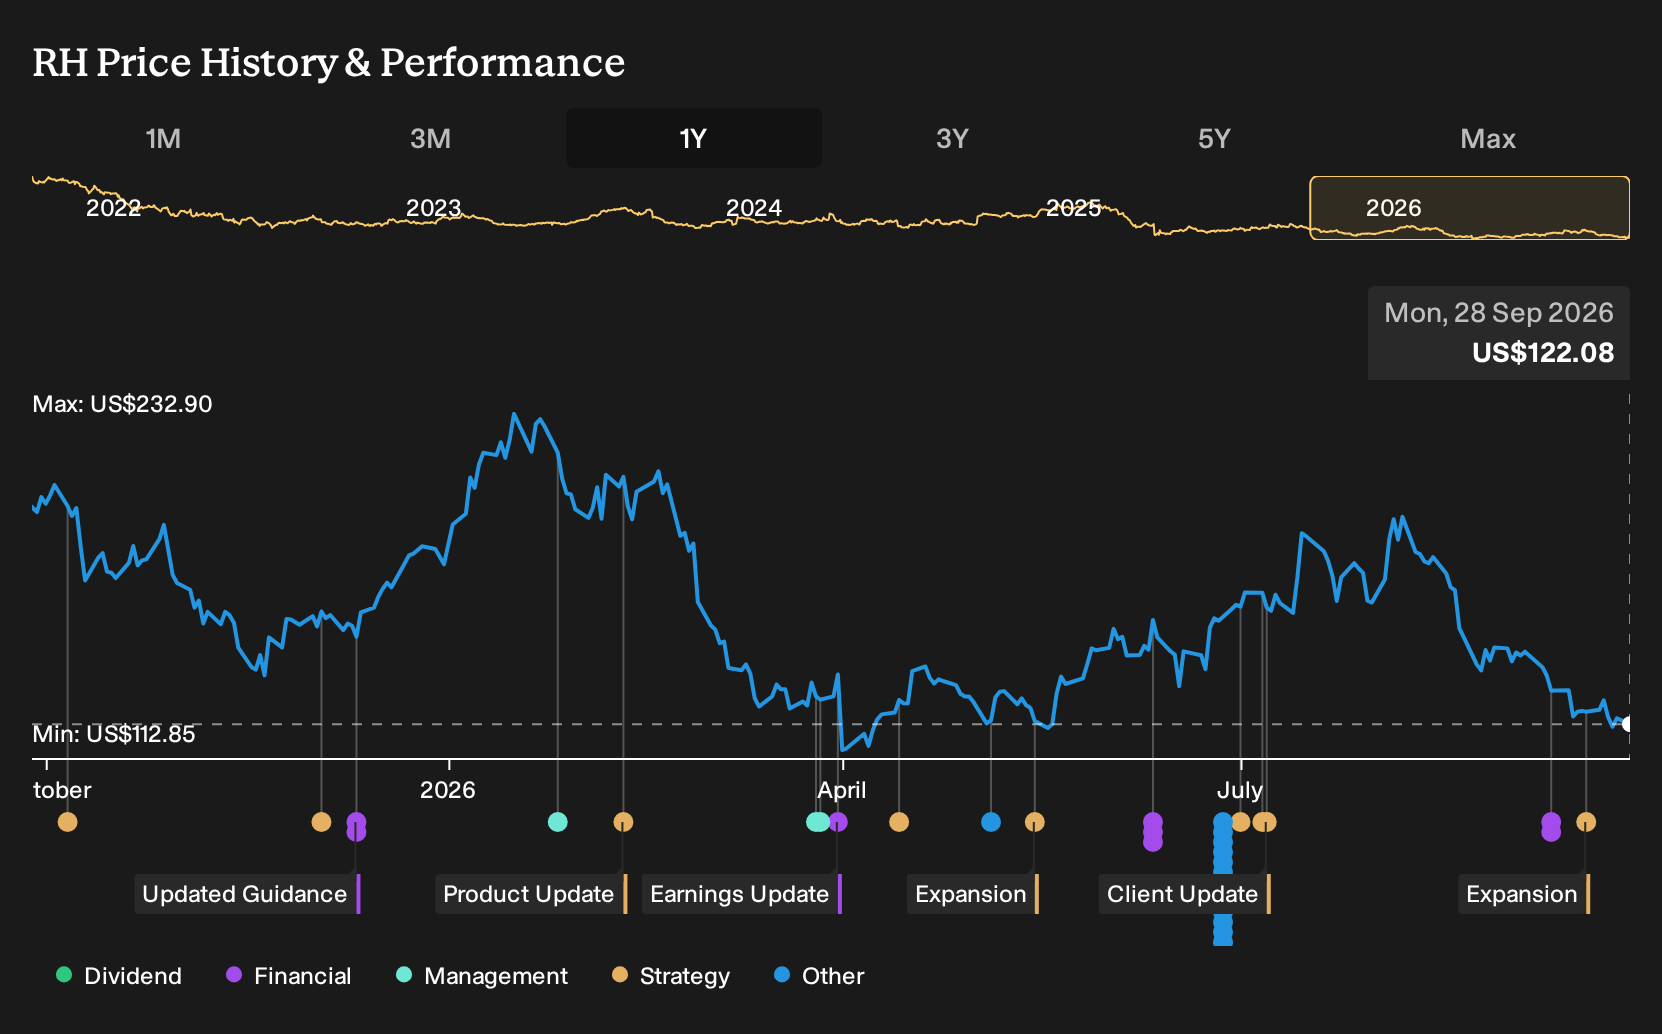
Exploring Other Perspectives
One big swing factor analysts debate for RH is how far these high cost showrooms can really take margins. The most optimistic group expected revenue of about US$4.5b and earnings near US$313.8m by 2029 even before Greenwich. Their take is far more upbeat than consensus, and the RH Estates opening could eventually push both narratives to shift.
Explore 4 other RH fair value estimates, including one that suggests potential upside of up to 117% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own research and judgment.
- A great starting point for your RH research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for RH. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review RH's overall financial health at a glance.
Looking For More Ideas Beyond RH?
If the RH story has sharpened your thinking about quality, risk, and balance sheets, it can be useful to line it up against other companies that fit different profiles. The Simply Wall St Screener lets you do that in a structured way so you can stress test your thesis instead of relying on a single stock.
- For investors who want strong fundamentals without paying any price for growth, scan through a 33 high quality undervalued stocks that combine quality metrics with discounted valuations.
- If capital preservation sits high on your checklist, weigh RH against a 30 resilient stocks with low risk scores that score well on financial strength and volatility.
- When balance sheet resilience is a priority, set RH alongside a list of solid balance sheet and fundamentals (25 results) that pair healthy leverage levels with solid underlying business performance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com