


Neurocrine Biosciences (NBIX) Could Be 34% Undervalued After Its CMO Return
Why Neurocrine Biosciences Is Back in Focus After a C-suite Shift
Eiry W. Roberts, M.D., is returning as Chief Medical Officer at Neurocrine Biosciences (NBIX) after the mutual departure of former CMO Dr. Sanjay Keswani, putting fresh attention on leadership continuity during late stage clinical work.
Neurocrine Biosciences shares recently closed at US$140.44, with the 90 day share price return down 16.67% and the 30 day share price return down 8.84%, even as the 3 year total shareholder return of 25.63% and 5 year total shareholder return of 39.33% point to a steadier long term record. This C suite reshuffle comes at a moment when short term momentum is fading and investors are reassessing execution risk around late stage programs.
Scan beyond Neurocrine Biosciences and identify other potential late stage winners in neurology and biotech by reviewing our curated list of 16 high quality undiscovered gems.
After a sharp 90 day pullback and a reset in the medical leadership seat, Neurocrine Biosciences now sits in a very different spot compared with its 3 and 5 year track record. Does that make today’s price an early entry or a patience test?
Most Popular Narrative: 34% Undervalued
On the most followed view, Neurocrine Biosciences is worth about $213 a share versus the recent $140.44 close. This puts the spotlight on whether execution across INGREZZA, CRENESSITY and newer assets can bridge that gap under a 7.28% discount rate.
Rapid and consistent early adoption of CRENESSITY, with demonstrated high rates of reimbursement (>75%), robust clinical profile, and significant unmet need in CAH, indicates the likelihood of future blockbuster status, driving both top-line revenue growth and improved operating leverage.
See why 47 investors see Neurocrine Biosciences as 34% undervalued.
Result: Fair Value of $213.13 (UNDERVALUED)
Still, the bullish Neurocrine Biosciences story can unravel if INGREZZA pricing pressure bites harder than expected or if Crenessity uptake plateaus under tighter payer controls.
Find out about the key risks to this Neurocrine Biosciences narrative.
Another View: What Multiples Say About Neurocrine Biosciences
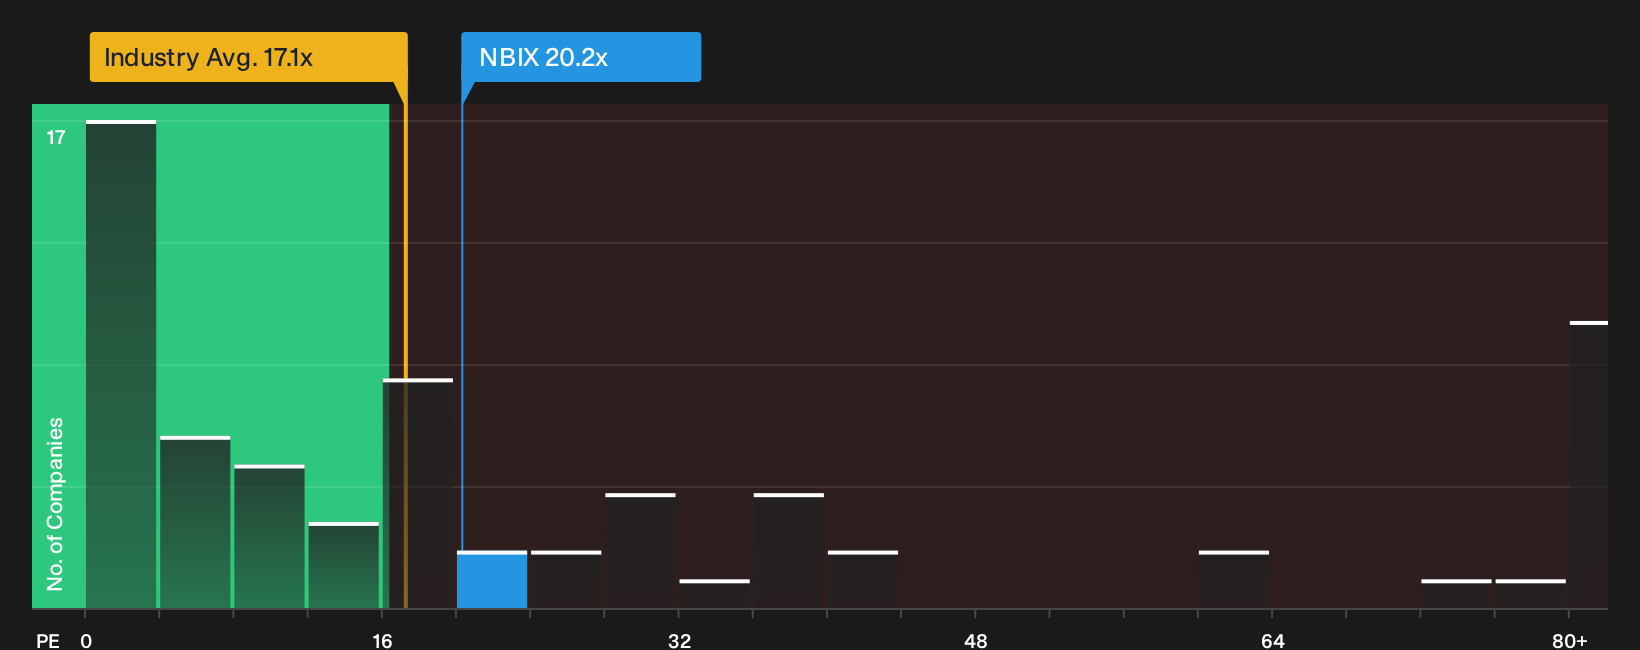
Neurocrine Biosciences may look inexpensive on a cash flow model, but the P/E tells a different story. The stock trades at 20.2x earnings versus 17.1x for the US Biotechs industry and a fair ratio of 24.5x. This means the market is already paying a premium, with only partial catch up to that fair ratio.
That gap suggests there may be some room for upside if sentiment moves toward the fair ratio, but it also leaves less margin for error if growth or pricing assumptions fall short. Which signal feels more useful for you: the richer multiple or the deeper cash flow estimate?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed sentiment on Neurocrine Biosciences leaves you unsure, move quickly to test the numbers, cross check the narrative, and weigh the 4 key rewards
Looking For More Investment Ideas Beyond Neurocrine Biosciences?
Keep Neurocrine Biosciences on your radar, but do not stop there. Broader ideas give you more options, context, and potential opportunities to compare.
- Target dependable value by scanning a curated mix of quality companies trading below their estimated worth through the 33 high quality undervalued stocks.
- Prioritize staying power by focusing on businesses with strong finances and healthy balance sheets using the list of solid balance sheet and fundamentals (25 results).
- Hunt for overlooked opportunities by zeroing in on lesser known stocks with solid fundamentals through the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com