


3 Great Canadian Dividend Stocks With Yield Over 3%
Higher interest rates are already pressuring parts of the global economy, yet Canadian dividend investors still have one clear advantage. Cash now competes with equities, so companies paying yields above 3% that appear well covered and steadily growing can appeal to investors who want regular income without relying on short term price moves. This article highlights three Canadian dividend stocks that fit that brief.
The three stocks in focus next are simply a sample of what this approach can uncover, since the full screen surfaced another 17 income ideas with similarly compelling stories that are not covered here. To go straight to the source and identify your own high conviction dividend candidates, head into the Dividend Powerhouses (3%+ Yield) screener
Sun Life Financial (TSX:SLF)
Sun Life Financial is a global insurer and asset manager whose fee-based wealth operations and recurring life and health insurance cash flows fit cleanly with the Dividend Powerhouses theme of covered, consistent income streams above the 3% yield mark.
Sun Life Financial runs a broad mix of insurance, wealth and asset management businesses, drawing about CA$15.7b from Canada, CA$12.9b from the U.S., CA$7.7b from Sun Life Asset Management and CA$2.6b from Asia, with a market value near CA$62.9b.
"Strong growth across Asian markets, particularly in Individual Protection and wealth products, is expanding Sun Life's addressable market and creating significant new revenue sources. This is reinforced by double-digit sales and CSM growth in the region year-over-year."
The real test for Sun Life Financial’s dividend appeal comes from how one quiet pressure on its earnings efficiency eventually resolves.
That quiet drag on earnings is exactly what the full narrative for Sun Life Financial unpacks, showing how Sun Life Financial could turn it into accelerating income power for long term holders.

Canadian Tire Corporation (TSX:CTC.A)
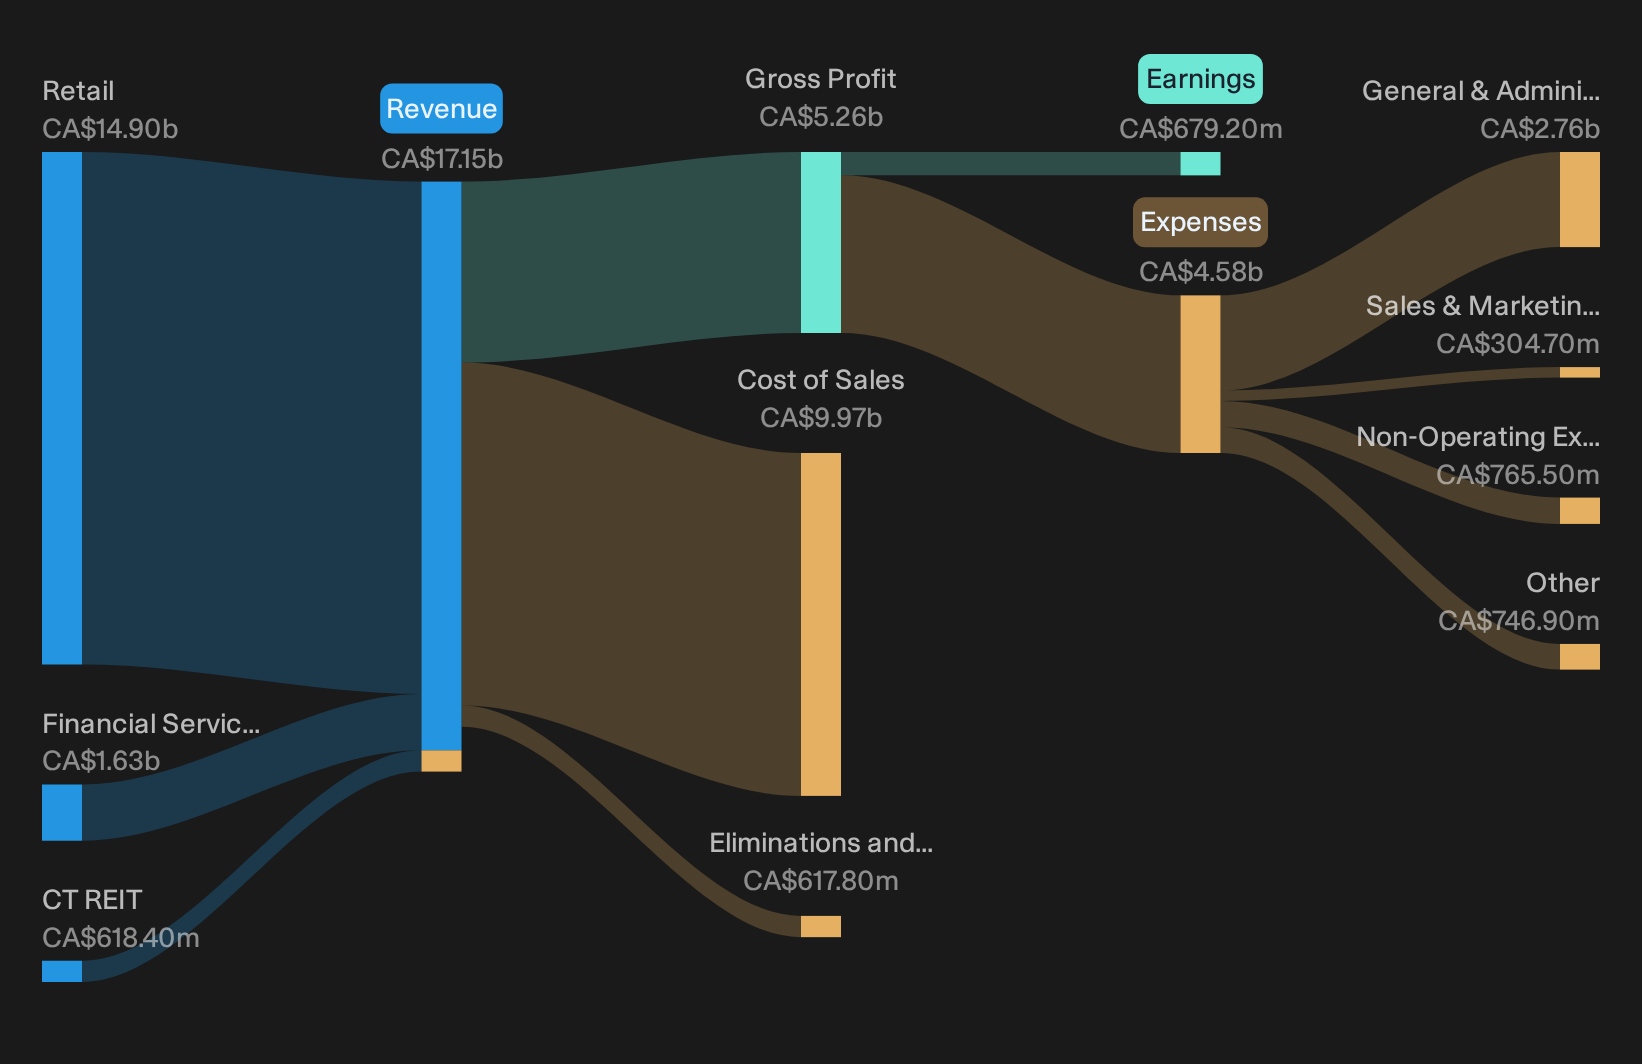
Canadian Tire Corporation ties into the Dividend Powerhouses idea through its CT REIT arm. Rent from Canadian Tire anchored properties helps underpin a regular payout even as the wider retail and financial services engine keeps evolving.
"Ongoing investments in store refreshes, loyalty programs, and supply chain optimization are expected to drive cost efficiencies over time; however, the current and projected increase in fixed and variable costs, combined with wage and utility inflation, could pressure net margins and delay anticipated operating leverage improvements."
The real story for Canadian Tire Corporation’s dividend strength now hinges on how one quiet shift in its cost structure lands over the next few years.
Canadian Tire Corporation is a broad retailer and financial services group in Canada, with most of its CA$14.9b in revenue coming from the Retail segment, plus CA$1.6b from Financial Services and about CA$618m from CT REIT. It carries a market value near CA$9.9b.
That quiet shift in costs is exactly what the full narrative for Canadian Tire Corporation unpacks, highlighting where Canadian Tire Corporation’s cash flows could decouple from near term pressures and begin to accelerate again.
Whitecap Resources (TSX:WCP)
Whitecap Resources is a Western Canada focused oil and gas producer whose upstream wells generate the cash flow that supports its Dividend Powerhouses profile. The business produced about CA$7.2b in oil and gas revenue, entirely from Canada, and carries a market value near CA$22.1b.
For income investors, Whitecap Resources matters because its monthly dividend is tied directly to the cash engine of its Western Canadian production, and recent operational progress is starting to reshape how durable that payout could look over time.
"Successful integration of Veren assets is resulting in early operational synergies, cost reductions, and improved capital efficiency, which are expected to unlock further sustainable cost savings and margin expansion over the next 6 to 12 months, directly supporting higher future earnings and free cash flow."
What really moves the needle for Whitecap Resources now is how one less visible shift in its capital mix ultimately feeds through to dividend breathing room.
That shift in capital mix is exactly what the full narrative for Whitecap Resources unpacks, showing how Whitecap Resources could turn integration gains into accelerating dividends with overlooked resilience.

Curious About Dividend Alternatives?
Fresh ideas can move fast. Some gain momentum quietly, then start flying once attention catches up. Scan these under the radar lists before the crowd and get in early.
- Hunt for resilient balance sheets and steady fundamentals using the curated list of solid balance sheet and fundamentals (7 results) while the market focus is still elsewhere and entry points have not been crowded.
- Spot early movers in nuclear infrastructure by running through the hand picked 19 nuclear energy infrastructure stocks before the theme gains wider attention and prices start reflecting it.
- Track trends in robotics and automation through the focused 92 robotics and automation stocks while these operators are still priced as niche stories rather than fully scaled businesses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com