


ArcBest (ARCB) On Tariff Relief Is The Pullback A Buying Opportunity
Tariff relief between the US and China, with a trade truce now running into early 2027 and a new Bilateral Trade Council planned, has turned attention to ArcBest (ARCB) as cross border freight expectations reset.
ArcBest’s share price has eased over the past quarter, with a 30-day share price return of down 6.94% and a 90-day move of down 11.47%, even after a strong year to date gain of 64.66% and a 1-year total shareholder return of 83.96%. This suggests recent momentum has cooled while longer term holders have still seen substantial gains as tariff relief reshapes expectations around cross border freight demand.
Scan for other freight and logistics stocks that could also react to tariff relief by reviewing the hand picked list of solid balance sheet and fundamentals (25 results).
ArcBest now sits between two stories: a freight platform tied to real cross border demand, and a stock that has cooled after a sharp run. Which one does the current valuation really reflect?
Most Popular Narrative: 26% Undervalued
ArcBest’s most followed valuation storyline puts fair value at $170.77 per share, compared with a last close of $127.07. This frames the recent pullback as a debate about how much of its freight recovery and technology push is already in the price.
Broad deployment of AI-driven optimization tools, such as real-time route and dock management systems, are driving measurable productivity gains and cost savings, which are expected to translate into improved net margins and operational earnings as automation and technology adoption intensify across the industry.
Find out how 4 investors see ArcBest as 26% undervalued.
Result: Fair Value of $170.77 (UNDERVALUED)
Still, if freight volumes stay soft or industry overcapacity keeps pricing under pressure, the ArcBest margin and earnings narrative could look too optimistic.
Find out about the key risks to this ArcBest narrative.
Another View On ArcBest’s Valuation
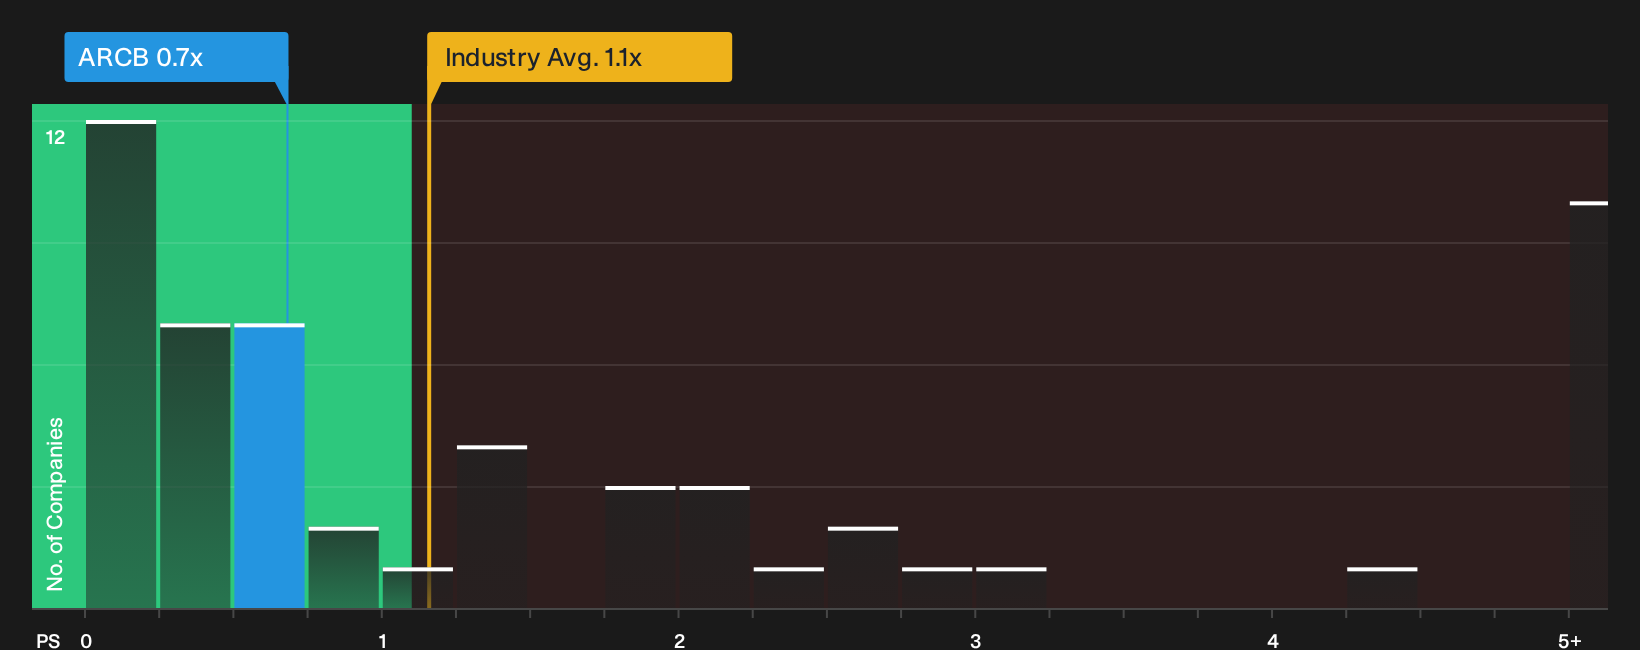
The fair value story around ArcBest looks very different when you switch from earnings forecasts to simple sales multiples. The stock trades on a P/S of 0.7x, which is below the US Transportation industry at 1.1x, yet slightly above its own fair ratio of 0.6x. This raises the question of whether the apparent discount is a margin of safety or a signal that expectations are already stretched.
To see how that gap between the current P/S and the fair ratio could resolve, and what the earnings path would need to look like to support either outcome, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on ArcBest’s outlook can be confusing, so move quickly, review the underlying data on risks and rewards, and weigh the 3 key rewards and 3 important warning signs.
Looking For More Investment Ideas Beyond ArcBest?
If ArcBest has sharpened your thinking on valuation and momentum, do not stop here. Broaden your watchlist with fresh ideas built from hard data.
- Explore potential upside in quality companies trading at a discount by scanning the 33 high quality undervalued stocks.
- Focus on resilience and sleep-better-at-night holdings by reviewing the 30 resilient stocks with low risk scores.
- Identify underfollowed opportunities with strong fundamentals before they gain wider attention through the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com