


Encompass Health (EHC) Could Be 16% Below Fair Value After New Hospital Expansion
Why recent hospital projects matter for Encompass Health stock
Encompass Health (EHC) has put fresh capacity expansion at the center of its story, with a new inpatient rehabilitation hospital now open in Pennsylvania and two more projects announced in Texas.
These hospital projects are landing at a time when Encompass Health’s share price momentum has picked up, with a 90 day share price return of 22.69% and a year-to-date share price return of 16.59%, while the 1 year total shareholder return is slightly negative and the 5 year total shareholder return is 122.57%.
Scan how Encompass Health’s expansion compares with other hospital and healthcare operators by checking our hand picked list of solid balance sheet and fundamentals (25 results) for potential ideas in the same space.
Bulls point to Encompass Health’s expansion push and recent share price strength. Bears focus on execution risk and what is already implied by the move. Which case does the current valuation lean toward?
Most Popular Narrative: 16% Undervalued
Against a last close of $124.02, the most widely followed narrative pegs Encompass Health’s fair value at $148.17. This frames recent hospital openings as part of a broader capacity led story rather than a one off expansion.
Ongoing expansion of Encompass Health’s inpatient rehabilitation footprint through de novo hospitals, bed additions at high occupancy sites, and small format facilities, supported by a disclosed multi year pipeline and high returns on these projects, points to further discharge volume growth that can lift net operating revenue and EBITDA.
See why 5 investors see Encompass Health as 16% undervalued.
Result: Fair Value of $148.17 (UNDERVALUED)
Still, the Encompass Health story can be dented if tougher Medicare Advantage authorization trends deepen or if new hospital projects earn weaker returns than management expects.
Find out about the key risks to this Encompass Health narrative.
Another View: What Encompass Health’s P/E Is Telling You
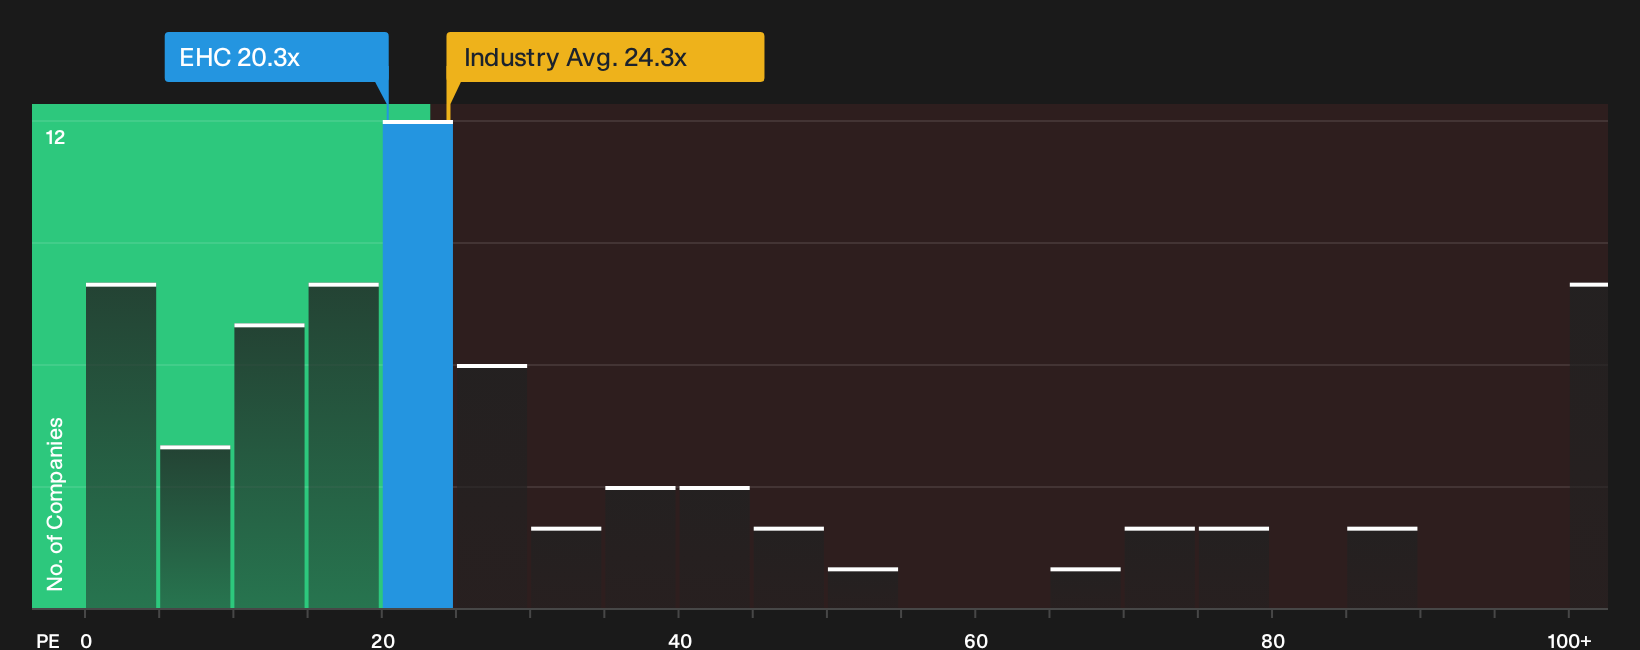
The first narrative leans on future earnings and cash flows to argue Encompass Health looks undervalued. A simpler lens tells a different story. At a P/E of 20.3x, the stock trades richer than its direct peers at 17.1x, even though it sits below the broader US Healthcare sector on 24.3x.
The fair ratio from Simply Wall St’s model is 25.5x, so the current 20.3x leaves a gap that could be read as either a margin of safety or a signal that expectations are already loaded into the price. Which camp you fall into depends on how much confidence you place in those forward earnings assumptions.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Encompass Health so far. If you want to move quickly and decide where you land, start by weighing its risks against its upside with 3 key rewards and 2 important warning signs.
Looking for more Encompass Health investment ideas?
If Encompass Health has your attention, do not stop with one ticker. Broaden your watchlist now so you are not chasing the next move late.
- Target underpriced quality by scanning companies that combine strong fundamentals with cheaper valuations through the 33 high quality undervalued stocks.
- Prioritize resilience by focusing on businesses with sturdier finances using the 30 resilient stocks with low risk scores.
- Hunt for fresh opportunities among financially sound operators that fewer investors track via the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com