


Dividend Raise Could Be A Key Signal For Fifth Third Bancorp Stock (FITB)
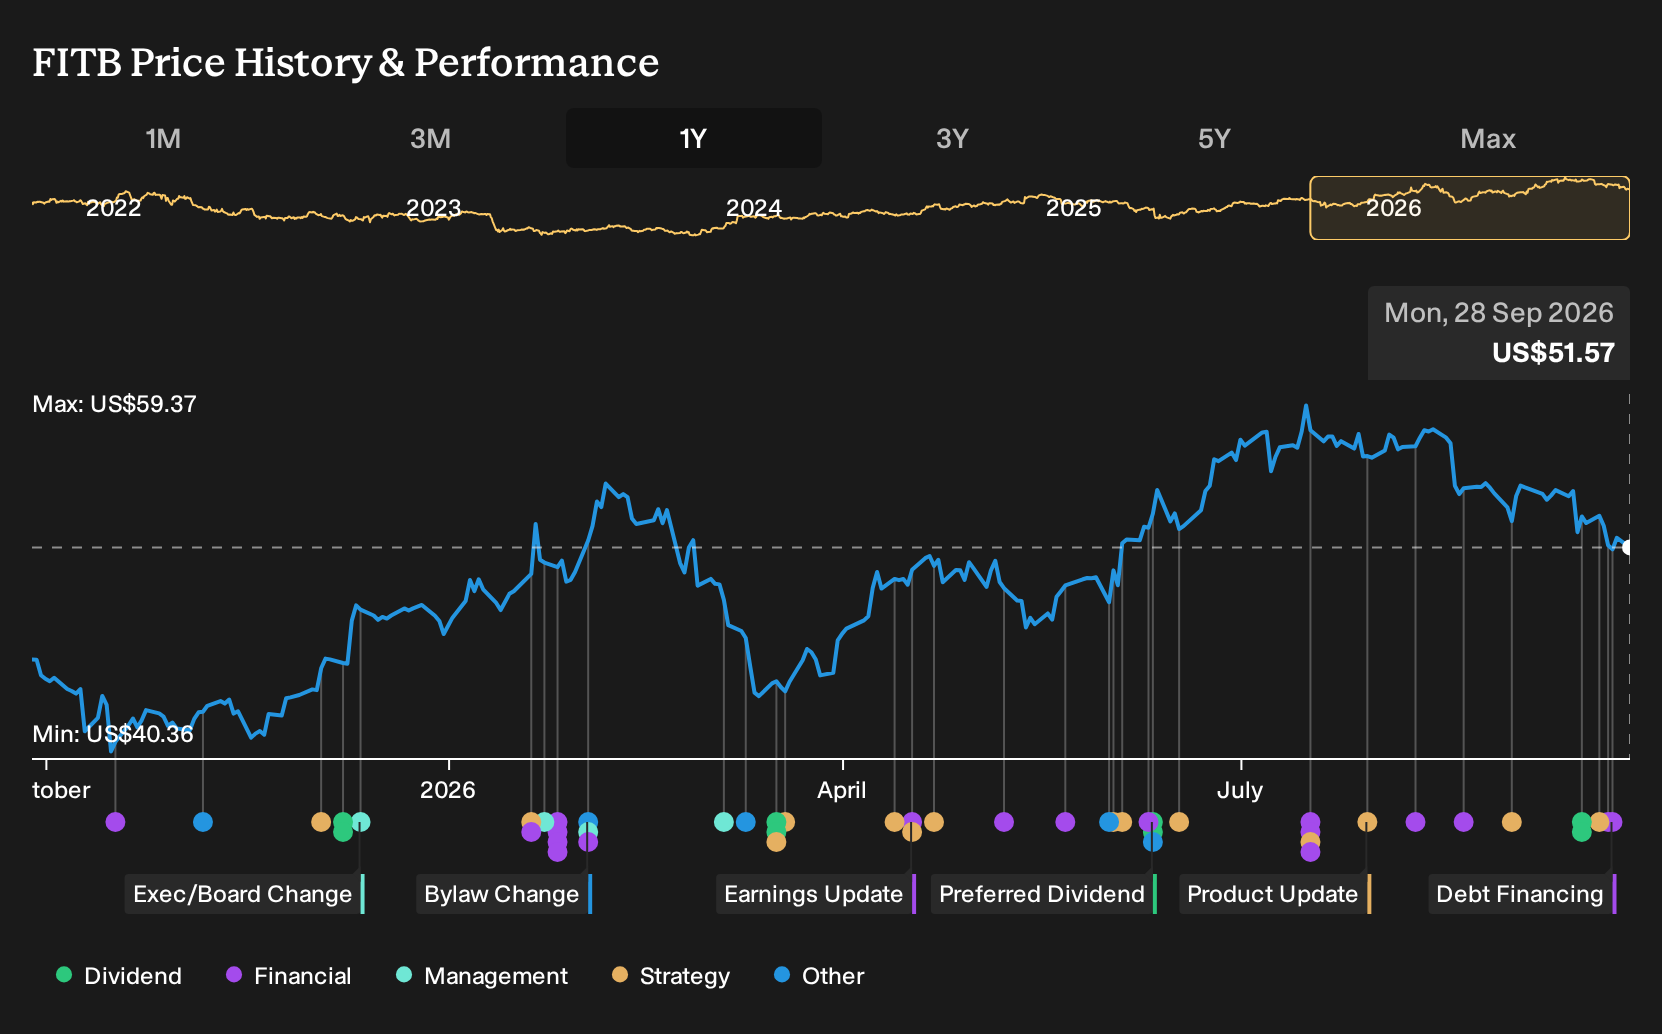
- Fifth Third Bancorp raised its quarterly common dividend for the third quarter of 2026 to US$0.42 per share, payable on October 15 to shareholders of record on September 30, and also declared cash dividends across multiple preferred stock series with payment dates on September 30 and October 1.
- The 5% increase in the common payout, alongside ongoing preferred dividends, highlights how Fifth Third Bancorp is currently using its capital position to support consistent cash returns to both common and preferred equity holders.
- We will now look at how this latest 5% dividend increase shapes Fifth Third Bancorp's broader investment narrative and execution risks.
Scan how Fifth Third Bancorp’s dividend and debt moves compare with other banks using our curated list of 6 dividend fortresses that prioritize consistent cash returns.
Fifth Third Bancorp Investment Narrative Recap
For an investor to stay with Fifth Third Bancorp, there needs to be confidence that deposit-led funding, Comerica integration work and technology spending can keep feeding earnings and dividend support without being eroded by rising deposit costs or service issues. The recent dividend lift fits that picture, while the senior note redemption and exchange do not materially change the near term operating story.
The bigger swing factor in the coming quarters still sits in execution. Management needs to keep expanding in Southeast and Southwest markets, bed down Comerica systems without further online glitches, and absorb the loss of residential solar tax credits without a prolonged drag on fee income.
The debt redemption notice on the US$500 million 1.707% Senior Notes due 2027 looks most relevant here. Redeeming this issue at par plus accrued interest simplifies the balance sheet and modestly reshapes the funding mix without introducing new complexity for investors watching capital and liquidity.
Combined with the recent exchange of restricted senior notes into registered securities, this step keeps the capital structure tidy as the Comerica merger and branch expansion continue. For you, the key link to catalysts is simple. A cleaner liability stack can make it easier to judge how much headroom Fifth Third Bancorp has for technology spend, integration risk and ongoing dividends.
Fifth Third Bancorp’s current analyst narrative points to revenues of US$16.4b and earnings of US$4.3b by 2029, built on assumed revenue growth of 17.6% a year and an earnings increase of US$2.1b from US$2.2b today.
Uncover why Fifth Third Bancorp's fair value indicates a 22% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span roughly US$62.65 to about US$97.16 per share, so private investors clearly do not agree on where Fifth Third Bancorp should trade. When you set that against the Comerica merger, the debt clean up, and the branding push in Detroit, you can arrive at very different interpretations of future execution. Use these gaps to stress test your own view, not replace it.
Explore 3 other Fifth Third Bancorp fair value estimates, including one that suggests it could be worth just $62.65!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Fifth Third Bancorp research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Fifth Third Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fifth Third Bancorp's overall financial health at a glance.
Looking For More Investment Ideas Beyond Fifth Third Bancorp?
If you want to pressure test your view on Fifth Third Bancorp, it can help to line it up against other opportunities with different risk and income profiles. The Simply Wall St Screener lets you quickly filter for traits that matter to you, whether that is balance sheet strength, income resilience, or quieter, under-followed stories.
- If capital protection comes first for you, start with a set of companies that screen well on downside risk using our 30 resilient stocks with low risk scores and compare how their profiles differ from Fifth Third Bancorp.
- If you care most about resilient cash flows, line up Fifth Third Bancorp against businesses that also combine strong payouts with staying power by reviewing our curated 6 dividend fortresses.
- If you are hunting for less crowded opportunities, broaden your watchlist with a focused 16 high quality undiscovered gems that score well on fundamentals but attract less attention from the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com