


Is ONE Gas (OGS) Undervalued After Its Recent Slide?
Conference spotlight and recent stock pressure
ONE Gas (OGS) is set to appear at Wolfe Research’s virtual Utilities, Midstream and Clean Energy Conference on September 29, 2026, as the shares face recent selling pressure.
Recent selling has pushed ONE Gas to US$71.66, with the 30-day share price return down 9.83% and the year-to-date share price return down 7.44%, even though the 3-year total shareholder return of 21.92% and 5-year total shareholder return of 26.72% still reflect a positive longer-term result. Short-term momentum has clearly faded, and the pullback arrives just as the company is being highlighted for low leverage, earnings growth, and dividend consistency. This may be reshaping how investors weigh its growth potential against perceived risk.
Scan beyond ONE Gas and compare it with a hand picked group of regulated utilities that combine earnings strength with balance sheet resilience in the 30 resilient stocks with low risk scores.
ONE Gas looks like a sturdy regulated utility on the fundamentals, yet the recent slide to US$71.66 raises a sharper question: Is this still a strong business at a stretched price, or a solid franchise on sale?
Most Popular Narrative: 21% Undervalued
ONE Gas last closed at $71.66, while the most followed valuation narrative pegs fair value at $90.22 using a 7.11% discount rate. That gap puts the current pullback in sharp relief for anyone weighing long term earnings power against today’s weaker share price.
Sustained population growth and urbanization in Texas, Oklahoma, and Kansas is fueling above-trend new customer additions, including a 9% year-over-year jump in new meters installed, that supports persistent, organic top-line revenue growth.
The shift toward electrification is gradual, with natural gas remaining the preferred and affordable solution for heating, cooking, and industrial use in ONE Gas's core regions; this underpins stable customer retention and long-term regulated revenue visibility.
See why 0 investors see ONE Gas as 21% undervalued.
Result: Fair Value of $90.22 (UNDERVALUED)
Still, the bullish narrative on ONE Gas hinges on regulators continuing to allow timely cost recovery and on capital spending not squeezing free cash flow or margins.
Find out about the key risks to this ONE Gas narrative.
Another view on ONE Gas valuation
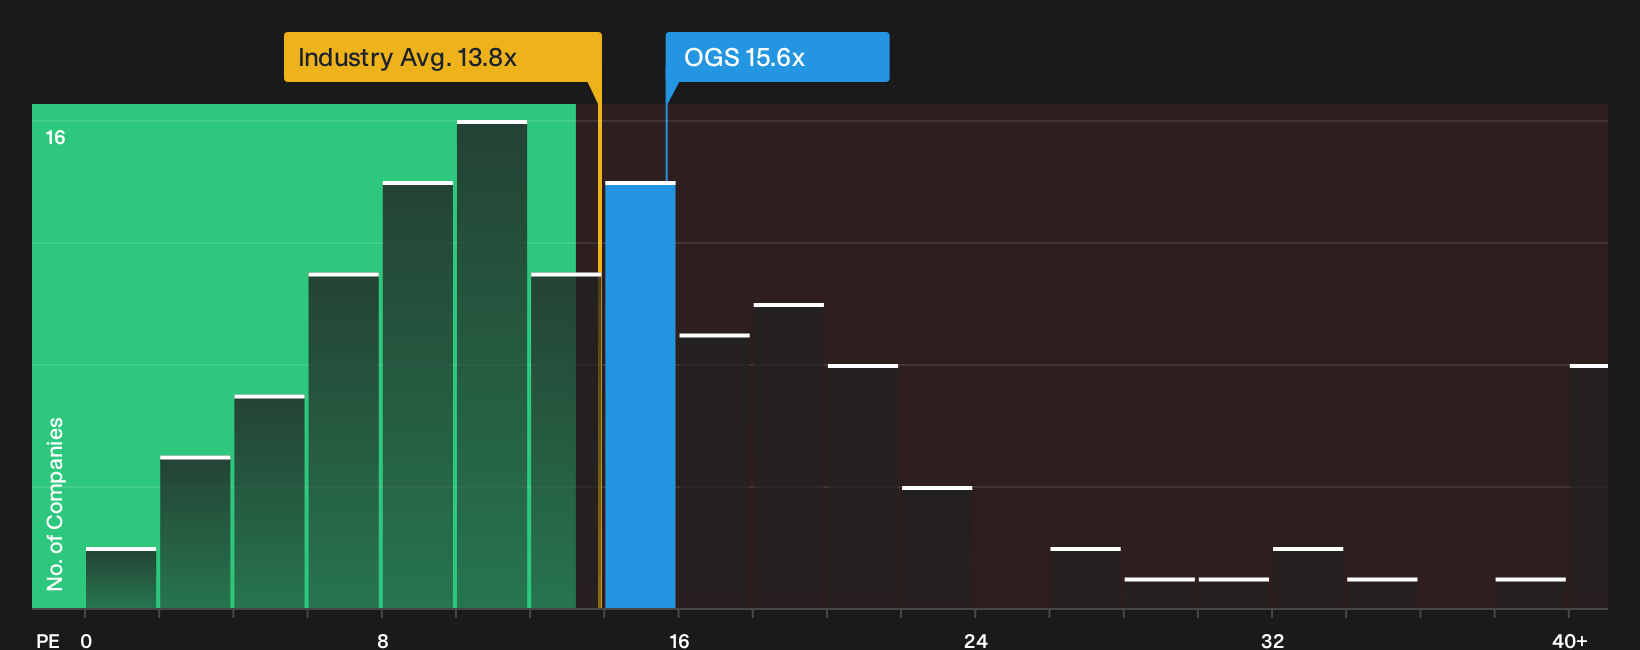
Analysts see ONE Gas as undervalued on future earnings, but the simple P/E check tells a tougher story. The stock trades on 15.6x earnings, above both US and global gas utilities averages of 13.3x and 13.8x, while the fair ratio is estimated at 18.6x. That premium versus peers, together with the discount to the fair ratio, leaves you weighing whether this reflects a quality premium or suggests limited upside if sentiment cools.
To see how this earnings multiple compares with the sector and what that price gap could mean for your risk tolerance, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages around ONE Gas can be confusing, so move quickly, review the latest numbers and weigh the upside against the drawbacks yourself. To see both sides laid out clearly, start with the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond ONE Gas?
If ONE Gas has sharpened your thinking about value, do not stop here. Broader ideas often come from comparing different business models and risk profiles.
- Target a cleaner risk profile by scanning a list of solid balance sheet and fundamentals (25 results) that can help you focus on companies with financial room to breathe.
- Hunt for pricing gaps by reviewing a 33 high quality undervalued stocks that highlights businesses where fundamentals and share prices appear out of sync.
- Stack potential income streams by assessing a 6 dividend fortresses that concentrates on higher yielding payers with robust support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com