


China Resources Land (SEHK:1109) Could Be 11% Below Fair Value Following August Sales Update
Why China Resources Land is back on investors’ radar
China Resources Land (SEHK:1109) has drawn fresh attention after reporting August contracted sales of about RMB 18.50b, along with solid recurring income figures and brisk unit take up at The Sterling II project in Hong Kong.
Investors have reacted to these sales updates with a 2.86% 1 day share price gain to HK$29.46. However, the stock is still down 11.21% on a 30 day share price basis, while posting a 6.28% year to date share price return and a 5 year total shareholder return of 15.09%. This suggests recent momentum has softened after a longer stretch of more positive compounding.
Capitalize on the renewed interest in China Resources Land by scanning a curated set of real estate and asset-backed plays through list of solid balance sheet and fundamentals (202 results).China Resources Land has just bounced on fresh sales news, yet the share price is still below where it traded a month ago. Is it worth stepping in now, or does patience offer a better entry as valuation comes into focus?
Price-to-earnings of 7.7x: Is it justified?
China Resources Land last closed at HK$29.46, and on a P/E of 7.7x it screens as inexpensive compared with both its peers and the wider Hong Kong real estate sector.
The P/E ratio compares the share price with earnings per share, so it reflects how much investors are willing to pay for each dollar of current profit. For a large property developer and landlord like China Resources Land, this gauge tends to capture expectations around future income from contracted sales, rental streams and management fees in a single, easy to track figure.
On that measure, the stock trades on a clear discount. Management is forecast to grow earnings by 6.3% per year, while the revenue line is projected to edge down by 0.5% a year, and yet the market is paying only 7.7x earnings versus a Hong Kong real estate peer average closer to 15.7x. The SWS fair P/E estimate of 13.9x is also well above where the shares currently change hands, which signals a level the valuation could potentially gravitate toward if sentiment on earnings quality and balance sheet risk improves.
Explore the SWS fair ratio for China Resources Land.
Result: Price-to-earnings of 7.7x (UNDERVALUED)
Still, China Resources Land carries risks around declining annual revenue growth and concentrated exposure to the Chinese Mainland, which could pressure sentiment if conditions weaken further.
Find out about the key risks to this China Resources Land narrative.
Another view on China Resources Land’s value
While the P/E comparison paints China Resources Land as inexpensive, the SWS DCF model also points to the shares trading below estimated future cash flow value, with a fair value of about HK$32.78 against the current HK$29.46. If both earnings and cash flow signals lean cheap, what is the market still worried about?
Look into how the SWS DCF model arrives at its fair value.
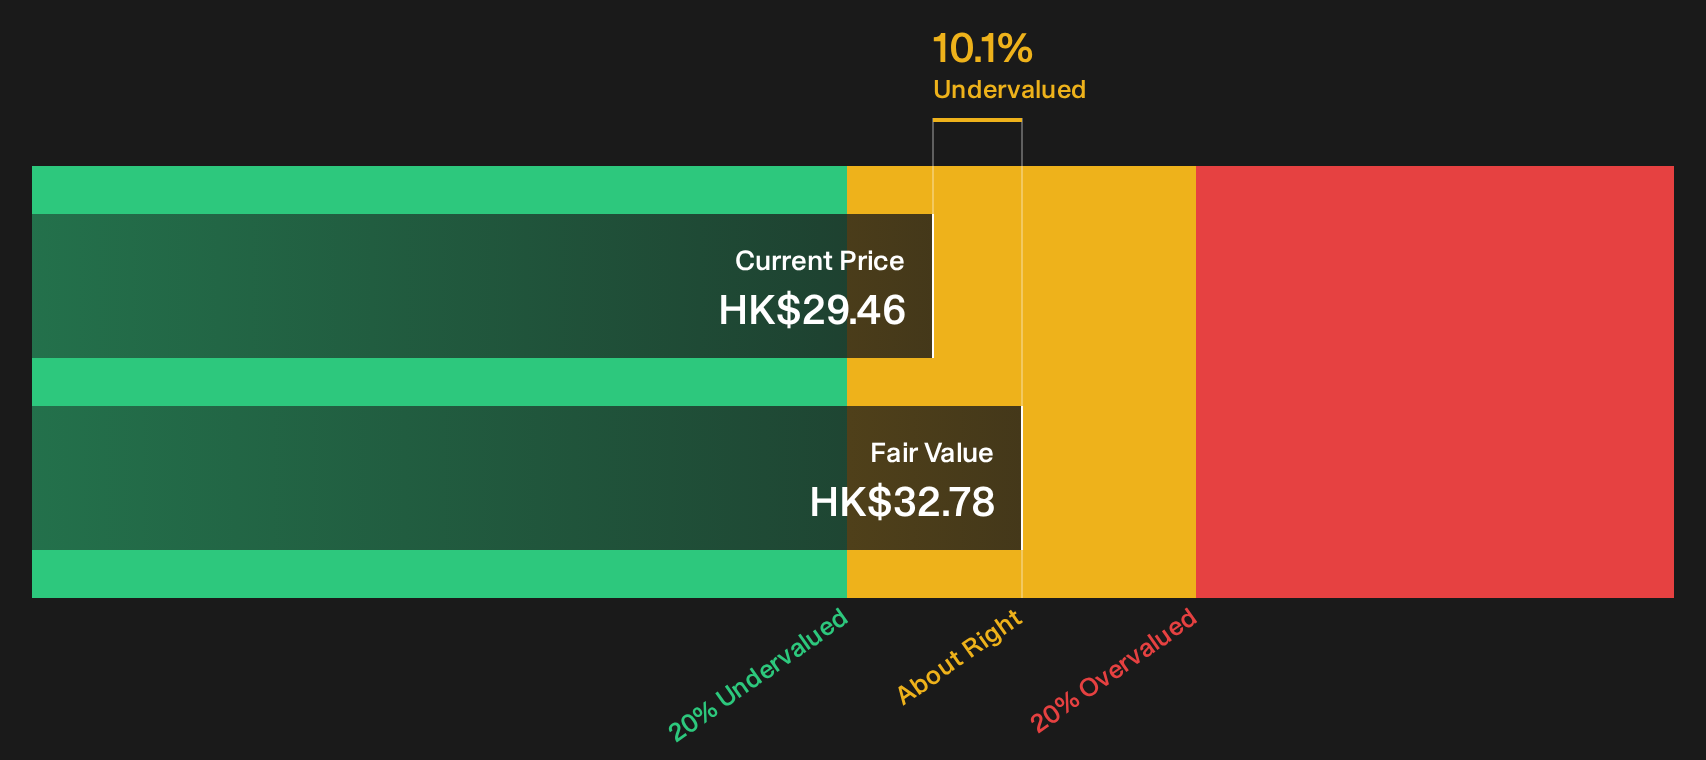
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Resources Land for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 198 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on China Resources Land can either be a warning or an opening, so move quickly to test the data yourself and weigh the trade off between concerns and upside potential with 5 key rewards and 2 important warning signs
Looking for more investment ideas beyond China Resources Land?
You have seen how China Resources Land stacks up on value and risk. Next, widen the field and pressure test your portfolio against other opportunities.
- Target potential bargains with strong fundamentals by scanning a curated set of quality opportunities through 198 high quality undervalued stocks.
- Build a steadier income stream by reviewing companies that meet strict payout and resilience criteria using the 166 dividend fortresses.
- Dial down portfolio stress by focusing on businesses screened for financial strength and lower risk profiles with the 221 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com