


3 Canadian Value Stocks Trading Up To 42% Below Fair Value
Rising bond yields are drawing attention back to income and capital protection, which puts steady cash generation under a brighter spotlight. Investors focused only on headline share moves risk missing Canadian businesses that quietly throw off strong cash each year while trading below their estimated worth. This piece looks at three ideas from our cash flow value screen and explains why each might appeal to patient, valuation driven investors.
The three stocks highlighted next are only a small sample from this cash flow focused list, with the full screen surfacing 3 more businesses with equally compelling narratives that are not covered here. To identify and analyze those opportunities alongside the ideas below, head straight into the Undervalued Stocks Based On Cash Flows screener.
Lundin Gold (TSX:LUG)
Overview: Lundin Gold is a Vancouver based miner. Its Fruta del Norte operation in Ecuador generates the cash flows underpinning its valuation.
Operations: Lundin Gold generates about US$2.0b in revenue from its 100% owned Fruta del Norte mine in Ecuador.
Market Cap: CA$22.1b
Lundin Gold appeals to cash flow focused investors because a single high grade mine is throwing off meaningful income that SWS models still view as undervalued.
"The current valuation seems to price in a seamless and rapid expansion of the company's resource base and mine life, particularly through ongoing drilling at FDNS, FDN East, and the new porphyry corridor. This optimism assumes material reserve additions and life extension, which, if not realized, could lead to future revenue disappointment post-2030."
For anyone weighing Lundin Gold, a single unresolved pressure on future cash generation could be the swing factor for long term returns.
If that single pressure point on future cash has your attention, read the full narrative for Lundin Gold to see how Lundin Gold’s upside and risks really stack up.
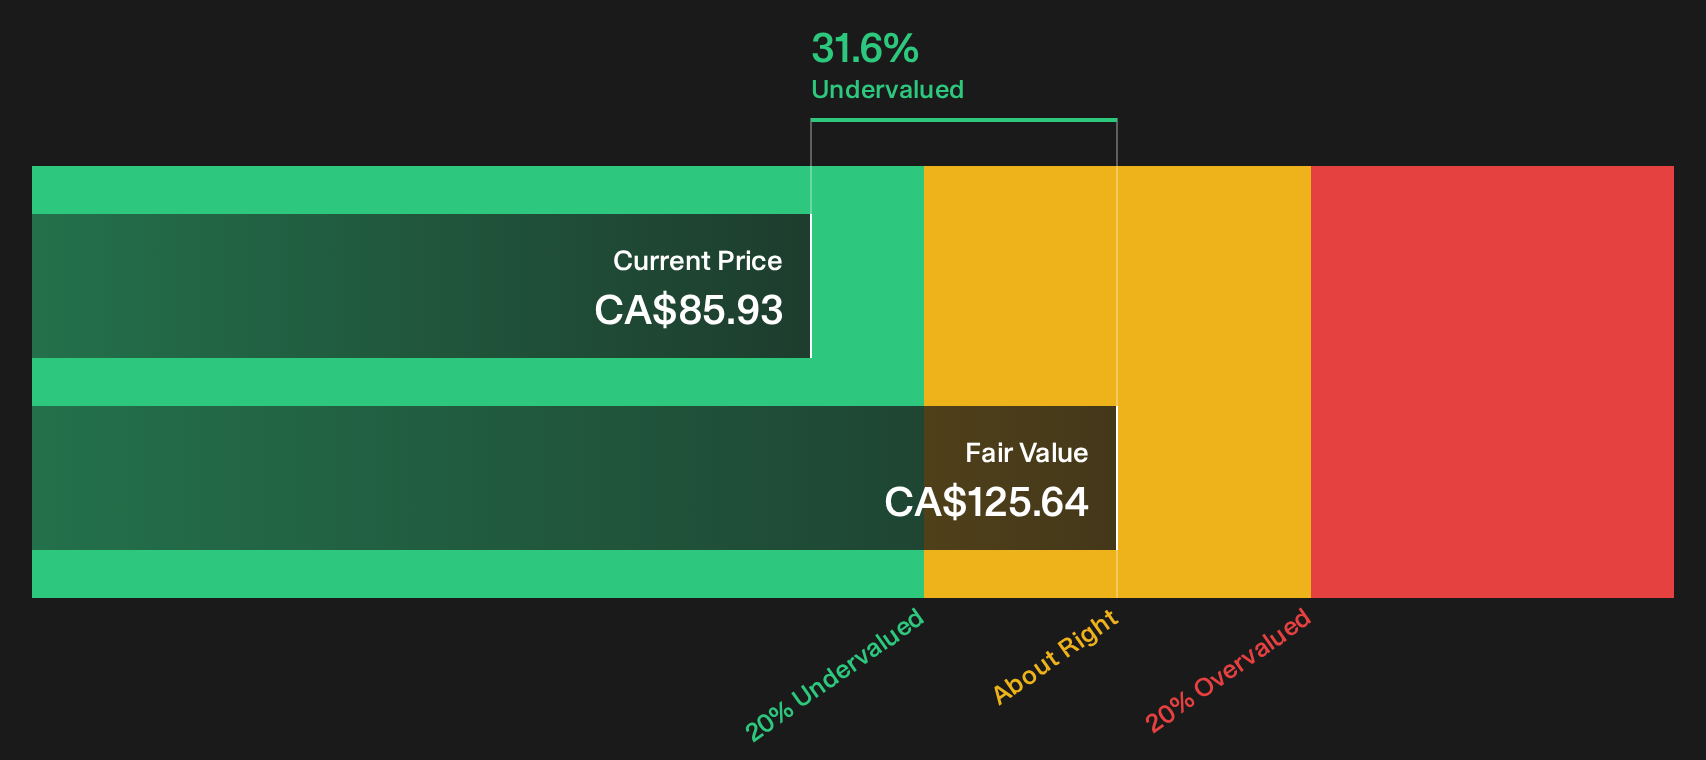
Savaria (TSX:SIS)
Overview: Savaria helps elderly and physically challenged people stay mobile and live at home by supplying residential and commercial accessibility equipment worldwide.
Operations: Savaria generates about CA$739 million from Accessibility, including adapted vehicles, and CA$209 million from Patient Care across Canada, the United States, Europe and beyond.
Market Cap: CA$2.1b
Savaria fits this cash flow focused list because its Accessibility products and related services tend to create steady, repeatable cash generation that can be assessed through discounted cash flow work rather than short term trading swings.
"Ongoing global demographic shifts, namely population aging and increased urban density, are expected to drive a sustained uptick in demand for home accessibility solutions (e.g., elevators, stairlifts), positioning Savaria for long-term revenue growth as these trends intensify."
What happens if one quiet pressure on Savaria’s ability to turn that demand into durable margins shifts even slightly against expectations.
If that margin pressure worries you, read the full narrative for Savaria to see how Savaria’s cash engine, balance sheet and valuation thesis could still be quietly accelerating.

Suncor Energy (TSX:SU)
Overview: Suncor Energy is an integrated Canadian producer that turns oil sands bitumen into refined fuels and petrochemical products for global markets.
Operations: Suncor Energy generates about CA$26.9b from Oil Sands and CA$36.8b from Refining and Marketing, partly offset by corporate eliminations.
Market Cap: CA$113.0b
Suncor Energy fits this cash flow focused screen because its oil sands and refining complex generates sizeable operating cash that discounted cash flow (DCF) models can scrutinize closely.
"Reliance on very high utilization of existing oil sands and refining assets, including refinery runs consistently at or above 100% and upgrader utilization above 100%, leaves little unused capacity to offset unplanned outages, which could pressure volumes and compress margins if reliability slips from current record levels."
The long term cash flow profile for Suncor Energy may depend on how this gradually building pressure affects future margins and payout capacity.
That pressure on future payouts is exactly what the full narrative for Suncor Energy unpacks, separating reliability worries from where Suncor Energy’s cash machine could still be quietly accelerating.

Seeking Fresh Alternatives Beyond Today
Fresh ideas move first. While screens stay quiet, potential breakouts build momentum under the radar for now. Do not get caught watching from the sidelines, get in early.
- Spot potential turnaround leaders before they catch headlines by scanning the 9 high quality undiscovered gems curated for strong fundamentals and cleaner balance sheets.
- Target resilient income streams while yields are still adjusting by reviewing the 1 dividend fortresses designed for higher payout strength and financial durability.
- Ride structural demand in critical materials by checking the 16 top copper producer stocks built around producers with meaningful exposure to long term copper needs.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com