


Asian Stocks Estimated Below Intrinsic Value In September 2026
In September 2026, Asian markets have been navigating a complex landscape marked by inflation concerns and fluctuating bond yields, echoing global economic uncertainties. Amidst this backdrop, identifying stocks that are potentially undervalued can offer investors opportunities to capitalize on discrepancies between market prices and intrinsic values.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Shizuki Electric (TSE:6994) | ¥1202.00 | ¥2303.86 | 47.8% |
| Rakus (TSE:3923) | ¥1036.00 | ¥2062.91 | 49.8% |
| Marco Polo Marine (SGX:5LY) | SGD0.128 | SGD0.24 | 46.4% |
| Ichikoh Industries (TSE:7244) | ¥571.00 | ¥1074.41 | 46.9% |
| Double Medical Technology (SZSE:002901) | CN¥41.30 | CN¥79.52 | 48.1% |
| Dongwon Industries (KOSE:A006040) | ₩36250.00 | ₩71386.75 | 49.2% |
| China Coal Energy (SEHK:1898) | HK$10.66 | HK$20.07 | 46.9% |
| Cheil Worldwide (KOSE:A030000) | ₩17810.00 | ₩34157.21 | 47.9% |
| BuySell TechnologiesLtd (TSE:7685) | ¥2788.00 | ¥5570.48 | 50% |
| AK Medical Holdings (SEHK:1789) | HK$4.84 | HK$9.52 | 49.2% |
Let's review some notable picks from our screened stocks.
Ugreen Group (SZSE:301606)
Overview: Ugreen Group Limited designs, researches, produces, and sells consumer electronics products both in China and internationally, with a market cap of CN¥20.77 billion.
Operations: The company generates revenue of CN¥11.45 billion from its consumer electronics industry segment.
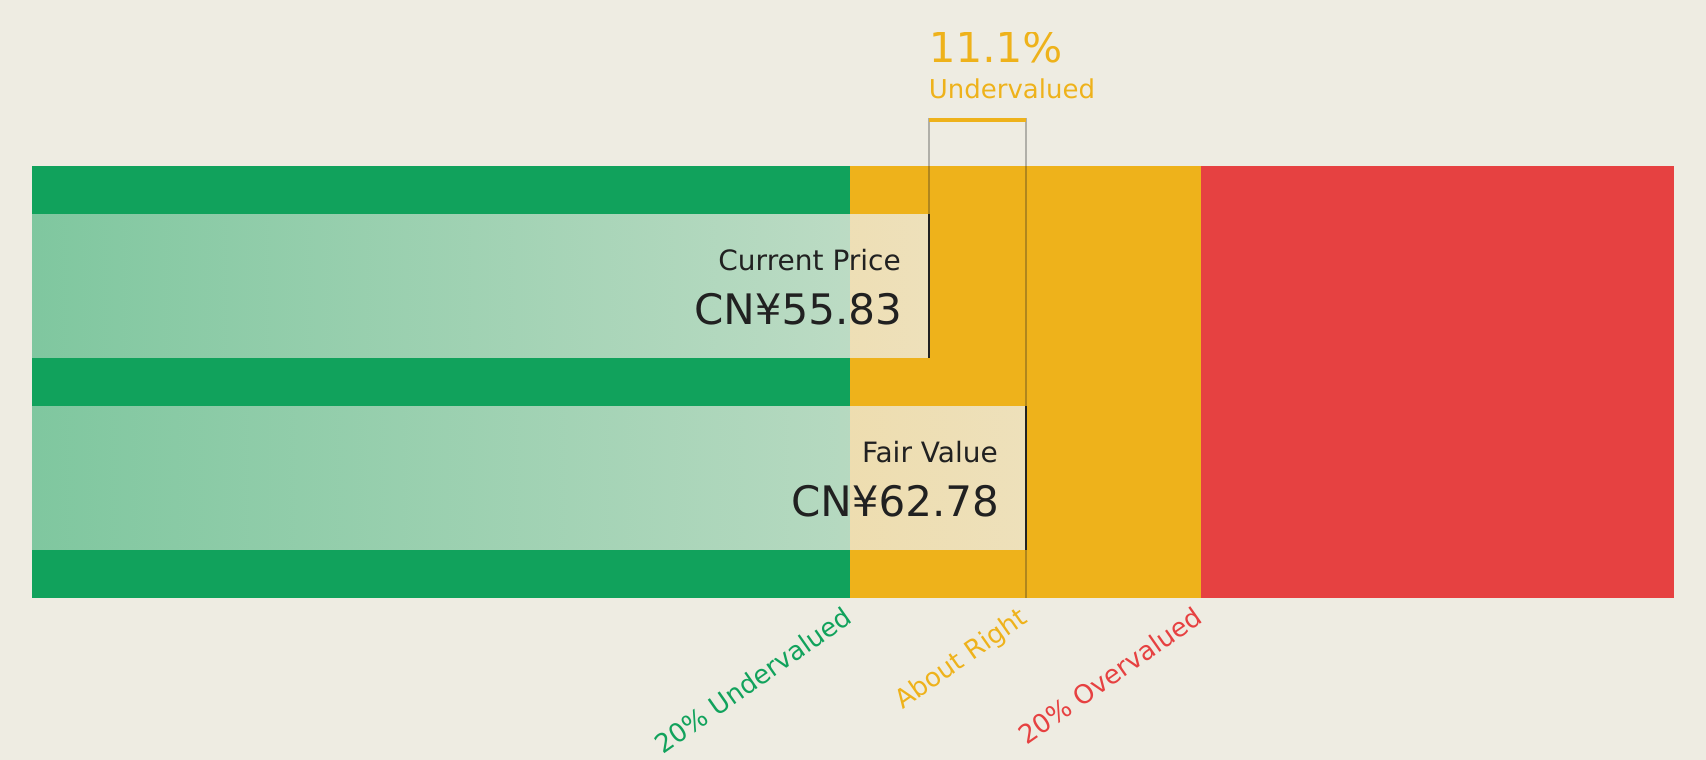
Estimated Discount To Fair Value: 22.3%
Ugreen Group is trading at a substantial discount to its estimated future cash flow value, offering potential for value investors. Recent earnings grew significantly, with revenue increasing from CNY 3.86 billion to CNY 5.82 billion year-over-year, and profits are expected to continue rising at over 25% annually. Despite a dividend yield of 1.2% not fully covered by free cash flows, the company shows strong revenue growth prospects and high-quality earnings, supported by strategic product expansions and innovations in the charging sector.
- The growth report we've compiled suggests that Ugreen Group's future prospects could be on the up.
- Click here and access our complete balance sheet health report to understand the dynamics of Ugreen Group.
Kyowa Kirin (TSE:4151)
Overview: Kyowa Kirin Co., Ltd. is involved in the research, development, manufacturing, and marketing of pharmaceuticals across Japan, the Americas, Europe, Asia, and internationally with a market cap of ¥1.18 trillion.
Operations: The company generates revenue primarily from its pharmaceuticals segment, totaling ¥529.80 billion.
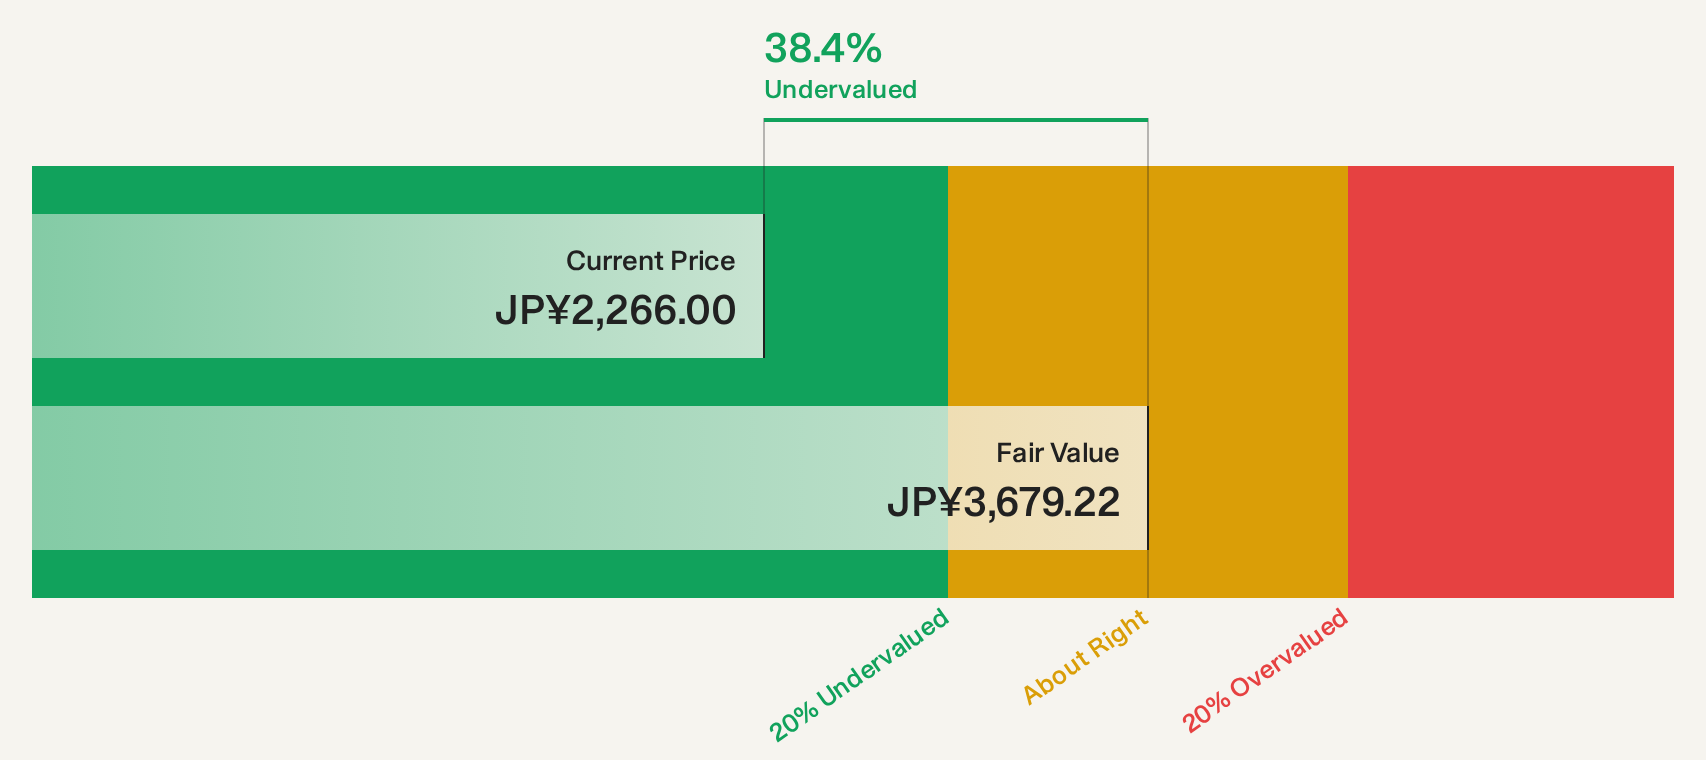
Estimated Discount To Fair Value: 39%
Kyowa Kirin trades at a notable discount to its estimated future cash flow value, with shares priced at ¥2,246 against a fair value of ¥3,679.22. Despite earnings growth forecasts below Japan's market average, recent financials show strong performance; half-year sales rose to ¥263.63 billion from ¥230.65 billion, and net income nearly doubled year-over-year to ¥30.62 billion. The FDA PreCheck Pilot Program selection could enhance manufacturing efficiency for biologics in the U.S., potentially strengthening future cash flows.
- Our expertly prepared growth report on Kyowa Kirin implies its future financial outlook may be stronger than recent results.
- Take a closer look at Kyowa Kirin's balance sheet health here in our report.
BuySell TechnologiesLtd (TSE:7685)
Overview: BuySell Technologies Co., Ltd., along with its subsidiaries, operates a reuse business specializing in kimonos and branded items in Japan, with a market capitalization of ¥172.45 billion.
Operations: The company generates revenue primarily from its reuse business for kimonos and branded products, amounting to ¥124.96 billion.
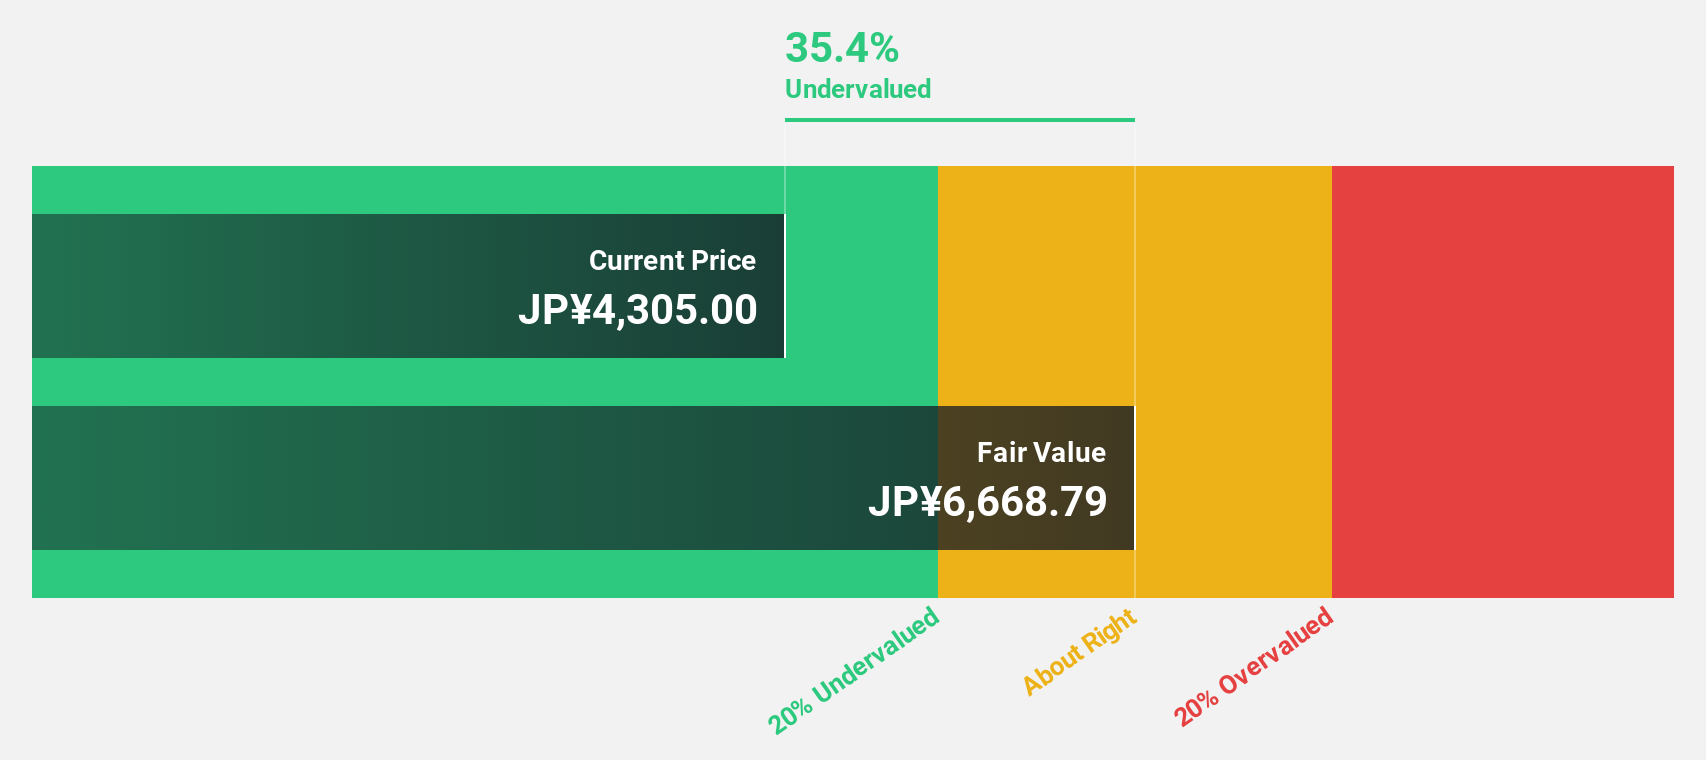
Estimated Discount To Fair Value: 50%
BuySell Technologies is trading at a significant discount to its estimated future cash flow value, with shares priced at ¥2,788 against a fair value of ¥5,570.48. The company has revised its earnings guidance upward due to improved tax calculations and integration impacts, forecasting profit growth of 24.9% annually—outpacing the Japan market average. Despite recent share price volatility, BuySell's strong cash flow potential and strategic acquisitions position it as an attractive investment in Asia's undervalued stock landscape.
- Insights from our recent growth report point to a promising forecast for BuySell TechnologiesLtd's business outlook.
- Dive into the specifics of BuySell TechnologiesLtd here with our thorough financial health report.
Taking Advantage
- Investigate our full lineup of 81 Undervalued Asian Stocks Based On Cash Flows right here.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Streamline your investment strategy with Simply Wall St's app for free and benefit from extensive research on stocks across all corners of the world.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com