


Cheniere Energy (LNG) Could Be 13% Undervalued On Sabine Pass Tax Break
Cheniere Energy (LNG) just cleared an important local hurdle for its US$6b Sabine Pass expansion, as Louisiana authorities backed mega project status that could bring a US$138m property tax break.
Cheniere Energy’s recent regulatory updates and the Sabine Pass tax incentive arrive after a strong run, with the share price up 36.32% year to date and a 90 day share price return of 12.82%. The 5 year total shareholder return of 177.05% reflects longer term momentum that investors will weigh against recent short term share price softness.
Scan opportunities beyond Cheniere Energy by reviewing a hand picked 33 high quality undervalued stocks that combine resilient cash flows with balance sheets built to support multi year growth plans.
The rally in Cheniere Energy has already rewarded investors who were on board earlier in the year, while fresh tax relief and expansion plans keep the story live. Does the balance of risk and reward still lean toward new buyers once valuation is in focus?
Most Popular Narrative: 13% Undervalued
Cheniere Energy’s most followed narrative pegs fair value at $309.95 per share, above the recent close of $269.65. This puts the Sabine Pass tax break into a broader valuation story rather than a one off headline.
The highly contracted nature of Cheniere Energy’s LNG platform through 2030 and into 2035, combined with an investment grade credit profile and a capital return program that targets dividend growth and share repurchases, is set to keep a large portion of future EBITDA and distributable cash flow tied to recurring, contracted revenue.
See why 68 investors see Cheniere Energy as 13% undervalued.
Result: Fair Value of $309.95 (UNDERVALUED)
Still, the Cheniere Energy narrative can be knocked off course if LNG linked derivatives keep driving large swings in reported earnings, or if the US$370m tax credit probe bites into future cash available for shareholders.
Find out about the key risks to this Cheniere Energy narrative.
Another View On Cheniere Energy’s Valuation
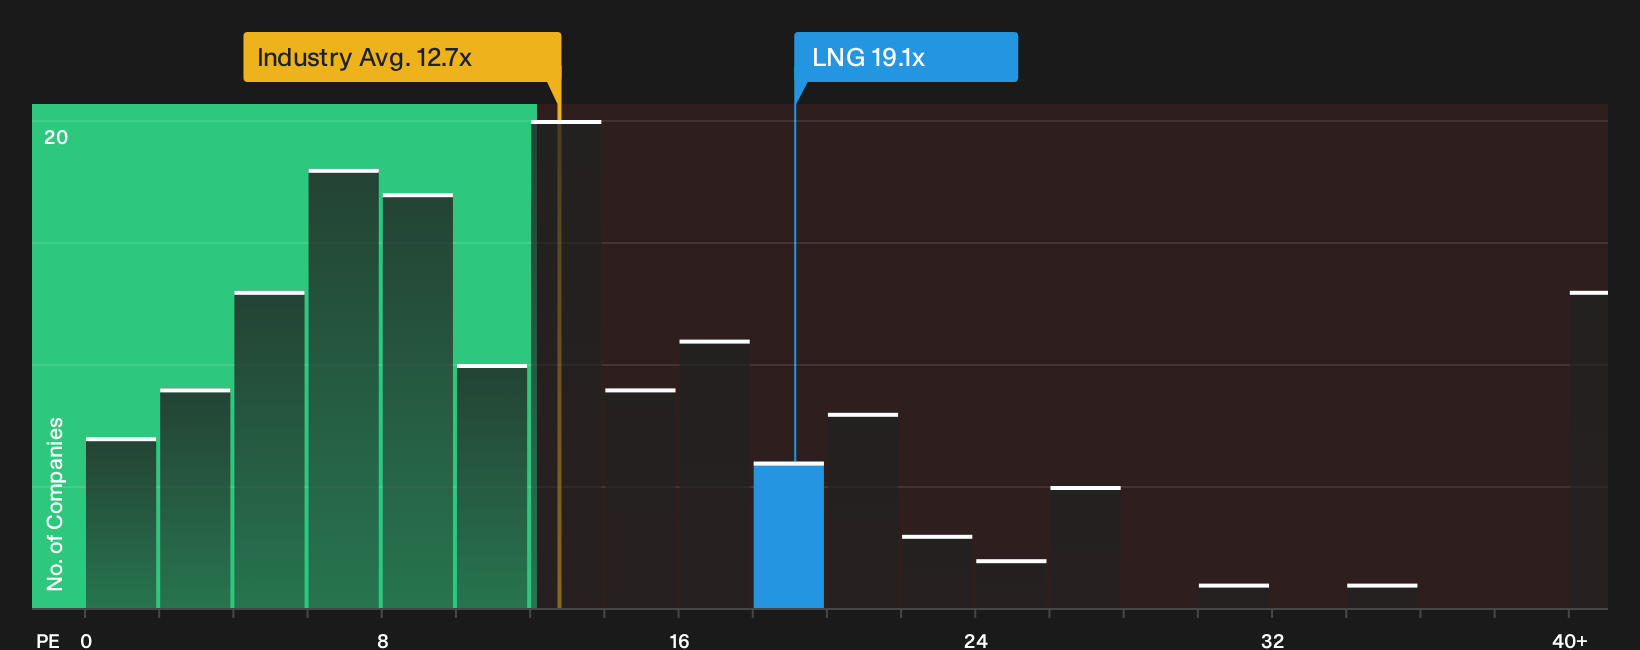
Analyst fair value work paints Cheniere Energy as undervalued, yet the current $269.65 price sits on a P/E of 19.1x. That is richer than the US Oil and Gas sector at 12.7x and slightly above peers at 18.1x, while still below a fair ratio of 22.4x. This raises the question of whether the stock is quietly priced for perfection or simply carrying a premium for quality earnings and board oversight.
For a closer look at what this pricing gap could mean in practice, including where the market might shift the ratio over time, check the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Cheniere Energy can pull you in either direction, so move quickly and test the story against the underlying data yourself. The clearest way to balance the concerns against the potential upside is to review the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Cheniere Energy?
If Cheniere Energy has sharpened your focus on valuation and risk, do not stop there. Use targeted stock lists to pressure test your thesis and uncover fresh opportunities before the crowd catches on.
- Target strong income potential by scanning a curated group of reliable payers through the 7 dividend fortresses.
- Hunt for quality at a discount by reviewing a hand picked 33 high quality undervalued stocks that pair solid fundamentals with appealing prices.
- Zero in on financial resilience by checking a list of solid balance sheet and fundamentals (24 results) that highlights businesses built to handle tougher conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com