


Jefferies (NYSE:JEF) Posts Better-Than-Expected Sales In Q3 CY2026
Investment banking firm Jefferies Financial Group (NYSE:JEF) reported revenue ahead of Wall Street’s expectations in Q3 CY2026, with sales up 8.5% year on year to $2.22 billion. Its GAAP profit of $1.08 per share was 8.8% above analysts’ consensus estimates.
Is now the time to buy Jefferies? Find out by accessing our full research report, it’s free.
Jefferies (JEF) Q3 CY2026 Highlights:
- Revenue: $2.22 billion vs analyst estimates of $2.2 billion (8.5% year-on-year growth, 1.1% beat)
- Pre-tax Profit: $351 million (15.8% margin)
- EPS (GAAP): $1.08 vs analyst estimates of $0.99 (8.8% beat)
- Tangible Book Value per Share: $35.21 vs analyst estimates of $34.99 (0.6% beat)
- Market Capitalization: $10.99 billion
Company Overview
Tracing its roots back to 1962 and rebranded from Leucadia National Corporation in 2018, Jefferies Financial Group (NYSE:JEF) is a global investment banking and capital markets firm that provides advisory services, securities trading, and asset management to corporations, institutions, and wealthy individuals.
Revenue Growth
A company’s long-term performance is an indicator of its overall quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Unfortunately, Jefferies struggled to consistently increase demand as its $8.51 billion of revenue for the trailing 12 months was close to its revenue five years ago. This wasn’t a great result and suggests it’s a low quality business.
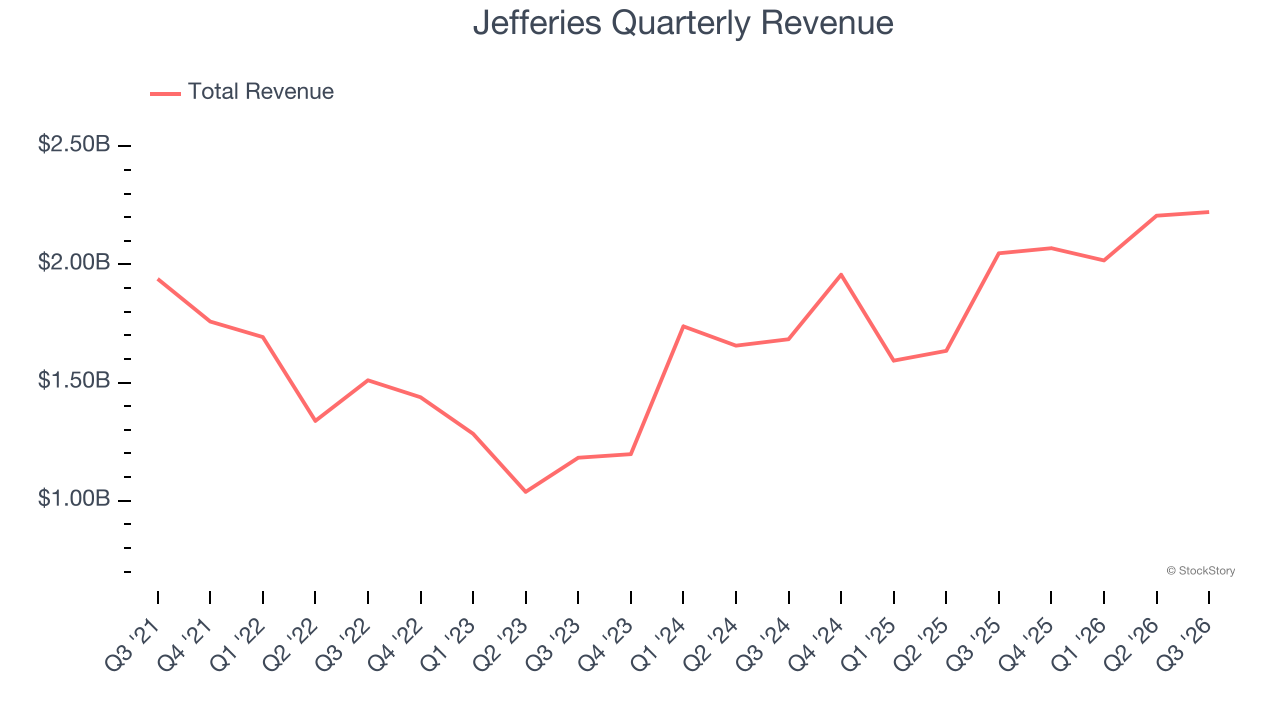
We at StockStory place the most emphasis on long-term growth, but within financials, a half-decade historical view may miss recent interest rate changes, market returns, and industry trends. Jefferies’s annualized revenue growth of 16.5% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 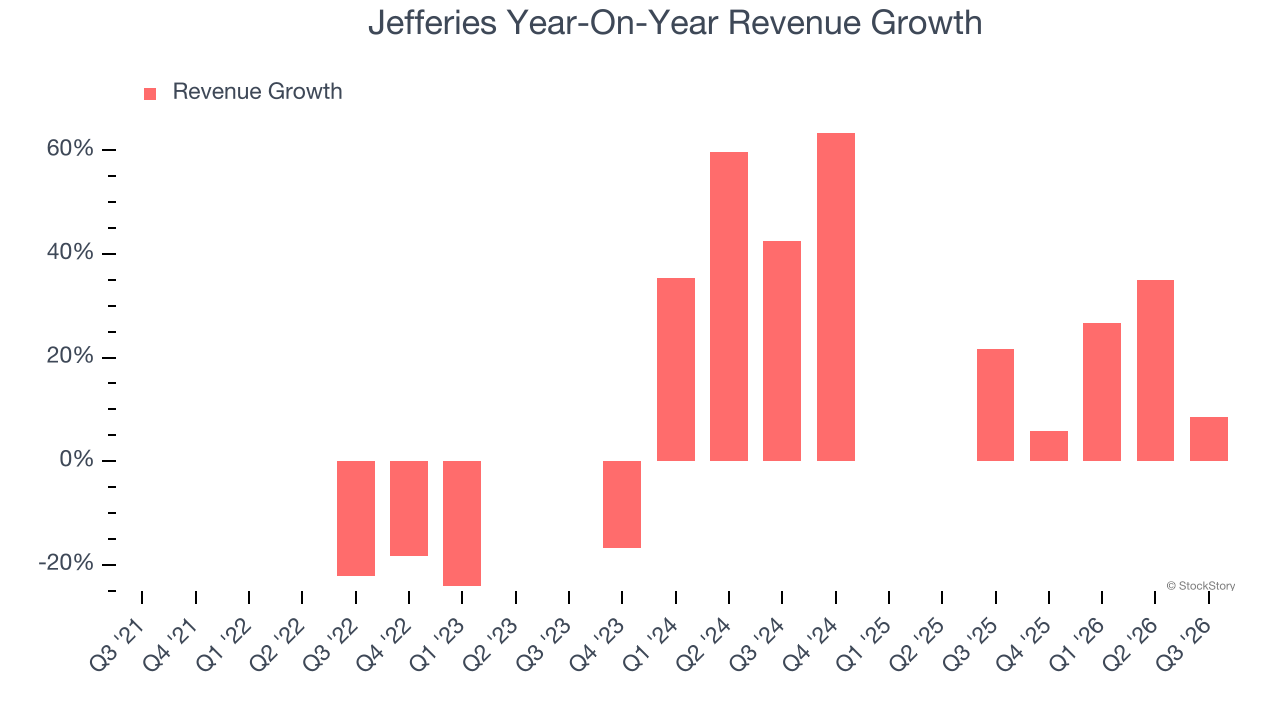 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Jefferies reported year-on-year revenue growth of 8.5%, and its $2.22 billion of revenue exceeded Wall Street’s estimates by 1.1%.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Tangible Book Value Per Share (TBVPS)
Financial institutions with multiple business lines manage complex balance sheets that span various financial activities. Market valuations reflect this operational complexity, prioritizing balance sheet strength and sustainable book value growth across all business segments.
This is why we consider tangible book value per share (TBVPS) an important metric for the sector. TBVPS represents the real net worth per share across all business segments, providing a clear measure of shareholder equity regardless of the complexity of operations. EPS can become murky due to the complexity of multiple revenue streams, acquisition impacts, or accounting flexibility across different financial services, and book value resists financial engineering manipulation.
Jefferies’s TBVPS was flat over the last five years and came it at $35.21 for the most recent quarter.
Key Takeaways from Jefferies’s Q3 Results
It was good to see Jefferies beat analysts’ EPS expectations this quarter. We were also happy its revenue narrowly outperformed Wall Street’s estimates. Overall, this print had some key positives. The market seemed to be hoping for more, and the stock traded down 3% to $45.76 immediately following the results.
So should you invest in Jefferies right now? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. We cover that in our actionable full research report which you can read here (it’s free).