


Why Scholar Rock Holding (SRRK) Is Back In The Spotlight
Scholar Rock Holding (SRRK) drew investor attention after recent trading left the share price at $48.63, with returns mixed between the past month, past 3 months, and the previous year.
Recent trading paints a mixed picture for Scholar Rock Holding, with the share price down 15.9% over the past month but still up 13.6% year to date. The 1-year total shareholder return of 26.8% and a very large 3-year total shareholder return suggest longer term momentum has been strong even as near term sentiment cools.
Scan how Scholar Rock Holding compares with other rare-disease developers by reviewing our curated list of 38 healthcare AI stocks benefiting from renewed interest in specialist healthcare breakthroughs.
Scholar Rock Holding now trades near the top of its recent range after a sharp multi year run and a choppy past quarter. Does that recent swing still leave enough upside potential to justify the risk investors are taking?
Preferred Price-to-Book of 23.3x: Is it justified?
On current data, Scholar Rock Holding screens as expensive on traditional valuation checks, with a price at $48.63 and a P/B ratio of 23.3x. A DCF fair value estimate of $223.92 points in the opposite direction.
The price to book ratio compares the market value of the equity to the accounting value of net assets on the balance sheet. For a drug developer like Scholar Rock Holding with minimal reported revenue and ongoing losses, that multiple reflects what investors are willing to pay today for a pipeline, intellectual property, and future cash flows that do not yet show up in book value.
The 23.3x P/B figure is far above the peer average of 7.2x and well beyond the wider US Biotechs industry at 2.1x. The gap suggests the market is paying a premium for this pipeline relative to both direct peers and the sector. It also sets a high bar for future execution to keep justifying that pricing.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-book of 23.3x (OVERVALUED)
Still, the Scholar Rock Holding story can break if key drug trials disappoint or if continued net losses of $408.591 million strain funding options.
Find out about the key risks to this Scholar Rock Holding narrative.
Another View on Scholar Rock Holding’s valuation
The book value check paints Scholar Rock Holding as expensive, yet the SWS DCF model points the other way. On that framework, a fair value of $223.92 against a $48.63 share price suggests the stock trades at a steep discount. Which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
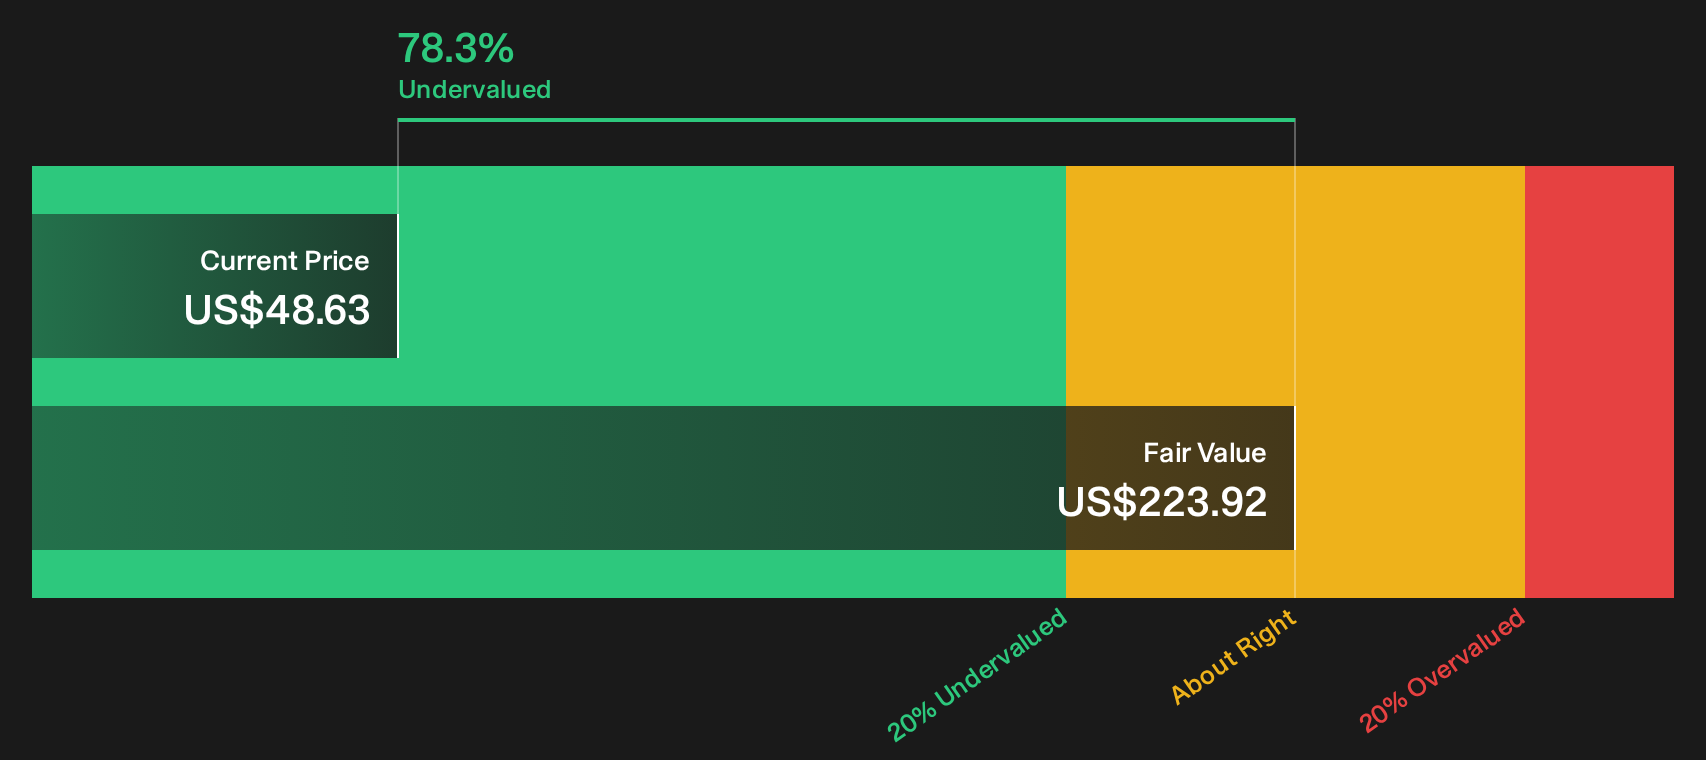
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Scholar Rock Holding for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Scholar Rock Holding’s valuation can feel confusing, so it makes sense to move quickly and look through the data yourself before taking a stance. To weigh both the concerns and the upside potential that investors are focused on, start by reviewing the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Scholar Rock Holding?
Once you have a view on Scholar Rock Holding, do not leave the rest of your watchlist to chance. Fresh opportunities often sit just one screen away.
- Target resilient balance sheets by scanning our list of solid balance sheet and fundamentals (24 results) to highlight businesses backed by stronger financial foundations.
- Hunt for quality at a discount using the 32 high quality undervalued stocks to spot companies where fundamentals and price still look out of sync.
- Build a steadier income stream by reviewing the 7 dividend fortresses to focus on higher yielding payers with more robust profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com