


Should Higher Dividend Payout Require Action From CITIC (SEHK:267) Investors?
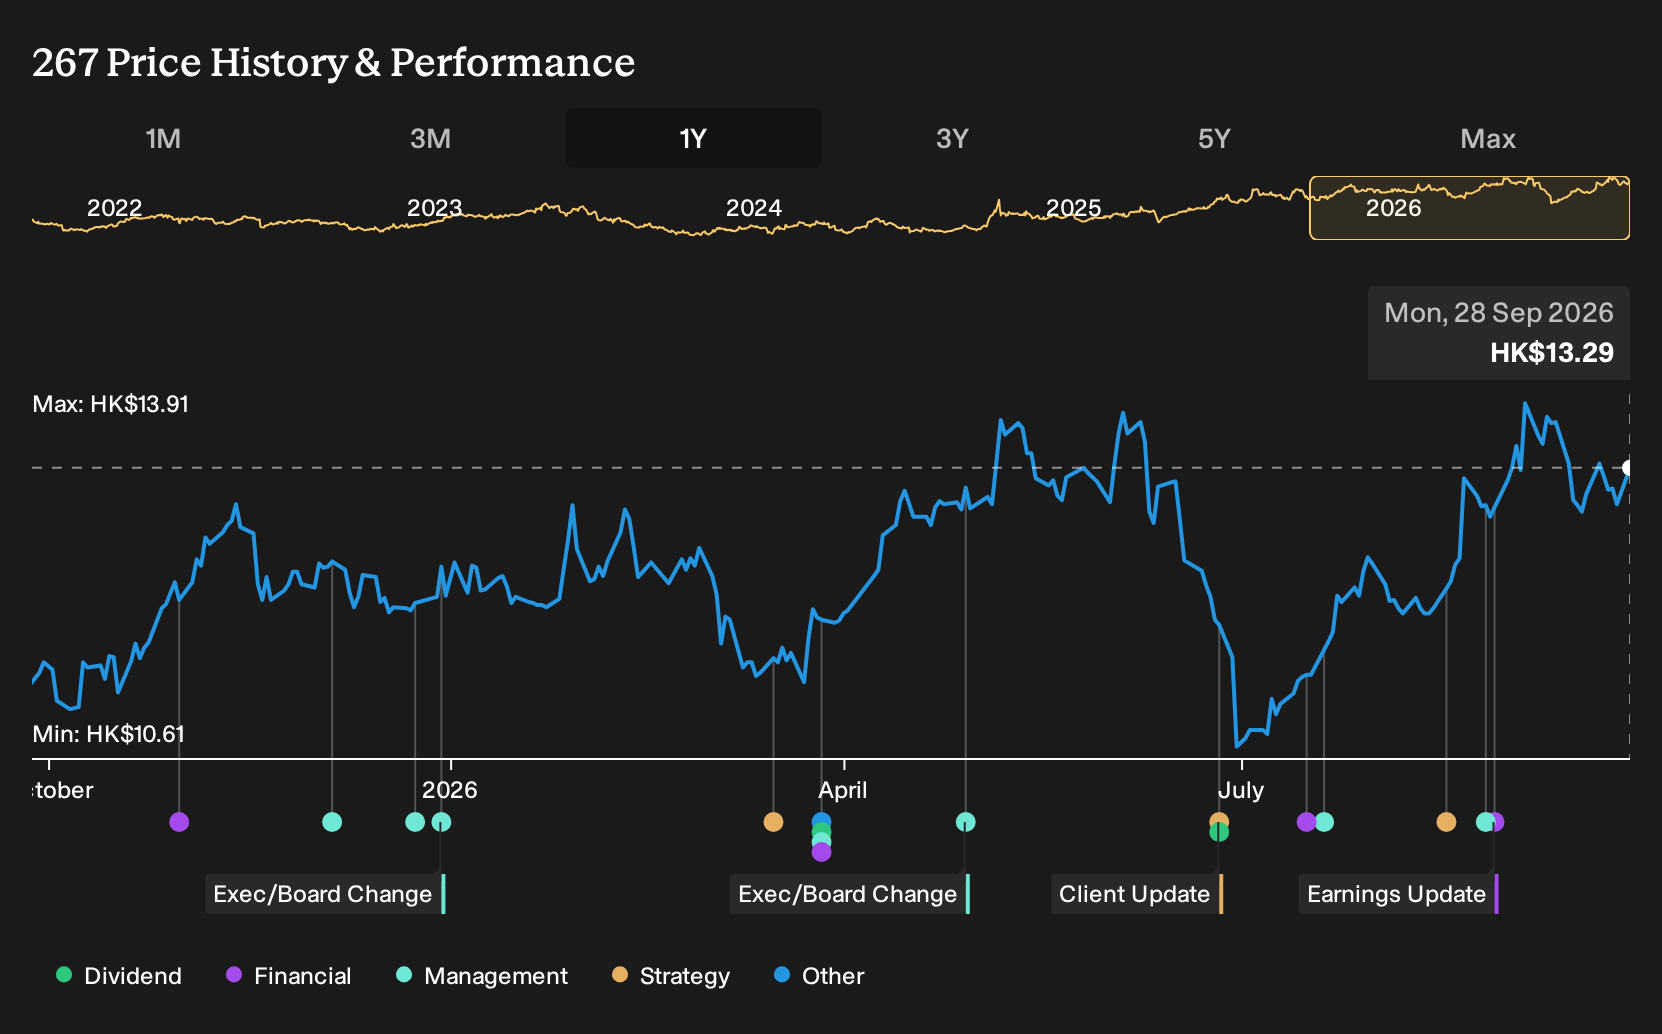
- CITIC has outlined plans to lift its dividend payout ratio to at least 30% by 2026 and to push harder into overseas markets, with an emphasis on Belt and Road regions and developed economies.
- The combination of a higher future dividend commitment and a clearer international agenda points to how CITIC is aiming to balance cash returns with broader earnings potential across its diverse business lines.
- This article will examine how CITIC's investment narrative is shaped by the higher future dividend payout commitment alongside its wider international push.
Scan beyond CITIC and line up other income and expansion stories by running the hand picked 159 dividend fortresses alongside this dividend and overseas pivot.
CITIC Investment Narrative Recap
CITIC appeals if you think a broad mix of finance, materials, manufacturing and consumption can keep generating steady cash, even while some areas stay under pressure. The short term swing factor is execution on its overseas push and high growth segments, while keeping earnings quality intact as revenue is expected to drift lower over the next few years.
The biggest near term risk still sits in exposure to Chinese real estate and local government related credit. That, combined with funding that leans on external borrowing, keeps balance sheet discipline front of mind. The latest news around dividends and expansion does not remove those core financial and macro sensitivities.
The clearest recent announcement tied to this story is CITIC’s plan to lift its dividend payout ratio to at least 30% by 2026. That commitment pulls more focus onto the stability of net profit, the health of cash generation and how much volatility might come from the financial and property related operations.
For you as a shareholder, this means the dividend pledge and international growth ambitions become part of the same test. CITIC needs to keep earnings resilient while managing geopolitical risk, weaker pockets such as Brazilian seeds and domestic auto price competition, and a pressured Chinese property market. Execution on overseas revenue growth and technology investment will likely frame how durable that higher payout looks over time.
CITIC Earnings Assumptions Behind The Dividend And Overseas Push
CITIC's narrative projects CN¥856.1b revenue and CN¥71.0b earnings by 2029. That profile is built on revenue declining 3.2% a year and an earnings increase of about CN¥12.3b from CN¥58.7b today.
Those analyst assumptions matter if you are weighing the higher dividend payout against the overseas growth story. Forecast earnings of CN¥71.0b by 2029 need to support both a larger cash distribution and the funding of new projects across Belt and Road regions and mature markets.
Profit margins are expected to move from 6.2% today to 8.3% over the next three years. In simple terms, the view is that CITIC can squeeze more profit out of a slightly smaller top line, helped by mix, efficiency gains and a greater tilt toward higher margin activities.
The projection for a 7.1x P/E on those 2029 earnings, compared with 5.2x today, implies investors would need to be comfortable paying a higher multiple of profit than now, but still below the current valuation level for the broader Hong Kong industrials sector at 8.7x. That sits alongside the planned dividend uplift as part of a joined up story about how the market might price CITIC's cash flows.
Flat share count assumptions keep the focus on operating performance rather than financial engineering. If earnings reach CN¥71.0b with the number of shares broadly unchanged, any dividend per share tied to a 30% or higher payout ratio would track more closely to the underlying profit trend.
For you as an investor, the practical question is whether a revenue line that is expected to drift lower, but with better margins, feels consistent with CITIC's plan to push harder overseas and lean into technology and higher value segments. The answer shapes how comfortable you might be relying on that future payout while the business works through property exposure, funding costs and a more complex international footprint.
Uncover why CITIC's fair value indicates a 5% potential upside to its current price. This suggests a discount that could narrow more quickly than many investors anticipate.
Exploring Other Perspectives
Community fair value views on CITIC from the Simply Wall St Community span from HK$13.90 to about HK$995, across 2 separate estimates. This signals very different conviction levels. Set that against real world risks like property exposure, trade restrictions and weaker autos or seeds, and there are plenty of reasons to compare multiple viewpoints before deciding how dependable the current narrative feels.
Explore another CITIC fair value estimate, including one that suggests it could be worth just HK$13.90.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis.
- A great starting point for your CITIC research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for CITIC. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CITIC's overall financial health at a glance.
Looking for more investment ideas beyond CITIC?
If the CITIC story has sharpened your thinking about income, risk and international growth, it can be useful to set it alongside other businesses with different profiles but comparable trade offs.
- If you want income to play a bigger role in your portfolio, scan a curated set of higher yielding payers through 159 dividend fortresses.
- If value is your main filter, line up CITIC next to companies that look mispriced on quality and cash generation using the 194 high quality undervalued stocks.
- If capital protection matters most, stress test your ideas against companies with more resilient balance sheets and lower risk scores via the 226 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com