


Blackstone Mortgage Trust (BXMT), Why Is It Back In Focus?
Blackstone Mortgage Trust (BXMT) has affirmed a quarterly dividend of $0.47 per share for its class A common stock, payable on October 15, 2026, to shareholders of record as of September 30.
Viewed against that backdrop, Blackstone Mortgage Trust’s latest dividend confirmation lands at a time when the US$12.50 share price has seen pressure, with the stock down 26.25% on a 3 month share price return and the 1 year total shareholder return also declining 26.21%. This suggests recent momentum has been fading rather than building.
Scan beyond Blackstone Mortgage Trust and compare its recent share price and dividend profile against a curated set of 8 dividend fortresses to see how other income-focused stocks are holding up.
So is the slide in Blackstone Mortgage Trust mainly a verdict on its commercial real estate loan book and earnings profile, or does the scale of the drop point more to shifting sentiment that could reshape how the shares are valued next?
Most Popular Narrative: 40.5% Undervalued
On the most followed view, Blackstone Mortgage Trust’s fair value of $21 sits well above the recent $12.50 close. This puts the current selloff against a narrative that still sees material upside if the thesis holds.
The company is focusing on portfolio turnover through repayments and redeployment into high-quality new credit opportunities, which is expected to enhance future earnings by improving the overall credit composition and potentially increasing revenue from new investments. Resolution of impaired loans is expected to be a catalyst for future growth by reducing the non-performing assets and allowing the company to recapture earnings potential, thereby potentially increasing net margins as capital is redeployed into more productive investments.
See why 6 investors see Blackstone Mortgage Trust as 40% undervalued.
Result: Fair Value of $21 (UNDERVALUED)
Still, a prolonged drag from the US$970 million of impaired loans, or slower than expected loan repayments and redeployment, could quickly challenge the Blackstone Mortgage Trust upside story.
Find out about the key risks to this Blackstone Mortgage Trust narrative.
Another View On Blackstone Mortgage Trust Valuation
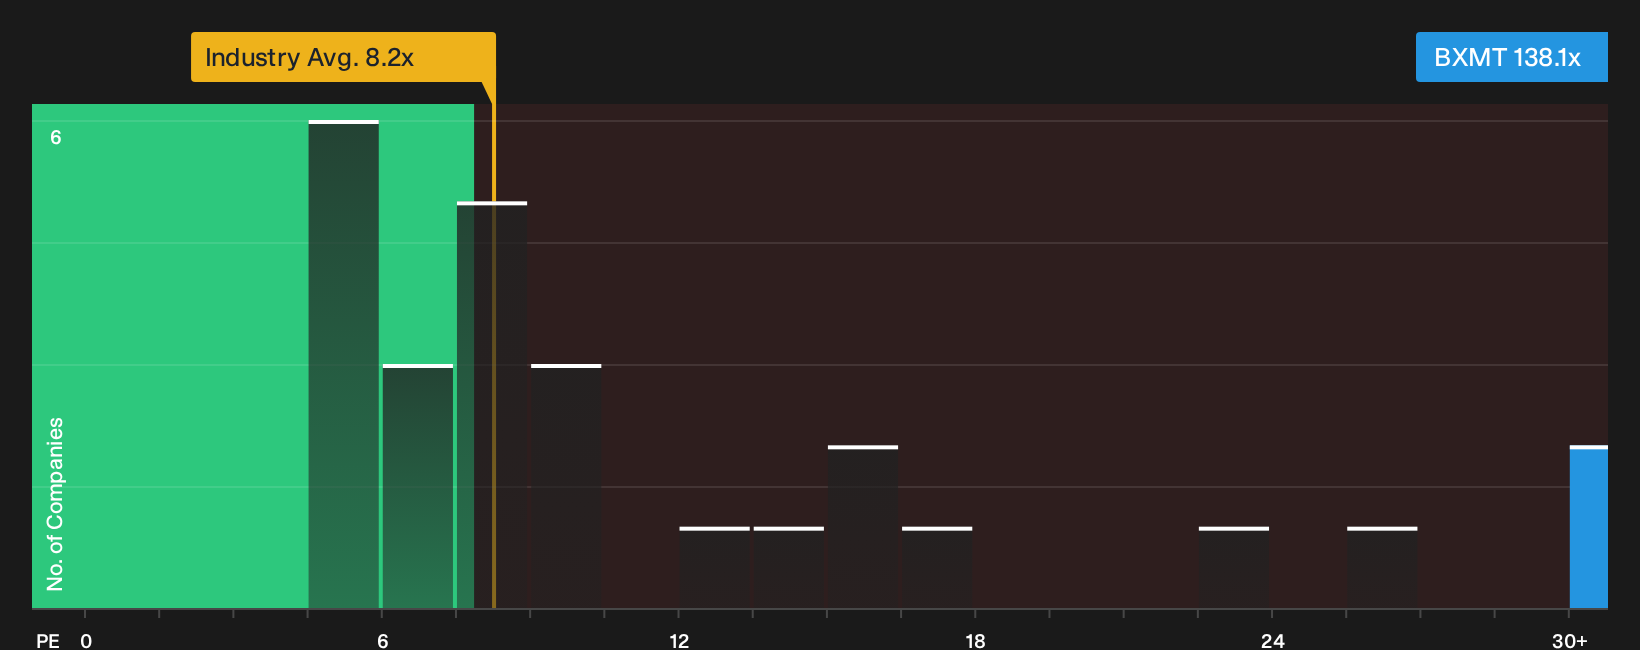
The earlier fair value story for Blackstone Mortgage Trust leans on analyst earnings forecasts and price targets. A simple P/E check tells a very different story. BXMT trades on about 138.1x earnings, while the US Mortgage REITs industry is around 8.2x and similar peers average 13.9x. The fair ratio is 49.3x, which is closer to peers yet still far below the current level, so anyone buying at today’s multiple is taking on clear valuation risk if sentiment normalises.
See what the numbers say about this price in context, including how the market could move toward that fair ratio, in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Blackstone Mortgage Trust so far? If the combination of pressure and potential has you curious, act quickly, review the data available, and weigh the full picture for yourself with 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Blackstone Mortgage Trust?
If Blackstone Mortgage Trust has sharpened your focus on valuation and income, do not stop here when a wider universe of opportunities is just a few clicks away.
- Target potential value opportunities by scanning a curated set of 32 high quality undervalued stocks that may offer better risk and reward trade offs for your portfolio.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (24 results) where financial strength supports more durable business models through different market conditions.
- Get early to promising stories by checking a fresh pool of 16 high quality undiscovered gems before they reach every watchlist on the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com